- Latest available (Revised)
- Original (As enacted)
Income and Corporation Taxes Act 1988
You are here:
- UK Public General Acts
- 1988 c. 1
- Whole Act
- Previous
- Next

What Version
Advanced Features
- Show Geographical Extent(e.g. England, Wales, Scotland and Northern Ireland)
- Show Timeline of Changes
Opening Options
More Resources
Changes over time for: Income and Corporation Taxes Act 1988
Alternative versions:
- 01/02/1991- Amendment
- 28/02/1991- Amendment
- 04/03/1991- Amendment
- 06/03/1991- Amendment
- 11/03/1991- Amendment
- 19/03/1991- Amendment
- 28/03/1991- Amendment
- 01/04/1991- Amendment
- 06/04/1991- Amendment
- 19/04/1991- Amendment
- 25/04/1991- Amendment
- 16/05/1991- Amendment
- 15/07/1991- Amendment
- 25/07/1991- Amendment
- 27/08/1991- Amendment
- 01/09/1991- Amendment
- 25/09/1991- Amendment
- 01/10/1991- Amendment
- 25/10/1991- Amendment
- 01/01/1992- Amendment
- 03/02/1992- Amendment
- 06/03/1992- Amendment
- 16/03/1992- Amendment
- 01/04/1992- Amendment
- 06/04/1992- Amendment
- 01/07/1992- Amendment
- 16/07/1992- Amendment
- 01/09/1992- Amendment
- 15/09/1992- Amendment
- 02/10/1992- Amendment
- 16/10/1992- Amendment
- 01/11/1992- Amendment
- 01/12/1992- Amendment
- 01/02/1993- Amendment
- 19/02/1993- Amendment
- 06/03/1993- Amendment
- 29/03/1993- Amendment
- 01/04/1993- Amendment
- 06/04/1993- Amendment
- 27/07/1993- Amendment
- 01/08/1993- Amendment
- 30/08/1993- Amendment
- 30/11/1993- Amendment
- 31/12/1993- Amendment
- 01/01/1994- Amendment
- 07/02/1994- Amendment
- 06/04/1994- Amendment
- 03/05/1994- Amendment
- 30/05/1994- Amendment
- 01/09/1994- Amendment
- 31/10/1994- Amendment
- 01/11/1994- Amendment
- 29/11/1994- Amendment
- 03/01/1995- Amendment
- 10/01/1995- Amendment
- 31/03/1995- Amendment
- 01/04/1995- Amendment
- 06/04/1995- Amendment
- 01/05/1995- Amendment
- 23/05/1995- Amendment
- 19/07/1995- Amendment
- 31/07/1995- Amendment
- 01/10/1995- Amendment
- 08/11/1995- Amendment
- 01/01/1996- Amendment
- 01/04/1996- Amendment
- 06/04/1996- Amendment
- 19/04/1996- Amendment
- 29/04/1996- Amendment
- 28/05/1996- Amendment
- 22/08/1996- Amendment
- 02/09/1996- Amendment
- 24/09/1996- Amendment
- 01/10/1996- Amendment
- 07/10/1996- Amendment
- 08/10/1996- Amendment
- 14/10/1996- Amendment
- 26/11/1996- Amendment
- 25/02/1997- Amendment
- 19/03/1997- Amendment
- 01/04/1997- Amendment
- 06/04/1997- Amendment
- 28/04/1997- Amendment
- 27/05/1997- Amendment
- 02/07/1997- Amendment
- 31/07/1997- Amendment
- 24/10/1997- Amendment
- 05/01/1998- Amendment
- 17/03/1998- Amendment
- 01/04/1998- Amendment
- 02/07/1998- Amendment
- 31/07/1998- Amendment
- 01/10/1998- Amendment
- 01/11/1998- Amendment
- 15/02/1999- Amendment
- 25/02/1999- Amendment
- 01/04/1999- Amendment
- 06/04/1999- Amendment
- 19/04/1999- Amendment
- 16/06/1999- Amendment
- 01/07/1999- Amendment
- 27/07/1999- Amendment
- 05/10/1999- Amendment
- 15/10/1999- Amendment
- 01/11/1999- Amendment
- 21/03/2000- Amendment
- 01/04/2000- Amendment
- 06/04/2000- Amendment
- 24/04/2000- Amendment
- 25/04/2000- Amendment
- 28/07/2000- Amendment
- 01/08/2000- Amendment
- 01/09/2000- Amendment
- 28/09/2000- Amendment
- 01/10/2000- Amendment
- 31/12/2000- Amendment
- 22/03/2001- Amendment
- 26/03/2001- Amendment
- 06/04/2001- Amendment
- 01/05/2001- Amendment
- 11/05/2001- Amendment
- 09/11/2001- Amendment
- 01/12/2001- Amendment
- 03/12/2001- Amendment
- 27/03/2002- Amendment
- 01/04/2002- Amendment
- 06/04/2002- Amendment
- 17/06/2002- Amendment
- 27/06/2002- Amendment
- 02/07/2002- Amendment
- 08/07/2002- Amendment
- 24/07/2002- Amendment
- 01/10/2002- Amendment
- 10/10/2002- Amendment
- 28/10/2002- Amendment
- 27/11/2002- Amendment
- 01/12/2002- Amendment
- 30/12/2002- Amendment
- 23/01/2003- Amendment
- 03/03/2003- Amendment
- 31/03/2003- Amendment
- 06/04/2003- Amendment
- 09/04/2003- Amendment
- 10/07/2003- Amendment
- 25/07/2003- Amendment
- 15/09/2003- Amendment
- 27/11/2003- Amendment
- 01/04/2004- Amendment
- 06/04/2004- Amendment
- 02/07/2004- Amendment
- 22/07/2004- Amendment
- 29/07/2004- Amendment
- 08/09/2004- Amendment
- 28/09/2004- Amendment
- 01/10/2004- Amendment
- 15/11/2004- Amendment
- 28/11/2004- Amendment
- 02/12/2004- Amendment
- 31/12/2004- Amendment
- 01/01/2005- Amendment
- 16/03/2005- Amendment
- 01/04/2005- Amendment
- 06/04/2005- Amendment
- 07/04/2005- Amendment
- 18/04/2005- Amendment
- 06/05/2005- Amendment
- 07/05/2005- Amendment
- 20/07/2005- Amendment
- 27/09/2005- Amendment
- 05/10/2005- Amendment
- 05/12/2005- Amendment
- 06/01/2006- Amendment
- 30/03/2006- Amendment
- 01/04/2006- Amendment
- 06/04/2006- Amendment
- 09/06/2006- Amendment
- 19/07/2006- Amendment
- 11/08/2006- Amendment
- 31/12/2006- Amendment
- 01/01/2007- Amendment
- 08/01/2007- Amendment
- 01/03/2007- Amendment
- 01/04/2007- Amendment
- 06/04/2007- Amendment
- 17/04/2007- Amendment
- 19/07/2007- Amendment
- 13/08/2007- Amendment
- 01/09/2007- Amendment
- 01/10/2007- Amendment
- 29/11/2007- Amendment
- 27/12/2007- Amendment
- 03/01/2008- Amendment
- 18/02/2008- Amendment
- 19/02/2008- Amendment
- 01/04/2008- Amendment
- 06/04/2008- Amendment
- 21/07/2008- Amendment
- 12/08/2008- Amendment
- 29/10/2008- Amendment
- 01/12/2008- Amendment
- 27/12/2008- Amendment
- 03/02/2009- Amendment
- 01/04/2009- Amendment
- 06/04/2009- Amendment
- 22/04/2009- Amendment
- 23/04/2009- Amendment
- 21/07/2009- Amendment
- 13/08/2009- Amendment
- 01/10/2009- Amendment
- 21/10/2009- Amendment
- 11/11/2009- Amendment
- 01/12/2009- Amendment
- 01/01/2010- Amendment
- 01/04/2010- Amendment
- 06/04/2010- Amendment
- 08/04/2010- Amendment
- 27/07/2010- Amendment
- 16/12/2010- Amendment
- 01/04/2011- Amendment
- 19/07/2011- Amendment
- 01/04/2012- Amendment
- 17/07/2012- Amendment
- 31/01/2013- Amendment
- 01/04/2013- Amendment
- 06/04/2013- Amendment
- 17/07/2013- Amendment
- 19/07/2013- Amendment
- 01/08/2014- Amendment
- 22/08/2014- Amendment
- 12/08/2016- Amendment
- 15/09/2016- Amendment
- 06/04/2017- Amendment
- 17/07/2017- Amendment
- 16/11/2017- Amendment
- 12/02/2019- Amendment
- 01/04/2019- Amendment
- 05/07/2019- Amendment
- 05/10/2020- Amendment
- 14/07/2022- Amendment
- 06/04/2024- Amendment
- 20/03/2025- Amendment
- 01/04/2026- Amendment
Changes to legislation:
Income and Corporation Taxes Act 1988 is up to date with all changes known to be in force on or before 28 September 2026. There are changes that may be brought into force at a future date. Changes that have been made appear in the content and are referenced with annotations.
View outstanding changesChanges and effects yet to be applied to :
- Act Tax Acts: power to modify conferred by 2004 c. 25 s. 18
- s. 266 repealed by 2012 c. 14 Sch. 39 para. 28(1)
- s. 266A repealed by 2012 c. 14 Sch. 39 para. 28(1)
- s. 274 repealed by 2012 c. 14 Sch. 39 para. 28(1)
- s. 824(2D)(b) repealed by 2012 c. 14 Sch. 39 para. 28(1)
- s. 824(3)(ad) repealed by 2012 c. 14 Sch. 39 para. 28(1)
- s. 826(1)(f)-(fb) omitted by 2024 c. 3 Sch. 2 para. 9(2)
- s. 826(3C) words omitted by 2024 c. 3 Sch. 2 para. 9(3)
- s. 826(8A)(b)(ii) words omitted by 2024 c. 3 Sch. 2 para. 9(4)
- s. 826(8BA) words omitted by 2024 c. 3 Sch. 2 para. 9(5)
- s. 842(4) words inserted by 2009 c. 10 Sch. 22 para. 11(2)
- Sch. 14 repealed by 2012 c. 14 Sch. 39 para. 28(1)
- Sch. 15 para. 8 words repealed by 2012 c. 14 Sch. 39 para. 28(1)
Changes and effects yet to be applied to the whole Act associated Parts and Chapters:
- Act Tax Acts: power to modify conferred by 2004 c. 25 s. 18
Income and Corporation Taxes Act 1988
1988 CHAPTER 1
An Act to consolidate certain of the enactments relating to income tax and corporation tax, including certain enactments relating also to capital gains tax; and to repeal as obsolete section 339(1) of the Income and Corporation Taxes Act 1970 and paragraphs 3 and 4 of Schedule 11 to the Finance Act 1980.
[9th February 1988]X1
Editorial Information
X1EDITORIAL NOTE
The originating text of this Act is derived from the 1990 edition of The Taxes Acts edited by the Inland Revenue and published by Her Majesty's Stationery Office. The style of editing followed in older versions of the revised text may therefore differ from that applicable to most other Acts published in the online edition of the revised statutes. Any references in older footnote annotations to Vol. 1, 2 etc. are to the Volumes of that 1990 edition.
References to Acts in sidenotes and footnote annotations may be abbreviated. The main abbreviations used are listed below. Where a reference to an Act consists of the year, or the year and a series number (such as "1975", or "1975 (No. 2)", etc.), without any following letter(s) in parentheses, the reference is in most cases to the Finance Act, or Finance (No. 2) Act, etc., of that year. Exceptions to this are 1952, 1970, and 1988 (as to which see the list below).
ABBREVIATIONS USED IN SIDENOTES AND FOOTNOTES
1828 (R.S.) = Revenue Solicitors Act 1828 (c. 25, SIF 57)
1890 (I.R.R.) = Inland Revenue Regulation Act 1890 (c. 21, SIF 63:1)
1952 = Income Tax Act 1952 (c. 10, SIF 63:1)
1968 (C) = Capital Allowances Act 1968 (c. 3)
1970 (M) = Taxes Management Act 1970 (c. 9, SIF 63:1)
1970 = Income and Corporation Taxes Act 1970 (c. 10, SIF 63:1)
1970 (F) = Finance Act 1970 (c. 24, SIF 63:1,2)
1970 (No.2) = Income and Corporation Taxes (No.2) Act 1970 (c. 54)
1975 (O) = Oil Taxation Act 1975 (c. 22) (and similarly as respects subsequent years)
1976 (D) = Development Land Tax Act 1976 (c. 24)
1977 (I.T.R.) = Finance (Income Tax Reliefs) Act 1977 (c. 53)
1979 (C) = Capital Gains Tax Act 1979 (c. 14, SIF 63:2)
1984 (C) = Capital Transfer Tax Act 1984/Inheritance Tax Act 1984 (c. 51, SIF 65)
1988 = Income and Corporation Taxes Act 1988 (c. 1, SIF 63:1)
1988 (F) = Finance Act 1988 (c. 39, SIF 63:1,2)
1990 (C) = Capital Allowances Act 1990 (c. 1, SIF 63:1)
O.J. = Official Journal of the European Communities
SIF = Statutes in Force, the official hard-copy predecessor to the online statutes (and any following numbers refer to the relevant volume)
Modifications etc. (not altering text)
C1General amendments, modifications, etc. to Tax Acts (or Income Tax Acts or Corporation Taxes Acts as the case may be):
Taxes Management Act 1970 (c.9, SIF 63:1), s. 41A(7) (as added by Finance Act 1990 (c.29, SIF 63:1), s. 95(1)(2));
British Telecommunications Act 1981 (c.38, SIF 96), s. 82(2)(7);
Telecommunications Act 1984 (c.12, SIF 96), s. 72(3);
Finance Act 1984 (c.43, SIF 63:1), ss. 82(6), 85(2), 89(1)(7), 96(1)(7), 98(7), Sch. 9 para. 3(2)(9), Sch. 16 paras. 6, 12;
Finance Act 1985 (c.54, SIF 63:1), ss. 72(1), 74(5), Sch. 23 para. 15(4);
The Income Tax (Entertainers and Sportsmen) Regulations 1987 (S.I. 1987/530), regs. 11(2), 13(1), 14;
Income and Corporation Taxes Act 1988 (c.1, SIF 63:1), ss. 4, 6, 7, 9, 32, 34, 78, 134, 135, 141, 142, 185, 191, 193, 194, 195, 200, 203, 209, 212, 213, 219, 247, 253, 272, 287, 314, 315, 317, 318, 325, 326, 327, 345, 350, 351, 368, 375, 381, 397, 414, 432, 440, 442, 446, 458, 460, 461, 463, 463(2)(3) (as added by Finance Act 1990 (c.29, SIF 63:1), s. 50(2)), 468, 474, 475, 486, 490, 491, 503, 511, 518, 524, 532, 544, 550, 556, 558, 569, 572, 582, 595, 601, 613, 617, 619, 621, 639, 656, 660, 663, 676, 689, 691, 694, 700, 701, 714, 716, 739, 743, 754, 763, 776, 780, 781, 782, 787, 789, 811, 828, 829, 832, 833, 834, 835, 837, 838, 839, 840, 841, 842, Sch. 2 para. 5, Sch. 4 para. 5, Sch. 13 para. 10, Sch. 16 para. 10, Sch. 21 para. 6, Sch. 26 para. 1, Sch. 27 para. 20;
Finance Act 1988 (c.39, SIF 63:1), ss. 66, 127(1)(6), Sch. 12 para. 6;
Electricity Act 1989 (c. 29, SIF 44:1), s. 90, Sch. 11 para. 8(2); S.I. 1990/117, art. 3, Sch. 1;
Capital Allowances Act 1990 (c.1, SIF 63:1), ss. 28(1), 68(8), 74, 82, 83(5), 148(5), 163(4), 164(2); S.I. 1990/627;
Finance Act 1990 (c.29, SIF 63:1), s. 25(10);
Income and Corporation Taxes Act 1988 (c. 1, SIF 63:1), s. 84(3) (having effect with respect to gifts made on or after 19.3.1991), s. 587A(2)(3) (with application as referred to in Finance Act 1991 (c.31, SIF 63:1), s. 54, Sch. 12 para. 5 (if the new securities are issued on or after 19.3.1991)), s. 736A, Sch. 23A paras. 2(2), 3(2), 4(4), 5(2), 7(1);
Ports Act 1991 (c. 52, SIF 58), s. 35(8);
The Official Listing of Securities (Change of Competent Authority) Regulations 1991 (S.I. 1991/2000), regs. 1(1), 4(5);
British Technology Group Act 1991 (c.66, SIF 64), s.12(1)(3)(4); S.I. 1991/2721, art.2;
The Social Security (Contributions) Regulations 1979 (S.I. 1979/591), Sch. 1 reg. 28 (as substituted by S.I. 1992/97, reg. 18);
Social Security Contributions and Benefits Act 1992 (c. 4), ss. 16, 177(4), Sch.2 (with s. 108(5));
Taxation of Chargeable Gains Act 1992 (c. 12), ss. 209(3), 289 (with ss. 60, 101(1), 171, 201(3)) (with effect for the year 1992-93 and subsequent years of assessment);
The Lloyd's Underwriters (Tax) (1989-90) Regulations 1992 (S.I. 1992/511), reg.3 (with effect for the year of assessment 1989-90);
Finance (No. 2) Act 1992 (c. 48), ss. 66, 77, Sch. 12 paras. 6(2), 7, Sch. 17 para.9;
The Lloyd's Underwriters (Tax) (1990-91) Regulations 1993 (S.I. 1993/415), regs. 1(1), 3(1) (with effect for the year of assessment 1990-91);
Finance Act 1993 (c. 34), s. 78(3)-(5), 118(1), 146(2)(3), 165, 175, Sch. 20 paras. 8, 9(1);
Finance Act 1993 (c. 34), ss. 172(1), 176(1), 179(4)(5), 180(1)(a)(2), 182(2), 184(3) (with effect for the year 1992-93 and subsequent years of assessment);
Agriculture Act 1993 (c. 37), ss. 12, 36, Sch. 2, paras. 1, 2(1), 3(2), 16(2)(a), Sch. 4 para. 1(1);
The Income Tax (Manufactured Overseas Dividends) Regulations 1993 (S.I. 1993/2004), regs. 1, 4(1) , 5(1), 7(1), 8, 11(7);
Finance Act 1994 (c. 9), ss. 139(1)(2), 173(2)(b)(4)(a)(b), 174, Sch. 25 paras. 2, 6(1)(2);
Finance Act 1994 (c. 9), s. 252(1)(3), Sch. 24 paras. 1(4), 12(2), 15(1)(b), 18(1)-(4), 20(1)(a)(3), 25(1) (with retrospective effect to 11.1.1994);
Coal Industry Act 1994 (c. 21), ss. 21, 68(4), Sch. 4 paras. 11(1), 14, 17(2)-(4), 19(1)(a)(3); S.I. 1994/2189, art. 2, Sch.;
The Lloyd's Underwriters (Tax) (1991-92) Regulations 1994 (S.I. 1994/728), reg.3 (with effect for the year of assessment 1991-92);
Finance Act 1995 (c. 4), ss. 152, 157(12);
Finance Act 1995 (c. 4), s. 154 (with retrospective effect to 29.11.1994);
Income and Corporation Taxes Act 1988 (c. 1), Sch. 5A (as inserted by Finance Act 1995 (c. 4), s. 85(2)(3), Sch. 19);
Crown Agents Act 1995 (c. 24), s. 7(3)-(5);
Atomic Energy Authority Act 1995 (c. 37), s. 8, Sch. 3 paras. 1, 2, 7, 13;
Gas Act 1995 (c. 45), s. 17(1)(2), Sch. 5 paras. 1, 10(1)-(3);
The Friendly Societies (Taxation of Transfers of Business) Regulations 1995 (S.I. 1995/171), reg. 3;
The Lloyd's Underwriters (Tax) Regulations 1995 (S.I. 1995/351), reg. 4 (with regs. 5-8 and S.I. 1995/352, regs. 6-12, 14, 15);
The Lloyd's Underwriters (Tax) (1992-93 to 1996-97) Regulations 1995 (S.I. 1995/352), regs. 1, 4 (with regs. 6-12, 14, 15 and S.I. 1995/351, regs. 5-8) (with effect for the years of assessment 1992-93 to 1996-97);
The Income Tax (Manufactured Dividends) (Tradepoint) Regulations 1995 (S.I. 1995/2052), regs. 1, 10;
Finance Act 1996 (c. 8), ss. 81(1), 151(1), 152, 154(2)(5)(9), Sch. 10 para. 4(2), Sch. 11 para. 4(4);
Income and Corporation Taxes Act 1988 (c. 1), s. 689A(2) (as inserted by Finance Act 1996 (c. 8), Sch. 6 paras. 16, 28);
Broadcasting Act 1996 (c. 55), Sch. 7 paras. 1(3), 18, 27;
Finance Act 1997 (c. 16), s. 79(3), Sch. 7 paras. 2(1)(3), 3(2)(5), 7(2);
Income and Corporation Taxes Act 1988 (c. 1), Sch. 23A paras. 3, 8(2A) (as substituted and inserted respectively by Finance Act 1997 (c. 16), Sch. 10 paras. 11(1), 13(3), 16);
Capital Allowances Act 1990 (c. 1), ss. 28A, 29(1)(1A) (as inserted and substituted respectively by Finance Act 1997 (c. 16), Sch. 15 paras. 3, 4)
Finance (No. 2) Act 1997 (c. 58), s. 29(1), Sch. 6 para. 23;
Income and Corporation Taxes Act 1988 (c. 1), s. 1A(5) (as substituted by Finance (No. 2) Act 1997 (c. 58), s. 31(4)(6);
The Friendly Societies (Modification of the Corporation Tax Acts) Regulations 1997 (S.I. 1997/473), reg. 3 (as amended by S.I. 2001/3629, art. 165(2)(a); S.I. 2004/822, reg. 4)
The Open-ended Investment Companies (Tax) Regulations 1997 (S.I. 1997/1154), regs. 1, 3-23 (as amended by S.I. 1997/1715);
The Lloyd's Underwriters (Scottish Limited Partnerships) (Tax) Regulations 1997 (S.I. 1997/2681), regs. 1, 9;
Teaching and Higher Education Act 1998 (c. 30), s. 22(5)(g);
Finance Act 1998 (c. 36), ss. 30(3), 31(2), 32(8), 46, 47(3)(a), 117, 161(2)(b)(7), Sch. 18;
Income and Corporation Taxes Act 1988 (c. 1), ss. 65A(3), 70A(3), 596C, 754(2), Sch. 28AA para. 6(2)(b) (as inserted or substituted (as the case may be) by Finance Act 1998 (c. 36), ss. 38, 93(3)(4), 108(5)(6), Sch. 5 paras. 24, 25, 73, Sch. 16, Sch. 17 paras. 9(4), 37;
Regional Development Agencies Act 1998 (c. 45), s. 38; S.I. 1998/2952, art. 2(2);
Scotland Act 1998 (c. 46), s. 73(2); S.I. 1998/3178, art. 2(2), Sch. 3;
The European Single Currency (Taxes) Regulations 1998 (S.I. 1998/3177), regs. 1, 21;
Finance Act 1999 (c. 16), s. 68(4);
Income and Corporation Taxes Act 1988 (c. 1), s. 469A (as inserted by Finance Act 1999 (c. 16), s. 68(1)(3));
Commonwealth Development Corporation Act 1999 (c. 20), ss. 6(2)(c), 16(1)(4)(c)(5);
Finance Act 2000 (c. 17), Sch. 14 para. 43;
Income and Corporation Taxes Act 1988 (c. 1), s. 587B(2)(b) (as inserted by Finance Act 2000 (c. 17), s. 43(1)(3));
Capital Allowances Act 2001 (c. 2), ss. 253(4), 260(5), 579, Sch. 3 paras. 54, 55;
Income and Corporation Taxes Act 1988 (c. 1), s. 118ZA (as substituted by Finance Act 2001 (c. 9), s. 75(1)(6));
Finance Act 2002 (c. 23), ss. 55(2)-(4)(7), 83(1)(a)(3), Sch. 26 para. 51;
Income Tax (Earnings and Pensions) Act 2003 (c. 1), ss. 56, 566(2), 723(1) (with s. 48(2), Sch. 7));
Finance Act 2003 (c. 14), ss. 148(1)-(5), 150, 195;
The Taxation of Benefits under Government Pilot Schemes (Return to Work Credit and Employment Retention and Advancement Schemes) Order 2003 (S.I. 2003/2339), arts. 1, 3;
Finance Act 2004 (c. 12), ss. 51, 188(7), 192(8)(10), 205(7), 206(7), 207(7), 208(8), 215(11), 227(5), 254(7), 255(3), 284(1) (with Sch. 36);
Finance Act 2002 (c. 23),Sch. 26 para. 36(2) (as substituted by Finance Act 2004 (c. 12), s. 52(1)(3), Sch. 10 para. 62);
Income and Corporation Taxes Act 1988 (c. 1), s. 837C (as inserted by Finance Act 2004 (c. 12), Sch. 27 paras. 1, 3);
Income and Corporation Taxes Act 1988 (c. 1), Sch. 19B para. 15(2) (as inserted by Finance Act 2004 (c. 12), Sch. 38);
Energy Act 2004 (c. 20), ss. 27(10), 28(5), 29(6), 30(6), 38(2), 44(5), Sch. 9 para. 37(3); S.I. 2004/2575, art. 2(1), Sch. 1;
Horserace Betting and Olympic Lottery Act 2004 (c. 25), ss. 4(1), 5(3)(c)(4); S.I. 2011/462, art. 2;
The Taxation of Benefits under Government Pilot Schemes (Working Neighbourhoods Pilot and In Work Credit) Order 2004 (S.I. 2004/575), art. 3;
Finance Act 2005 (c. 7), ss. 41(4), 50, 53, 54, 56, 83(1);
Railways Act 2005 (c. 14), Sch. 10 para. 34(2); S.I. 2005/1444, art. 2(1), Sch. 1; S.I. 2005/1909, art, 2, Sch.;
Finance (No. 2) Act 2005 (c. 22), ss. 7(2), 8, 9;
Finance Act 1988 (c.39), s. 66A(2)(4) (as inserted by Finance (No. 2) Act 2005 (c. 22), s. 60(1)(3));
The Pension Protection Fund (Tax) (2005-06) Regulations 2005 (S.I. 2005/1907), reg. 4;
The Friendly Societies (Modification of the Corporation Tax Acts) Regulations 2005 (S.I. 2005/2014), reg. 3;
The Donations to Charity by Individuals (Appropriate Declarations) (Amendment) Regulations 2005 (S.I. 2005/2790), regs. 6, 7;
The Pension Protection Fund (Tax) Regulations 2006 (S.I. 2006/575), reg. 4;
Telecommunications Act 1984 (c. 12), s. 72(3) (as substituted by S.I. 2006/745, art. 2);
The Group Relief for Overseas Losses (Modification of the Corporation Tax Acts for Non-resident Insurance Companies) Regulations 2006 (S.I. 2006/3218), regs. 1(1)(2), 2-12;
The Group Relief for Overseas Losses (Modification of the Corporation Tax Acts for Non-resident Insurance Companies) (No. 2) Regulations 2006 (S.I. 2006/3389), regs. 1(1)(2), 2-10 (as amended by S.I. 2007/2147, regs. 1-6);
Income Tax Act 2007 (c. 3), ss. 414, 466, 467, 473(5)(6), 474, 477, 513(4), 573, 576, 578, 586(2), 597(2), 711(2), 959, 963(4), 970(1), 988-1016 (Pt. 16) (with Sch. 2);
Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 61G (as inserted by Finance Act 2007 (c. 11), s. 25, Sch. 3 para. 4);
Consumers, Estate Agents and Redress Act 2007 (c. 17), Sch. 4 para. 11; S.I. 2007/3546, art. 3, Sch.;
The Corporation Tax (Taxation of Films) (Transitional Provisions) Regulations 2007 (S.I. 2007/1050), regs. 1, 3-12 (as amended by Corporation Tax Act 2009 (c. 4), s. 1329(1), Sch. 2 para. 131 (with Sch. 2 Pts. 1, 2));
The Securitisation Companies (Application of Section 83(1) of the Finance Act 2005: Accounting Standards) Regulations 2007 (S.I. 2007/3338), reg. 3;
The Taxation of Insurance Securitisation Companies Regulations 2007 (S.I. 2007/3402), regs. 1, 6;
Income and Corporation Taxes Act 1988 (c. 1), s. 461D(4) (as inserted by Finance Act 2008 (c. 9), Sch. 18 para. 3);
Income Tax (Trading and Other Income) Act 2005 (c. 5), s. 840A(3) (as inserted by Finance Act 2008 (c. 9), Sch. 7 paras. 69, 81);
Crossrail Act 2008 (c. 18), Sch. 13 para. 3(2)(4);
The Authorised Investment Funds (Tax) Regulations 2006 (S.I. 2006/964), regs. 69Z15(2), 69Z16(2), 69Z17(2) (as inserted by S.I. 2008/705, reg. 5);
The Friendly Societies (Transfers of Other Business) (Modification of the Corporation Tax Acts) Regulations 2008 (S.I. 2008/1942), regs. 1-7;
The Group Relief for Overseas Losses (Modification of the Corporation Tax Acts for Non-resident Insurance Companies) Regulations 2008 (S.I. 2008/2646), regs. 1, 2;
Corporation Tax Act 2009 (c. 4), ss. 2(4), 3, 294(2), 481(2), 490(2), 509(2), 515, 516(1), 521(4)(e)(5), 539(6), 540(3), 545, 550, 592(3), 593(2), 608(7), 799(1)(b), 802(2), 855(7)(8), 969, 1273, 1329 (with Sch. 2);
Income and Corporation Taxes Act 1988 (c. 1), s. 230A (as inserted by Corporation Tax Act 2009 (c. 4), s. 1329(1), Sch. 1 para. 100);
Finance Act 2009 (c. 10), s. 25;
Corporation Tax Act 2009 (c. 4), s. 521B(2) (as inserted by Finance Act 2009 (c. 10), Sch. 24 paras. 4, 12-16);
The Education (Student Loans) (Repayment) Regulations (Northern Ireland) 2009 (S.R. 2009/128), regs. 1(1), 4, 26(2);
The Education (Student Loans) (Repayment) Regulations 2009 (S.I. 2009/470), regs. 1, 4-7, 31(2);
The Authorised Investment Funds (Tax) Regulations 2006 (S.I. 2006/964), reg. 69Z61 (as inserted by S.I. 2009/2036, reg. 24);
The Mutual Societies (Transfers of Business) (Tax) Regulations 2009 (S.I. 2009/2971), regs. 1(1)(2), 4;
The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1, 16(2), 94 (with Sch. 1);
Corporation Tax Act 2010 (c. 4), ss. 128, 620, 624, 625, 778, 784, 786, 876, 950(5), 996(1)(2), 1070, 1071, 1166 (with Sch. 2);
Taxation (International and Other Provisions) Act 2010 (c. 8), s. 79(2), 192, 220 (with ss. 213, 214, Sch. 9 paras. 1-9);
Income Tax Act 2007 (c. 3), s. 809CZB(2) (as inserted by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 5 para. 7 (with Sch. 9 paras. 1-9));
Finance Act 2011 (c. 11), s. 53(5)(7)-(10), Sch. 2 paras. 53(4), 54(6);
The Taxation of Equitable Life (Payments) Order 2011 (S.I. 2011/1502), arts. 1, 3;
Finance Act 2012 (c. 14), ss. 69(b), 71(3), 72, 142(1)(b), 143(1)(b), 144(1), 148, 151, 152, 158(5), 166(5)(6), 167(4) (with Sch. 17);
Corporation Tax Act 2010 (c. 4), ss. 793(8), 812(5A) (as inserted by Finance Act 2012 (c. 14), s. 22(2)-(4));
Taxation (International and Other Provisions) Act 2010 (c. 8), s. 371SO(2) (as inserted by Finance Act 2012 (c. 14), Sch. 20 para. 1);
Small Charitable Donations Act 2012 (c. 23), ss. 15, 21(1);
The Bank Levy (Double Taxation Relief) Regulations 2012 (S.I. 2012/458), regs. 1, 13;
The Bank Levy (Double Taxation Arrangements) (Federal Republic of Germany) Regulations 2012 (S.I. 2012/459), regs. 1(1)(2), 11;
Income Tax Act 2007 (c. 3), Pt. 11ZA (ss. 614ZA-614ZD) (as inserted by Finance Act 2013 (c. 29), Sch. 29 paras. 1, 51);
Corporation Tax Act 2010 (c. 4), Pt. 17A (ss. 814A-814D) (as inserted by Finance Act 2013 (c. 29), Sch. 29 paras. 2, 51);
The Taxation of Regulatory Capital Securities Regulations 2013 (S.I. 2013/3209), regs. 1, 3 (with reg. 8);
Finance Act 2014 (c. 26), s. 223(8)(9)(a);
Corporation Tax Act 2009 (c. 4), s. 490(2) (as substituted by Finance Act 2014 (c. 26), s. 27(3)(7)-(9));
Corporation Tax Act 2010 (c. 4), s. 329N(2) (as inserted by Finance Act 2014 (c. 26), Sch. 14 paras. 1, 4);
Social Security Contributions and Benefits Act 1992 (c. 4), s. 11A(1)(3) (as inserted by National Insurance Contributions Act 2015 (c. 5), Sch. 1 paras. 3, 35);
Social Security Contributions and Benefits (Northern Ireland) Act 1992 (c. 7), s. 11A(1)(3) (as inserted by National Insurance Contributions Act 2015 (c. 5), Sch. 1 paras. 12, 35);
Finance Act 2015 (c. 11), ss. 99(2), 116;
Taxes Management Act 1970 (c. 9), ss. 12ZH, 12ZI, 59AB (as inserted by Finance Act 2015 (c. 11), Sch. 7 paras. 43, 51, 60);
The Education (Postgraduate Master?s Degree Loans) Regulations 2016 (S.I. 2016/606), regs. 1, 67(1);
The Bank Levy (Double Taxation Relief) (Single Resolution Fund Levy) Regulations 2016 (S.I. 2016/1212), regs. 1, 16;
Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 61R (as inserted by Finance Act 2017 (c. 10), Sch. 1 paras. 9, 16);
Finance Act 2012 (c. 14), ss. 124A(6), 124B(7), 124C(7) (as inserted by Finance (No. 2) Act 2017 (c. 32), Sch. 4 paras. 26, 190-192);
Corporation Tax Act 2010 (c. 4), ss. 303B(5), 303C(7), 303D(6), 321(2A) (as inserted by Finance (No. 2) Act 2017 (c. 32), Sch. 4 paras. 48, 52(3), 190-192);
Taxes Management Act 1970 (c. 9), ss. 28A(8), 28B(9) (as inserted by Finance (No. 2) Act 2017 (c. 32), Sch. 15 paras. 12(6), 13(6), 44);
Finance Act 1998 (c. 36), Sch. 18 para. 32(4) (as inserted by Finance (No. 2) Act 2017 (c. 32), Sch. 15 paras. 28(4), 44)
Finance Act 2019 (c. 1), Sch. 3 paras. 7, 9, 12, 13;
Corporation Tax Act 2009 (c. 4), s. 420A(2) (as inserted by Finance Act 2019 (c. 1), Sch. 20 paras. 2, 10(a), 16);
Capital Allowances Act 2001 (c. 2), s. 270HE (as inserted by The Capital Allowances (Structures and Buildings Allowances) Regulations 2019 (S.I. 2019/1087), regs. 1, 2
C2Act (except ss. 201 and 684) amended (1.1.1992) by S.I. 1991/2684, arts. 2, 4,Sch. 1
C3Act: Coal Industry Act 1994 (c. 21), Sch. 4 Pt. 1 to be construed as one with this Act (19.9.1994) by virtue of ss. 21, 68(4) of, and Sch. 4 para. 1(2) to, that Act); S.I. 1999/2189, art. 2, Sch.
C4Act modified (17.9.2004 with effect in accordance with reg. 1 of the modifying S.I.) by The Overseas Life Insurance Companies Regulations 2004 (S.I. 2004/2200), regs. 3, 4
C5Act modified (12.8.2005 with effect in accordance with reg. 1(2) of the modifying S.I.) by The Friendly Societies (Modification of the Corporation Tax Acts) Regulations 2005 (S.I. 2005/2014), reg. 7
C6Act modified (1.4.2006 with effect in accordance with reg. 1(2) of the modifying S.I.) by The Authorised Investment Funds (Tax) Regulations 2006 (S.I. 2006/964), reg. 94 (as amended by S.I. 2008/3159, regs. 1(2)(4), 28)
C7Act modified (31.12.2006 with effect in accordance with reg. 1 of the modifying S.I.) by The Overseas Life Insurance Companies Regulations 2006 (S.I. 2006/3271), regs. 1, 3-18 (as amended by: S.I. 2007/2146, regs. 1, 3-13; S.I. 2007/3449, regs. 1, 3-6; S.I. 2008/1924, regs. 1, 3-12)
C8Act modified (with effect in accordance with Sch. 4 para. 2(2)-(4) of the modifying Act) by Finance Act 2007 (c. 11), Sch. 4 para. 3
C9Act modified (14.8.2007 with effect in accordance with reg. 1(2)(3) of the modifying S.I.) by The Insurance Companies (Tax Exempt Business) Regulations 2007 (S.I. 2007/2145), regs. 3-12
C10Act modified (21.2.2009) by The Banking Act 2009 (Parts 2 and 3 Consequential Amendments) Order 2009 (S.I. 2009/317), art. 3, Sch.
C11Act applied (1.4.2010 with effect in accordance with s. 1184(1) of the affecting Act) by Corporation Tax Act 2010 (c. 4), s. 853
C12Act amended by Finance Act 2010 (c. 13), Sch. 8 para. 8(2)(4)
C13Act amended (2006-07) by Finance (No. 3) Act 2010 (c. 33), Sch. 14 para. 3(5)
C14Act applied (with modifications) (1.10.2010) by The Employment and Support Allowance (Transitional Provisions, Housing Benefit and Council Tax Benefit) (Existing Awards) (No. 2) Regulations 2010 (S.I. 2010/1907), regs. 1(2), 16(2)(c), Sch. 2
C15Act amended by Finance Act 2012 (c. 14), Sch. 15 para. 17(4)(5)
C16 Corporation Tax Acts modified (14.7.2022) by Energy (Oil and Gas) Profits Levy Act 2022 (c. 40), s. 11(1)-(4) (with ss. 15(1), 16(1))
C17Taxes Acts modified (6.4.2024) by 1970 c. 9, s. 8(7) (as inserted by Finance (No. 2) Act 2017 (c. 32), s. 61(6), Sch. 14 para. 3(15); S.I. 2021/1079, reg. 2)
C18Taxes Acts modified (6.4.2024) by 1970 c. 9, s. 8A(7) (as inserted by Finance (No. 2) Act 2017 (c. 32), s. 61(6), Sch. 14 para. 4(12); S.I. 2021/1079, reg. 2)
C19Taxes Acts modified (1.4.2026) by 1970 c. 9, Sch. A1 para. 10(7) (as inserted by Finance (No. 2) Act 2017 (c. 32), s. 60(3)(4); S.I. 2026/356, reg. 2)
PART IU.K. THE CHARGE TO TAX
Income taxU.K.
1 The charge to income tax.U.K.
F1. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1S. 1 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 2, Sch. 3 Pt. 1 (with Sch. 2)
[F21A Application of lower rate to income from savings and distributions.U.K.
F3. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2S. 1A inserted (with effect in accordance with s. 73(3) of the amending Act) by Finance Act 1996 (c. 8), s. 73(1)
F3S. 1A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 2, Sch. 3 Pt. 1 (with Sch. 2)
[F41B Rates of tax applicable to [F5distribution] income etc.U.K.
F6. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F4S. 1B inserted (with effect in accordance with s. 31(6) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 31(5)
F5Words in s. 1B sidenote substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 4(5) (with Sch. 2)
F6S. 1B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 2, Sch. 3 Pt. 1 (with Sch. 2)
2 Fractions of a pound, and yearly assessments.U.K.
F7. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F7S. 2 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 2, Sch. 3 Pt. 1 (with Sch. 2)
3 Certain income charged at basic rate.U.K.
F8. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F8S. 3 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 3, Sch. 3 Pt. 1 (with Sch. 2)
4 Construction of references in Income Tax Acts to deduction of tax.U.K.
F9. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F9S. 4 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 4, Sch. 3 Pt. 1 (with Sch. 2)
5 Date for payment.U.K.
F10. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F10S. 5 repealed (with effect in accordance with s. 199(2) and Sch. 26 Pt. 5(23) Note 2 of the amending Act) by Finance Act 1994 (c. 9), s. 258, Sch. 26 Pt. 5(23); S.I. 1998/3173, art. 2
Corporation taxU.K.
6 The charge to corporation tax and exclusion of income tax and capital gains tax.U.K.
(1)F11. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F11. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F11. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F12. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F13(4A)F14. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
F15(5). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F11S. 6(1)-(3) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 2(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F12S. 6(4) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 2, Sch. 3 Pt. 1 (with Sch. 2)
F13S. 6(4A) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 6 (with Sch. 2)
F14S. 6(4A) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 2(4), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F15S. 6(5) repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 36, Sch. 10 Pt. 12 (with Sch. 9 Pt. 1)
7 Treatment of certain payments and repayment of income tax.U.K.
F16. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F16S. 7 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 3, Sch. 3 Pt. 1 (with Sch. 2)
8 General scheme of corporation tax.U.K.
F17. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F17S. 8 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 3, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F188A Resolutions to reduce corporation tax.U.K.
F19. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F18S. 8A inserted (27.7.1993) by 1993 c. 34, s. 206(2)
F19S. 8A repealed (29.4.1996) by Finance Act 1996 (c. 8), ss. 138, 205, Sch. 24 para. 10, Sch. 41
9 Computation of income: application of income tax principles.U.K.
(1)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F21(2A)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2B)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2C)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(3)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F20. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)Where F22. . . any enactment applies both to income tax and to corporation tax—
(a)it shall not be affected in its operation by the fact that they are distinct taxes but, so far as is consistent with the Corporation Tax Acts, shall apply in relation to income tax and corporation tax as if they were one tax, so that, in particular, a matter which in a case involving two individuals is relevant for both of them in relation to income tax shall in a like case involving an individual and a company be relevant for him in relation to that tax and for it in relation to corporation tax; and
(b)for that purpose references in any such enactment to a relief from or charge to income tax, or to a specified provision of the Income Tax Acts shall, in the absence of or subject to any express adaptation, be construed as being or including a reference to any corresponding relief from or charge to corporation tax, or to any corresponding provision of the Corporation Tax Acts.
(6)F23. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F20S. 9(1)-(4) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 4(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F21S. 9(2A)-(2C) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 7(2) (with Sch. 2)
F22Words in s. 9(5) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 4(3), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F23S. 9(6) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 4(4), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Modifications etc. (not altering text)
C20S. 9 restricted (24.3.2005) by Income Tax (Trading and Other Income) Act 2005 (c. 5), ss. 881, 883(3)(b) (with Sch. 2)
10 Time for payment of tax.U.K.
F24. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F24S. 10 repealed (with effect in accordance with s. 199(2) of the amending Act) by Finance Act 1994 (c. 9), s. 258, Sch. 26 Part 5(23), Note 4; S.I. 1998/3173, art. 2
11 Companies not resident in United Kingdom.U.K.
[F25(1)F26. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F26. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2A)F26. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(3)F27. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F27. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F25S. 11(1)-(2A) substituted for s. 11(1)(2) (with effect in accordance with s. 149(6) of the amending Act) by Finance Act 2003 (c. 14), s. 149(1)
F26S. 11(1)-(2A) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 5, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F27S. 11(3)(4) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 4, Sch. 3 Pt. 1 (with Sch. 2)
[F2811AADetermination of profits attributable to permanent establishmentU.K.
F29. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F28S. 11AA inserted (with effect in accordance with s. 149(6) of the amending Act) by Finance Act 2003 (c. 14), s. 149(2)
F29S. 11AA repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 6, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
12 Basis of, and periods for, assessment.U.K.
(1)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F31(5A)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F32(5B)F33. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(6)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(7)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F34(7ZA)F30. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F35(7A)F36. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
F38. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F39. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F40[F41(7C)F36. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
(8)Where it appears to the inspector that the beginning or end of any accounting period of a company is uncertain, he may make an assessment on the company for such period, not exceeding 12 months, as appears to him appropriate, and that period shall be treated for all purposes as an accounting period of the company unless either—
(a)the inspector on further facts coming to his knowledge sees fit to revise it; or
(b)on an appeal against the assessment in respect of some other matter the company shows the true accounting periods;
and if on an appeal against an assessment made by virtue of this subsection the company shows the true accounting periods, the assessment appealed against shall, as regards the period to which it relates, have effect as an assessment or assessments for the true accounting periods, and there may be made such other assessments for any such periods or any of them as might have been made at the time when the assessment appealed against was made.
[F42(9)F43. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F30S. 12(1)-(7ZA) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 7, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F31S. 12(5A) inserted (with effect as mentioned in Sch. 4 para. 11(4) of the amending Act) by Finance Act 1996 (c. 8), s. 79, Sch. 24 para. 11(3)
F32S. 12(5B) inserted (with effect in accordance with Sch. 41 para. 5(1) of the amending Act) by Finance Act 2003 (c. 14), Sch. 41 para. 1(3)
F33S. 12(1)-(7ZA) repealed (with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 7, Sch. 3 Pt. 1 (with Sch. 2 Pt. 12)
F34S. 12(7ZA) inserted (with effect in accordance with Sch. 41 para. 5(1) of the amending Act) by Finance Act 2003 (c. 14), Sch. 41 para. 1(5)
F35S. 12(7A) inserted by Finance Act 1990 (c. 29), s.48, Sch.9 para.3 (in relation to transfers of business on or after 1.11.1990)
F36S. 12(7A)(7C) omitted (19.2.2008 with effect in accordance with art. 1(2) of the repealing S.I.) by virtue of The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), arts. 1(1), 3
F37S. 12(7B) inserted (with effect in accordance with art. 14(4) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 14(3)
F38S. 12(7B): words and definition of "contracts of long-term insurance" repealed (with effect in accordance with Sch. 10 para. 17(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 10 para. 14(2)(a), Sch. 27 Pt. 2(10), Note
F39S. 12(7B): definition of "insurance business transfer scheme" repealed (with effect in accordance with Sch. 9 para. 17(1) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 9 para. 1(2)(a), Sch. 27 Pt. 2(9), Note
F40S. 12(7C) inserted (with effect in accordance with Sch. 9 para. 20(7) of the amending Act) by Finance (No. 2) Act 2005 (c. 22), Sch. 9 para. 20(3)
F41S. 12(7C) substituted (with effect in accordance with Sch. 9 para. 17(1) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 3(2)
F42S. 12(9) inserted (with effect in accordance with Sch. 10 para. 2 of the amending Act) by Finance Act 2006 (c. 25), Sch. 10 para. 43(2)
F43S. 12(9) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 7, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Small companies’ rateU.K.
13 Small companies’ relief.U.K.
F44. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F44Ss. 13-13A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 5, Sch. 3 Pt. 1 (with Sch. 2)
[F4513ZA Interpretation of section 13(7)U.K.
F46. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F45S. 13ZA inserted (with application in accordance with s. 86(6) of the amending Act) by Finance Act 2001 (c. 9), s. 86(5)
F46Ss. 13-13A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 5, Sch. 3 Pt. 1 (with Sch. 2)
[F4713AA Corporation tax starting rate.U.K.
F48. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F47S. 13AA inserted (with effect in accordance with s. 28(6)(7) of the amending Act) by Finance Act 1999 (c. 16), s. 28(1)
F48S. 13AA repealed (with effect in accordance with s. 26(8)-(11) of the repealing Act) by Finance Act 2006 (c. 25), s. 26(1), Sch. 26 Pt. 3(1), Note
[F4913ABThe non-corporate distribution rateU.K.
F50. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F49S. 13AB inserted (with effect in accordance with s. 28(4)(5) of the amending Act) by Finance Act 2004 (c. 12), s. 28(1)(6)
F50S. 13AB repealed (with effect in accordance with s. 26(8)-(11) of the repealing Act) by Finance Act 2006 (c. 25), s. 26(2), Sch. 26 Pt. 3(1), Note
[F5113A Close investment-holding companies.U.K.
F52. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F51S. 13A inserted (in relation to accounting periods beginning after 31 March 1989) by Finance Act 1989 (c. 26), s. 105(2)(3)
F52Ss. 13-13A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 5, Sch. 3 Pt. 1 (with Sch. 2)
Advance corporation taxU.K.
14 Advance corporation tax and qualifying distributions.U.K.
F53. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F53S. 14 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 6, Sch. 3 Pt. 1 (with Sch. 2)
The six SchedulesU.K.
15 Schedule A.U.K.
F54. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F54S. 15 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 8, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F5516 Schedule B.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F55S. 16 repealed (with effect from 6.4.1988) by Finance Act 1988 (c. 39) s.148, Sch.14 Pt. V
F5617 Schedule C.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F56S. 17 repealed (with effect in accordance with Sch. 7 para. 32 and Sch. 41 Pt. 5(2) Note of the repealing Act) by Finance Act 1996 (c. 8), ss. 79, 205, Sch. 7 para. 3, Sch. 41 Pt. V(2), Note (with Sch. 7 paras. 33-35)
18 Schedule D.U.K.
F57. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F57S. 18 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 9, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
19 Schedule E.U.K.
F58. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F58S. 19 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 723, Sch. 6 para. 6, Sch 8 Pt. 1 (with Sch. 7)
20 Schedule F.U.K.
F59. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F59S. 20 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 10, Sch. 3 (with Sch. 2)
PART IIU.K.[F60PROVISIONS RELATING TO THE SCHEDULE A CHARGE]
Textual Amendments
F60Pt. 2 heading substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 3 (with Sch. 5 para. 73)
GeneralU.K.
[F6121 Persons chargeable and basis of assessment.U.K.
F62. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F61Ss. 21-21B substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) for s. 21 by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 4 (with Sch. 5 paras. 73, 76)
F62S. 21 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 11, Sch. 3 (with Sch. 2)
[F6321A Computation of amount chargeable.U.K.
F64. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F63Ss. 21-21B substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) for s. 21 by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 4 (with Sch. 5 paras. 73, 76)
F64S. 21A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 10, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
21B Application of other rules applicable to Case I of Schedule D.U.K.
F65. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F63Ss. 21-21B substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) for s. 21 by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 4 (with Sch. 5 paras. 73, 76)
F65S. 21B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 11, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F6621C The Schedule A charge and mutual business.U.K.
F67. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F66S. 21C inserted (with effect as mentioned in s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 5 (with Sch. 5 paras. 73, 76)
F67S. 21C repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 12, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
22 Assessments.U.K.
F68. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F68S. 22 repealed (with effect in accordance with s. 39(4)(5) and Sch. 29 Pt. 8(1) Note of the repealing Act) by Finance Act 1995 (c. 4), ss. 39(3), 162, Sch. 6 para. 3, Sch. 29 Pt. 8(1), Note
23 Collection from lessees and agents.U.K.
F69. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F69S. 23 repealed (with effect in accordance with s. 39(4)(5) and Sch. 29 Pt. 8(1) Note of the repealing Act) by Finance Act 1995 (c. 4), ss. 39(3), 162, Sch. 6 para. 3, Sch. 29 Pt. 8(1), Note
24 Construction of Part II.U.K.
F70. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F70S. 24 repealed for the purposes of Corporation Tax (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 7, Sch. 3 Pt. 2 (with Sch. 2)
S. 24 otherwise repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 241, Sch. 10 Pt. 9 (with Sch. 9 paras. 1-9)
Deductions and other allowancesU.K.
25 Deductions from rent: general rules.U.K.
F71. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F71S. 25 ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(a); and s. 25 repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 6, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 68, 73)
26 Deductions from rent: land managed as one estate.U.K.
F72. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F72S. 26 repealed (with effect as mentioned in s. 39 of the repealing Act) by Finance Act 1998 (c. 36), s. 165, Sch. 27 Pt. 3(5), Note
27 Deductions from rent: maintenance funds for historic buildings.U.K.
F73. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F73S. 27 repealed (with effect as mentioned in s. 39 of the repealing Act) by Finance Act 1998 (c. 36), s. 165, Sch. 27 Pt. 3(5), Note
28 Deductions from receipts other than rent.U.K.
F74. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F74S. 28 ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(a); and s. 28 repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 9, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 73)
29 Sporting rights.U.K.
F75. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F75S. 29 ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(b); and s. 29 repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 10, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 73)
30 Expenditure on making sea walls.U.K.
F76. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F76S. 30 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
31 Provisions supplementary to sections 25 to 30.U.K.
F77. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F77S. 31 ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(c); and s. 31 repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 12, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 68, 73)
[F7831ZADeduction for expenditure on energy-saving itemsU.K.
F79. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F78Ss. 31ZA-31ZC inserted (with effect in accordance with s. 17(2) of the amending Act) by Finance Act 2007 (c. 11), s. 17(1); S.I. 2008/1521, art. 2
F79Ss. 31ZA-31ZC repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
31ZBRestrictions on reliefU.K.
F80. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F78Ss. 31ZA-31ZC inserted (with effect in accordance with s. 17(2) of the amending Act) by Finance Act 2007 (c. 11), s. 17(1); S.I. 2008/1521, art. 2
F80Ss. 31ZA-31ZC repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
31ZCRegulationsU.K.
F81. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F78Ss. 31ZA-31ZC inserted (with effect in accordance with s. 17(2) of the amending Act) by Finance Act 2007 (c. 11), s. 17(1); S.I. 2008/1521, art. 2
F81Ss. 31ZA-31ZC repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F8231ADeductions for expenditure by landlords on energy-saving itemsU.K.
F83. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F82Ss. 31A, 31B inserted (with effect in accordance with s. 143(2) of the amending Act) by Finance Act 2004 (c. 12), s. 143(1)
F83S. 31A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 16, Sch. 3 (with Sch. 2)
31BProvisions supplementary to section 31AU.K.
F84. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F82Ss. 31A, 31B inserted (with effect in accordance with s. 143(2) of the amending Act) by Finance Act 2004 (c. 12), s. 143(1)
F84S. 31B repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 16, Sch. 3 (with Sch. 2)
32 Capital allowances for machinery and plant used in estate management.U.K.
F85. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F85S. 32 repealed (with effect as mentioned in Sch. 15 para. 9(1) of the repealing Act) by Finance Act 1997 (c. 16), ss. 85, 113, Sch. 15 para. 1, Sch. 18 Pt. 06(11), Note
33 Agricultural land: allowance for excess expenditure on maintenance.U.K.
F86. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F86S. 33 ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(d); and s. 33 repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 13, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 73)
[F87 Connected personsU.K.
Textual Amendments
F87Ss. 33A, 33B inserted (16.7.1992 with effect in relation to rents or receipts accruing on or after 10.3.1992) by Finance (No. 2) Act 1992 (c. 48), s. 57(1)(2).
F8833A Rents or receipts payable by a connected person.U.K.
F89. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F88S. 33A inserted (16.7.1992 with effect in relation to rents or receipts accruing on or after 10.3.1992) by Finance (No. 2) Act 1992 (c. 48), s. 57(1)(2).
F89S. 33A ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(e); and s. 33A repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 14, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 73)
F9033B Rents or receipts relating to land in respect of which a connected person makes payments to a third party.U.K.
F91. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F90S. 33B inserted (16.7.1992 with effect in relation to rents or receipts accruing on or after 10.3.1992) by Finance (No. 2) Act 1992 (c. 48), s. 57(1)(2).
F91S. 33B ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(e); and s. 33B repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 14, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 73)
Premiums, leases at undervalue etcU.K.
34[F92Treatment of premiums, etc. as rent.]U.K.
F93. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F92S. 34 sidenote substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 15(2), (with Sch. 5 para. 73)
F93Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
35[F94Charge] on assignment of lease granted at an undervalue.U.K.
F95. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F94S. 35: word in sidenote substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 16(2) (with Sch. 5 para. 73)
F95Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
36[F96Charge] on sale of land with right to reconveyance.U.K.
F97. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F96S. 36: word in sidenote substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 17(2) (with Sch. 5 para. 73)
F97Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
37 Premiums paid etc: deductions from premiums and rent received.U.K.
F98. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F98Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
[F9937ASection 37(4) and reductions in receipts under ITTOIA 2005U.K.
F100. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F99S. 37A inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 21 (with Sch. 2)
F100Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
38 Rules for ascertaining duration of leases.U.K.
F101. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F101Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
39 Saving for pre-1963 leases, and special relief for individuals.U.K.
F102. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F102Ss. 34-39 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2 paras. 1-10, 39-41)
[F103 Supplementary provisions]U.K.
Textual Amendments
F103Cross-heading before s. 40 substituted (with effect as mentioned in s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 19, (with Sch. 5 para. 73)
40 Tax treatment of receipts and outgoings on sale of land.U.K.
F104. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F104S. 40 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 17, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
41 Relief for rent etc. not paid.U.K.
F105. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F105S. 41 ceased to have effect except for specified purposes (with effect in accordance with s. 39(4)(5) of the amending Act) by virtue of Finance Act 1995 (c. 4), s. 39(3), Sch. 6 para. 4(g); and s. 41 repealed (with effect as mentioned in s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), ss. 38(1), 165, Sch. 5 para. 21, Sch. 27 Pt. 3(4), Note (with Sch. 5 paras. 65, 73)
42 Appeals against determinations under F106. . . [F107Chapter 4 of Part 3 of ITTOIA 2005].U.K.
F108. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F106S. 42: words in sidenote omitted (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by virtue of Corporation Tax Act 2009 (c. 4), Sch. 1 para. 18(3)
F107S. 42: words in sidenote inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 24(3) (with Sch. 2)
F108S. 42 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 20, Sch. 10 Pt. 12 (with Sch. 9 Pt. 1) (subject to the omission of s. 42(7), so far as it continues to have effect, by virtue of Finance Act 2011 (c. 11), Sch. 23 paras. 55(a), 65)
[F10942A Non-residents and their representatives.U.K.
F110. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F109S. 42A inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 40(1)
F110S. 42A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 7, Sch. 3 Pt. 1 (with Sch. 2)
43 Non-residents.U.K.
F111. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F111S. 43 repealed (with effect in accordance with s. 40(3) of the repealing Act) by Finance Act 1995 (c. 4), s. 40(3), Sch. 29 Pt. 8(16), Note 1
[F112 Rent factoringU.K.
Textual Amendments
F112Ss. 43A-43G and cross-heading inserted (with effect in accordance with s. 110(2) of the amending Act) by Finance Act 2000 (c. 17), s.110(1)
43A Finance agreement: interpretation.U.K.
F113. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F113Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
43B Transfer of rent.U.K.
F114. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F114Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
43C Transfer of rent: exceptions, &c.U.K.
F115. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F115Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
43D Interposed lease.U.K.
F116. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F116Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
43E Interposed lease: exceptions, &c.U.K.
F117. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F117Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
43F Insurance business.U.K.
F118. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F118Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
43G Interpretation.U.K.
F119. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F119Ss. 43A-43G repealed (with effect in accordance with Sch. 6 para. 1(2) of the repealing Act) by Finance Act 2006 (c. 25), Sch. 6 para. 1(1), Sch. 26 Pt. 3(12), Note
PART IIIU.K.[F120GOVERNMENT SECURITIES]
Textual Amendments
F120Pt. 3 heading substituted (with effect in accordance with Sch. 7 para. 32 of the amending Act) by Finance Act 1996, s. 79, Sch. 7 para. 6 (with Sch. 7 paras. 33-35)
GeneralU.K.
44 Income tax: mode of charge.U.K.
F121. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F121S. 44 repealed (with effect in accordance with Sch. 7 para. 32 and Sch. 41 Pt. 5(2) Note of the repealing Act) by Finance Act 1996 (c. 8), ss. 79, 205, Sch. 7 para. 7, Sch. 41 Pt. 5(2) (with Sch. 7 paras. 33-35)
45 Interpretation of Part III.U.K.
F122. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F122S. 45 repealed (with effect in accordance with Sch. 7 para. 32 and Sch. 41 Pt. 5(2) Note of the repealing Act) by Finance Act 1996 (c. 8), ss. 79, 205, Sch. 7 para. 8, Sch. 41 Pt. 5(2) (with Sch. 7 paras. 33-35)
Government securities: exemptions from taxU.K.
46 Savings certificates and tax reserve certificates.U.K.
F123. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F123S. 46 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), s. 1329(1), Sch. 1 para. 19, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
47 United Kingdom government securities held by non-residents.U.K.
F124. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F124S. 47 repealed (with effect in accordance with s. 154(9) of the repealing Act) by Finance Act 1996 (c. 8), ss. 154(7), 205, Sch. 28 para. 1, Sch. 41 Pt. 5(18), Note (with s. 154(2)-(6))
48 Securities of foreign states.U.K.
F125. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F125S. 48 repealed (with effect in accordance with Sch. 7 para. 32 and Sch. 41 Pt. 5(2) Note of the repealing Act) by Finance Act 1996 (c. 8), ss. 79, 205, Sch. 7 para. 9, Sch. 41 Pt. 5(2) (with Sch. 7 paras. 33-35)
49 Stock and dividends in name of Treasury etc.U.K.
[F126(1)No tax shall be chargeable in respect of the stock or dividends—
(a)transferred, in pursuance of any Act of Parliament, to accounts in the books of the Bank of England in the name of the Treasury or the National Debt Commissioners, or
(b)transferred, in pursuance of any Act of Parliament, to the Treasury or the National Debt Commissioners and in respect of which the Treasury or those Commissioners are entered as holder in the registers kept by the Registrar of Government Stock,
but the Bank of England and the Registrar of Government Stock shall each transmit to the Board an account of the total amount thereof in those books or registers as the case may be.]
(2)No tax shall be chargeable in respect of the stock or dividends belonging to the Crown, in whatever name they may stand in the books of the Bank of England [F127or in the registers kept by the Registrar of Government Stock].
[F128(3)In this section “dividends” means any interest, public annuities, dividends or shares of annuities.]
[F129(4)In this section “Registrar of Government Stock” means the person or persons appointed in accordance with regulations under section 47(1)(b) of the Finance Act 1942 (see regulation 3 of the Government Stock Regulations 2004).]
Textual Amendments
F126S. 49(1) substituted (15.11.2004) by The Government Stock (Consequential and Transitional Provision) (No. 3) Order 2004 (S.I. 2004/2744), art. 1, Sch. para. 2(2)(a) (with art. 3)
F127Words in s. 49(2) inserted (15.11.2004) by The Government Stock (Consequential and Transitional Provision) (No. 3) Order 2004 (S.I. 2004/2744), art. 1, Sch. para. 2(2)(b) (with art. 3)
F128S. 49(3) inserted (with effect in accordance with Sch. 7 para. 32 of the amending Act) by Finance Act 1996 (c. 8), s. 79, Sch. 7 para. 10 (with Sch. 7 paras. 33-35)
F129S. 49(4) inserted (15.11.2004) by The Government Stock (Consequential and Transitional Provision) (No. 3) Order 2004 (S.I. 2004/2744), art. 1, Sch. para. 2(2)(c) (with art. 3)
Government securities: interest payable without deduction of taxU.K.
50United Kingdom securities: Treasury directions for payment without deduction of tax.U.K.
F130. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F130S. 50 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 8, Sch. 3 Pt. 1 (with Sch. 2)
51 Treasury directions as respects Northern Ireland securities.U.K.
F131. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F131S. 51 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 8, Sch. 3 Pt. 1 (with Sch. 2)
[F13251AA Commencement of direction under section 50 or 51.U.K.
F133. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F132S. 51AA inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 155
F133S. 51AA repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 8, Sch. 3 Pt. 1 (with Sch. 2)
[F13451A Gilt-edged securities held under authorised arrangements.U.K.
F135. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F134S. 51A inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 77
F135S. 51A repealed (with effect in accordance with s. 37(8) and Sch. 8 Pt. 2(13) Note of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), ss. 37(5), 52, Sch. 8 Pt. 2(13)
[F13651B Periodic accounting for tax on interest on gilt-edged securities.U.K.
F137. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F136S. 51B inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 78(1)
F137S. 51B repealed (with effect in accordance with s. 37(3) of the repealing Act and S.I. 1999/619) by Finance Act 1998 (c. 36), ss. 37(1), 165, Sch. 27 Pt. 3(3), Note
52 Taxation of interest on converted government securities and interest which becomes subject to deduction.U.K.
F138. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F138S. 52 repealed (with effect in accordance with Sch. 7 para. 32 of the repealing Act) by Finance Act 1996 (c. 8), ss. 79, 205, Sch. 7 para. 12, Sch. 41 Pt. 5(2), Note (with Sch. 7 paras. 33-35)
PART IVU.K. PROVISIONS RELATING TO THE SCHEDULE D CHARGE
CHAPTER IU.K. SUPPLEMENTARY CHARGING PROVISIONS
53 Farming and other commercial occupation of land (except woodlands).U.K.
F139. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F139S. 53 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 20, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F14054 Woodlands managed on a commercial basis.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F140S. 54 repealed (15.3.1988) by Finance Act 1988 (c. 39), Sch. 14 Pt. 5, Note 2
55 Mines, quarries and other concerns.U.K.
F141. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F141S. 55 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 21, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
56 Transactions in deposits with and without certificates or in debts.U.K.
(1)M1M2Subsection (2) below applies to the following rights—
(a)the right to receive the amount, with or without interest, stated in a certificate of deposit;
(b)the right to receive an amount payable with interest—
(i)in a transaction in which no certificate of deposit or security is issued, and
(ii)which is payable by a bank or similar institution or a person regularly engaging in similar transactions;
and the right to receive that interest.
(2)M3Profits or gains arising to a [F142company] from the disposal of a right to which this subsection applies or, except so far as it is a right to receive interest, from the exercise of any such right (whether by the person to whom the certificate was issued or by some other person, or, as the case may be, by the person who acquired the right in the transaction referred to in subsection (1) above or by some person acquiring it directly or indirectly from that person), shall, if not falling to be taken into account as a trading receipt, be treated as [F143an amount to which the charge to corporation tax on income applies].
(3)M4Subsection (2) above [F144and section 551 of ITTOIA 2005 (charge to income tax on profits from disposal of deposit rights) do] not apply in the case of the disposal or exercise of a right to receive an amount stated in a certificate of deposit or interest on such an amount—
(a)if the [F145company] disposing of the right acquired it before 7th March 1973;
(b)to any profits or gains arising to a fund or scheme in the case of which provision is made by section [F146613(4) or 614(2) or (3) or section 186 of the Finance Act 2004] for exempting the whole or part of its income from income tax;
(c)F147. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F148(3A)F149. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3B)F149. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3C)F149. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3D)F149. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(4)F150. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F151(4A)This section and section 56A shall not apply for the purposes of corporation tax except in relation to rights in existence before 1st April 1996.
(4B)For the purposes of corporation tax, where any profits or gains arising from the disposal or exercise of a right in existence before 1st April 1996 are, or (if there were any) would be, chargeable under this section, nothing in [F152Part 5 of CTA 2009] (loan relationships) shall require any amount relating to that disposal, or to the exercise of that right, to be brought into account for the purposes of [F152that Part].]
(5)M5 In this section—
“certificate of deposit” means a document relating to money, in any currency, which has been deposited with the issuer or some other person, being a document which recognises an obligation to pay a stated amount to bearer or to order, with or without interest, and being a document by the delivery of which, with or without endorsement, the right to receive that stated amount, with or without interest, is transferable; and
“security” has the same meaning as in section [F153132 of the 1992 Act].
Textual Amendments
F142Word in s. 56(2) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 34(2)(a) (with Sch. 2)
F143Words in s. 56(2) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 22(2) (with Sch. 2 Pts. 1, 2)
F144Words in s. 56(3) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 34(3)(a) (with Sch. 2)
F145Word in s. 56(3)(a) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 34(3)(b) (with Sch. 2)
F146Words in s. 56(3)(b) substituted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 4 (with Sch. 36)
F147S. 56(3)(c) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 8, Sch. 3 Pt. 1 (with Sch. 2)
F148S. 56(3A)-(3D) inserted (27.7.1993) by 1993 c. 34, s. 170, Sch. 18 para.2
F149S. 56(3A)-(3D) repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), s. 141, Sch. 40 Pt. 3(10), Note
F150S. 56(4) omitted (21.7.2008) by virtue of Finance Act 2008 (c. 9), Sch. 17 para. 24(1)
F151S. 56(4A)(4B) inserted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), s. 104, Sch. 14 para. 6 (with Sch. 15)
F152Words in s. 56(4B) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 22(3) (with Sch. 2 Pts. 1, 2)
F153Words in s. 56(5) substituted (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(3) (with ss. 60, 101(1), 171, 201(3)).
Modifications etc. (not altering text)
C21S. 56(2) modified (24.2.2003) by Proceeds of Crime Act 2002 (c. 29), s. 458, Sch. 10 para. 6 (with Sch. 10 para. 10); S.I. 2003/120, art. 2, Sch. (with arts. 3-7 (as amended by S.I. 2003/333, art. 14))
Marginal Citations
M1SOURCE-1973 s. 26(1)
M2SOURCE-1974 s. 30(1)
M3SOURCE-1973 s. 26(1); 1974 s. 30(1)
M4SOURCE-1973 s. 26(1)(a)(b); 1975 (No. 2) s. 50(1)
M5SOURCE-1973 s. 26(4); 1974 s. 30(2), (1); 1968 s. 55(3); 1979(C) Sch. 7
[F15456A Disposal or exercise of rights in pursuance of deposits.U.K.
(1)This section applies where there is an arrangement under which—
(a)there is a right to receive an amount (with or without interest)
in pursuance of a deposit of money,
(b)when the right comes into existence there is no certificate of deposit in respect of the right, and
(c)the person for the time being entitled to the right is entitled to call for the issue of a certificate of deposit in respect of the right.
(2)In such a case—
(a)the right shall be treated as not falling within section 56(1)(b), and
(b)if there is a disposal or exercise of the right before such time (if any) as a certificate of deposit is issued in respect of it, section 56(2) shall apply to it by virtue of this paragraph.
(3)In the application of section 56 by virtue of this section—
(a)subsection (2) shall have effect as if the words from “(whether” to “person)” read “(whether by the person originally entitled to the right or by some other person)”, and
(b)subsection (3) shall have effect as if the words “stated in a certificate of deposit” read “under an arrangement”.
(4)In this section “certificate of deposit” has the meaning given by section 56(5).]
Textual Amendments
F154S. 56A inserted (with application in relation to arrangements made after 16.7.1992) by Finance (No. 2) Act 1992 (c. 48), s. 34, Sch. 8 paras.1, 6.
57 Deep discount securities.U.K.
F155. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F155S. 57 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(3), Note
58 Foreign pensions.U.K.
F156. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F156S. 58 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 8, Sch. 8 Pt. 1 (with Sch. 7)
59 Persons chargeable.U.K.
(1)F157. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F157. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F158. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F158. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F157S. 59(1)(2) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 35(2), Sch. 3 (with Sch. 2)
F158S. 59(3)(4) repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 292, Sch. 10 Pt. 13 (with Sch. 9 Pts. 1, 2)
CHAPTER IIU.K. INCOME TAX: BASIS OF ASSESSMENT ETC.
Cases I and IIU.K.
60 Assessment on current year basis.U.K.
F159. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F159Ss. 60-63A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 36, Sch. 3 (with Sch. 2)
61 Basis of assessment at commencement.U.K.
F160. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F160Ss. 60-63A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 36, Sch. 3 (with Sch. 2)
62 Change of basis period.U.K.
F161. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F161Ss. 60-63A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 36, Sch. 3 (with Sch. 2)
[F16262A Conditions for such a change.U.K.
F163. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F162S. 62A inserted (with effect in accordance with s. 218 of the amending Act) by Finance Act 1994 (c. 9), s. 203 (with Sch. 20)
F163Ss. 60-63A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 36, Sch. 3 (with Sch. 2)
63 Basis of assessment on discontinuance.U.K.
F164. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F164Ss. 60-63A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 36, Sch. 3 (with Sch. 2)
[F16563A Overlap profits and overlap losses.U.K.
F166. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F165S. 63A inserted (with effect in accordance with s. 218 of the amending Act) by Finance Act 1994 (c. 9), s. 205 (with Sch. 20)
F166Ss. 60-63A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 36, Sch. 3 (with Sch. 2)
Cases III, IV and VU.K.
64 Case III assessments.U.K.
F167. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F167S. 64 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 37, Sch. 3 (with Sch. 2)
65 Cases IV and V assessments: general.U.K.
F168. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F168S. 65 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 38, Sch. 3 (with Sch. 2)
[F16965A Case V income from land outside UK: income tax.U.K.
F170. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F169S. 65A inserted (with effect in accordance with s. 41(5)-(10) of the amending Act) by Finance Act 1995 (c. 4), s. 41(2)
F170S. 65A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 39, Sch. 3 (with Sch. 2)
66 Special rules for fresh income.U.K.
F171. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F171S. 66 repealed (with effect in accordance with s. 218(1) of the repealing Act) by Finance Act 1994 (c. 9), ss. 207(4), 258, Sch. 26 Pt. 5(24), Note 7 (with Sch. 20)
67 Special rules where source of income disposed of or yield ceases.U.K.
F172. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F172S. 67 repealed (with effect in accordance with s. 218(1) of the repealing Act) by Finance Act 1994 (c. 9), ss. 207(4), 258, Sch. 26 Pt. 5(24), Note 7 (with Sch. 20)
68 Special rules where property etc. situated in Republic of Ireland.U.K.
F173. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F173S. 68 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 40, Sch. 3 (with Sch. 2)
[F17468AShare incentive plans: application of section 68BU.K.
F175. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F174Ss. 68A-68C inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 10 (with Sch. 7)
F175Ss. 68A-68C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 41, Sch. 3 (with Sch. 2)
68BShare incentive plans: cash dividends and dividend sharesU.K.
F176. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F174Ss. 68A-68C inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 10 (with Sch. 7)
F176Ss. 68A-68C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 41, Sch. 3 (with Sch. 2)
68CShare incentive plans: interpretationU.K.
F177. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F174Ss. 68A-68C inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 10 (with Sch. 7)
F177Ss. 68A-68C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 41, Sch. 3 (with Sch. 2)
Case VIU.K.
69 Case VI assessments.U.K.
F178. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F178S. 69 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 42, Sch. 3 (with Sch. 2)
CHAPTER IIIU.K. CORPORATION TAX: BASIS OF ASSESSMENT ETC
70 Basis of assessment etc.U.K.
F179. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F179S. 70 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 23, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F18070A Case V income from land outside UK: corporation tax.U.K.
F181. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F180S. 70A inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 38(1), Sch. 5 para. 25 (with Sch. 5 para. 73)
F181S. 70A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 24, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
CHAPTER IVU.K. PROVISIONS SUPPLEMENTARY TO CHAPTERS II AND III
71 Computation of income tax where no profits in year of assessment.U.K.
F182. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F182S. 71 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 43, Sch. 3 (with Sch. 2)
72 Apportionments etc. for purposes of Cases I, II and VI.U.K.
F183. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F183S. 72 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 25, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
73 Single assessments for purposes of Cases III, IV and V.U.K.
F184. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F184S. 73 repealed (with effect in accordance with s. 103(7) of the repealing Act) by Finance Act 1995 (c. 4), ss. 115(09), 162, Sch. 29 Pt. 8(14), Note 2
CHAPTER VU.K. COMPUTATIONAL PROVISIONS
DeductionsU.K.
74 General rules as to deductions not allowable.U.K.
F185. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F185S. 74 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 26, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
75Expenses of management: companies with investment businessU.K.
F186. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F186S. 75 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 27, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F18775AAccounting period to which expenses of management are referableU.K.
F188. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F187S. 75A inserted (with effect in accordance with ss. 42, 43 of the amending Act) by Finance Act 2004 (c. 12), s. 39
F188S. 75A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 28, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F18975BAmounts reversing expenses of management deducted: charge to taxU.K.
F190. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F189S. 75B inserted (22.7.2004) by Finance Act 2004 (c. 12), s. 45(1) (with s. 45(2)(3))
F190S. 75B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 29, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
76Expenses of insurance companiesU.K.
F191. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F191S. 76 omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 2 (with Sch. 17)
[F192Payments for restrictive undertakingsU.K.
Textual Amendments
F192S. 76ZA and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 31 (with Sch. 2 Pts. 1, 2)
76ZAPayments for restrictive undertakingsU.K.
F193. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F193S. 76ZA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 3 (with Sch. 17)
[F194Seconded employeesU.K.
Textual Amendments
F194S. 76ZB and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 32 (with Sch. 2 Pts. 1, 2)
76ZBEmployees seconded to charities and educational establishmentsU.K.
F195. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F195S. 76ZB omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 4 (with Sch. 17)
[F196Counselling and retraining expensesU.K.
Textual Amendments
F196S. 76ZC and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 33 (with Sch. 2 Pts. 1, 2)
76ZCCounselling and other outplacement servicesU.K.
F197. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F197Ss. 76ZC-76ZE omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 5 (with Sch. 17)
[F19876ZDRetraining coursesU.K.
F199. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F198S. 76ZD inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 34 (with Sch. 2 Pts. 1, 2)
F199Ss. 76ZC-76ZE omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 5 (with Sch. 17)
[F20076ZERetraining courses: recovery of taxU.K.
F201. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F200S. 76ZE inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 35 (with Sch. 2 Pts. 1, 2)
F201Ss. 76ZC-76ZE omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 5 (with Sch. 17)
[F202Redundancy payments etcU.K.
Textual Amendments
F202S. 76ZF and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 36 (with Sch. 2 Pts. 1, 2)
76ZFRedundancy payments and approved contractual paymentsU.K.
F203. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F203Ss. 76ZF-76ZJ omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 6 (with Sch. 17)
[F20476ZGPayments in respect of employment wholly in employer's businessU.K.
F205. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F204S. 76ZG inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 37 (with Sch. 2 Pts. 1, 2)
F205Ss. 76ZF-76ZJ omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 6 (with Sch. 17)
[F20676ZHPayments in respect of employment in more than one capacityU.K.
F207. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F206S. 76ZH inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 38 (with Sch. 2 Pts. 1, 2)
F207Ss. 76ZF-76ZJ omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 6 (with Sch. 17)
[F20876ZIAdditional paymentsU.K.
F209. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F208S. 76ZI inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 39 (with Sch. 2 Pts. 1, 2)
F209Ss. 76ZF-76ZJ omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 6 (with Sch. 17)
[F21076ZJPayments by the GovernmentU.K.
F211. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F210S. 76ZJ inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 40 (with Sch. 2 Pts. 1, 2)
F211Ss. 76ZF-76ZJ omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 6 (with Sch. 17)
[F212Contributions to local enterprise organisations or urban regeneration companiesU.K.
Textual Amendments
F212S. 76ZK and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 41 (with Sch. 2 Pts. 1, 2)
76ZKContributions to local enterprise organisations or urban regeneration companiesU.K.
F213. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F213S. 76ZK omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 7 (with Sch. 17)
[F214Unpaid remunerationU.K.
Textual Amendments
F214S. 76ZL and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 42 (with Sch. 2 Pts. 1, 2)
76ZLUnpaid remunerationU.K.
F215. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F215Ss. 76ZL, 76ZM omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 8 (with Sch. 17)
[F21676ZMUnpaid remuneration: supplementaryU.K.
F217. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F216S. 76ZM inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 43 (with Sch. 2 Pts. 1, 2)
F217Ss. 76ZL, 76ZM omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 8 (with Sch. 17)
[F218Car or motor cycle hire]U.K.
Textual Amendments
F218S. 76ZN and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 44 (with Sch. 2 Pts. 1, 2)
[F21976ZNCar or motor cycle hireU.K.
F220. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F219S. 76ZN and cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 44 (with Sch. 2 Pts. 1, 2)
F220S. 76ZN omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 9 (with Sch. 17)
[F22176ZOHiring cars (but not motor cycles) with low CO2 emissions before 1 April 2013U.K.
F222. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F221S. 76ZO inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 45 (with Sch. 2 Pts. 1, 2)
F222S. 76ZO omitted (with effect in accordance with Sch. 11 paras. 65-67 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 11 para. 61
[F22376A Levies and repayments under the Financial Services and Markets Act 2000.U.K.
F224. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F223Ss. 76A, 76B inserted (1.12.2001) by Financial Services and Markets Act 2000 (c. 8), ss. 411(2), 431(2); S.I. 2001/3538, art. 2(1)
F224S. 76A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 46, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F22576B Levies and repayments under the Financial Services and Markets Act 2000: investment companies.U.K.
F226. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F225Ss. 76A, 76B inserted (1.12.2001) by Financial Services and Markets Act 2000 (c. 8), ss. 411(2), 431(2); S.I. 2001/3538, art. 2(1)
F226S. 76B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 47, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
77 Incidental costs of obtaining loan finance.U.K.
F227. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F227S. 77 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 47, Sch. 3 (with Sch. 2)
78 Discounted bills of exchange.U.K.
F228. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F228S. 78 repealed with saving (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 14 para. 10, Sch. 41 Pt. 5(3), Note (with Sch. 15)
79 Contributions to local enterprise agencies.U.K.
F229. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F229S. 79 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 48, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F23079A Contributions to training and enterprise councils and local enterprise companies.U.K.
F231. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F230S. 79A inserted by Finance Act 1990 (c. 29), s.76
F231S. 79A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 49, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F23279BContributions to urban regeneration companiesU.K.
F233. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F232S. 79B inserted (10.7.2003) by Finance Act 2003 (c. 14), s. 180(1)
F233S. 79B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 50, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
80 Expenses connected with foreign trades etc.U.K.
F234. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F234S. 80 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 51, Sch. 3 (with Sch. 2)
81 Travel between trades etc.U.K.
F235. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F235S. 81 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 52, Sch. 3 (with Sch. 2)
82 Interest paid to non-residents.U.K.
F236. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F236S. 82 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 53, Sch. 3 (with Sch. 2)
[F23782A Expenditure on research and development.U.K.
F238. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F237Ss. 82A, 82B inserted (with effect in accordance with s. 68(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 19 para. 5(1) (with Sch. 19 para. 5(2)(3))
F238S. 82A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 51, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F23982B Payments to research associations, universities etc.U.K.
F240. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F239Ss. 82A, 82B inserted (with effect in accordance with s. 68(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 19 para. 5(1) (with Sch. 19 para. 5(2)(3))
F240S. 82B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 52, Sch. 3 Pt. 1 (with Sch. 2 Pt. 12)
83 Patent fees etc. and expenses.U.K.
F241. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F241S. 83 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 53, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F24283A Gifts in kind to charities etc.U.K.
F243. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F242S. 83A inserted (with effect in accordance with s. 55(3) of the amending Act) by Finance Act 1999 (c. 16), s. 55(1)
F243S. 83A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 54, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
84 Gifts to educational establishments.U.K.
F244. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F244S. 84 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 55, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F24584A Costs of establishing share option or profit sharing schemes: relief.U.K.
F246. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F245S. 84A inserted by Finance Act 1991 (c. 31), s. 42
F246S. 84A repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 26, Sch. 10 Pt. 12 (with Sch. 9)
85 Payments to trustees of approved profit sharing schemes.U.K.
F247. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F247S. 85 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 57, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F24885A Costs of establishing employee share ownership trusts: relief.U.K.
F249. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F248S. 85A inserted by Finance Act 1991 (c. 31), s. 43
F249S. 85A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 58, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F25085BApproved share incentive plansU.K.
F251. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F250S. 85B inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 12 (with Sch. 7)
F251S. 85B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 59, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
86 Employees seconded to charities and educational establishments.U.K.
F252. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F252S. 86 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 60, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F25386A Charitable donations: contributions to agent’s expenses.U.K.
F254. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F253S. 86A inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 69
F254S. 86A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 61, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
87 Taxable premiums etc.U.K.
F255. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F255S. 87 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 62, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F25687ASection 87(2) and (3) and reductions in receipts under ITTOIA 2005U.K.
F257. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F256S. 87A inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 63 (with Sch. 2)
F257S. 87A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 62, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
88 Payments to Export Credit Guarantee Department.U.K.
F258. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F258S. 88 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 63, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F25988A Debts of overseas governments etc.U.K.
F260. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F259Ss. 88A-88C inserted by Finance Act 1990 (c. 29), s. 74
F260Ss. 88A-88C repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(3), Note (with Sch. 15)
[F26188B Section 88A debts: restriction on deductions under section 74(j).U.K.
F262. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F261Ss. 88A-88C inserted by Finance Act 1990 (c. 29), s. 74
F262Ss. 88A-88C repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(3), Note (with Sch. 15)
[F26388C Section 88A debts: restriction on other deductions.U.K.
F264. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F263Ss. 88A-88C inserted by Finance Act 1990 (c. 29), s. 74
F264Ss. 88A-88C repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(3), Note (with Sch. 15)
[F26588DRestriction of deductions in respect of certain debtsU.K.
F266. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F265S. 88D inserted (with effect in accordance with s. 80(3)(4) of the amending Act) by Finance Act 2005 (c. 7), Sch. 4 para. 2
F266S. 88D repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 64, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
89Debts proving to be irrecoverable after discontinuance etcU.K.
F267. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F267S. 89 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 65, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
90 Additional payments to redundant employees.U.K.
F268. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F268S. 90 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 66, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
91 Cemeteries.U.K.
F269. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F269S. 91 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 67, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F27091A Waste disposal: restoration payments.U.K.
F271. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F270Ss. 91A, 91B inserted by Finance Act 1990 (c. 29), s. 78
F271S. 91A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 68, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F27291B Waste disposal: preparation expenditure.U.K.
F273. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F272Ss. 91A, 91B inserted by Finance Act 1990 (c. 29), s. 78
F273S. 91B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 69, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F27491BA Waste disposal: entitlement of successor to allowances.U.K.
F275. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F274S. 91BA inserted (28.7.2000) by Finance Act 2000 (c. 17), s. 89
F275S. 91BA repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 69, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F27691C Mineral exploration and access.U.K.
F277. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F276S. 91C inserted (with application in accordance with s. 66(3)(4) of the amending Act) by Finance Act 1997 (c. 16), s. 66(1)
F277S. 91C repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Treatment of regional development and other grants and debts released etc.U.K.
92 Regional development grants.U.K.
F278. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F278S. 92 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 71, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
93 Other grants under Industrial Development Act 1982 etc.U.K.
F279. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F279S. 93 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 72, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
94 Debts deducted and subsequently released.U.K.
F280. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F280S. 94 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
95[F281Taxation of dealers in respect of distributions etc.]U.K.
F282. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F281S. 95 sidenote substituted (with effect in accordance with s. 24(15) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 24(9)
F282S. 95 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 74, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F28395ZATaxation of UK distributions received by insurance companiesU.K.
(1)If the total amount of relevant distributions received by a company in an accounting period exceeds £50,000, those distributions are to be taken into account in calculating for corporation tax purposes the profits of the company in that period (and accordingly [F284[F285section 130(2)] of CTA 2009] does not apply in relation to those distributions).
(2)A company (“company A”) receives a “relevant distribution” if—
(a)it receives a distribution made by a company F286. . . (“company B”),
(b)the value of the shares or stock in respect of which the distribution is made (“the holding”) is materially reduced by reason of the distribution,
(c)a profit on the sale of the holding (to anyone other than company B) would be taken into account in calculating company A's profits in respect of relevant insurance business, and
(d)either—
(i)the holding amounts to, or is an ingredient in a holding amounting to, 10% of all holdings of the same class in company B, or
(ii)the period between the acquisition by company A of the holding and that company first taking steps to dispose of the holding does not exceed 30 days.
(3)In this section “relevant insurance business” means any kind of insurance business other than [F287business in relation to which section 111 of the Finance Act 2012 applies].
(4)Section 177(7) of TCGA 1992 (provision supplementing provision corresponding to subsection (2)(d)(i) above) applies for the purposes of subsection (2)(d)(i).
(5)Section 731(4) below (interpretation of “taking steps to dispose of securities”) applies for the purposes of subsection (2)(d)(ii) as if the reference to the securities were to the holding.]
Textual Amendments
F283S. 95ZA inserted (with effect in accordance with Sch. 17 para. 16(2) of the amending Act) by Finance Act 2008 (c. 9), Sch. 17 para. 16(1)
F284Words in s. 95ZA(1) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 75 (with Sch. 2 Pts. 1, 2)
F285Words in s. 95ZA(1) substituted (with effect in accordance with Sch. 14 para. 31 of the amending Act) by Finance Act 2009 (c. 10), Sch. 14 para. 5(2)
F286Words in s. 95ZA(2)(a) omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 5(3)
F287Words in s. 95ZA(3) substituted (with effect in accordance with s. 148(1) of the amending Act) by Finance Act 2012 (c. 14), Sch. 16 para. 10 (with Sch. 17)
Special provisionsU.K.
[F28895A Creative artists: relief for fluctuating profitsU.K.
F289. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F288S. 95A inserted (11.5.2001) by Finance Act 2001 (c. 9), s. 71(1)
F289S. 95A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 75, Sch. 3 (with Sch. 2)
96 Farming and market gardening: relief for fluctuating profits.U.K.
F290. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F290S. 96 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 76, Sch. 3 (with Sch. 2)
97 Treatment of farm animals etc.U.K.
F291. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F291S. 97 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 76, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F29298 Tied premises: receipts and expenses treated as those of trade.U.K.
F293. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F292S. 98 substituted (17.3.1998) by Finance Act 1998 (c. 36), s. 41(1)(3) (with s. 41(4)-(7))
F293S. 98 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 77, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
99 Dealers in land.U.K.
F294. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F294S. 99 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 78, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
CHAPTER VIU.K. DISCONTINUANCE F295. . .
Textual Amendments
F295Words in Pt. 4 Ch. 6 heading repealed (with application in accordance with Sch. 27 Pt. 3(6) Note of the repealing Act) by Finance Act 1998 (c. 36), Sch. 27 Pt. 3(6)
Valuation of trading stock etc.U.K.
100 Valuation of trading stock at discontinuance of trade.U.K.
F296. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F296S. 100 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 79, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
101 Valuation of work in progress at discontinuance of profession or vocation.U.K.
F297. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F297S. 101 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 80, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
102 Provisions supplementary to sections 100 and 101.U.K.
F298. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F298S. 102 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 81, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Case VI charges on receiptsU.K.
103 Receipts after discontinuance: earnings basis charge and related charge affecting conventional basis.U.K.
F299. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F299Ss. 103-106 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 82, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
104 Conventional basis: general charge on receipts after discontinuance F300. . . .U.K.
F301. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F300Words in s. 104 sidenote repealed (with effect in accordance with Sch. 27 Pt. 3(6) Note of the repealing act) by Finance Act 1998 (c. 36), Sch. 27 Pt. 3(6)
F301Ss. 103-106 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 82, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
105 Allowable deductions.U.K.
F302. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F302Ss. 103-106 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 82, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
106 Application of charges where rights to payments transferred.U.K.
F303. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F303Ss. 103-106 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 82, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
ReliefsU.K.
107 Treatment of receipts as earned income.U.K.
F304. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F304S. 107 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 86, Sch. 3 (with Sch. 2)
108 Election for carry-back.U.K.
F305. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F305S. 108 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 87, Sch. 3 (with Sch. 2)
109 Charge under section 104: relief for individuals born before 6th April 1917.U.K.
F306. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F306S. 109 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 88, Sch. 3 (with Sch. 2)
[F307 Relief for post-cessation expenditureU.K.
Textual Amendments
F307S. 109A and preceding cross-heading inserted (with effect in accordance with s. 90(7) of the amending Act) by Finance Act 1995 (c. 4), s. 90(1)
109A Relief for post-cessation expenditure.U.K.
F308. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F308S. 109A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 11, Sch. 3 Pt. 1 (with Sch. 2)
SupplementalU.K.
110 Interpretation etc.U.K.
F309. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F309S. 110 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 83, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F310[F311 Change of residence]U.K.
Textual Amendments
F310S. 110A and preceding cross-heading inserted (with effect in accordance with s. 124(2) of the amending Act) by Finance Act 1995 (c. 4), s. 124(1)
F311S. 110A and preceding cross-heading repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 91, Sch. 3 (with Sch. 2)
110A Change of residence.U.K.
F312. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F312S. 110A and preceding cross-heading repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 91, Sch. 3 (with Sch. 2)
CHAPTER VIIU.K. PARTNERSHIPS AND SUCCESSIONS
GeneralU.K.
[F313111 Treatment of partnerships.U.K.
(1)F314. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(7)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(8)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(9)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(10)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(11)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(12)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(13)F315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F313S. 111 substituted (with effect in accordance with s. 215(4)(5) of the 1994 amending Act) by Finance Act 1994 (c. 9), s. 215(1) (as amended (retrospectively) by Finance Act 1995 c. 4, s. 117(1)(a)(2)(4)) (with Sch. 20)
F314S. 111(1) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 84, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F315S. 111(2)-(13) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 92(3), Sch. 3 (with Sch. 2)
112 Partnerships controlled abroad.U.K.
F316. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F316S. 112 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 93, Sch. 3 (with Sch. 2)
113 Effect, for income tax, of change in ownership of trade, profession or vocation.U.K.
F317. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F317S. 113 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 94, Sch. 3 (with Sch. 2)
Partnerships involving companiesU.K.
114 Special rules for computing profits and losses.U.K.
F318. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F318S. 114 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 85, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
115 Provisions supplementary to section 114.U.K.
F319. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F319S. 115 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 85, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
116 Arrangements for transferring relief.U.K.
F320. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F320S. 116 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 11, Sch. 3 Pt. 1 (with Sch. 2)
Limited partnersU.K.
117 Restriction on relief: individuals.U.K.
F321. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F321S. 117 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 13, Sch. 3 Pt. 1 (with Sch. 2)
118 Restriction on relief: companies.U.K.
F322. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F322Ss. 118-118ZD repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 12, Sch. 3 Pt. 1 (with Sch. 2)
[F323Limited liability partnershipsU.K.
Textual Amendments
F323Ss. 118ZA-118ZD and preceding cross-heading inserted (6.4.2001) by Limited Liability Partnerships Act 2000 (c. 12), ss. 10(1), 19(1); S.I. 2000/3316, art. 2
118ZA Treatment of limited liability partnerships.U.K.
F324. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F324S. 118ZA repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 87, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
118ZBRestriction on relief: companiesU.K.
F325. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F325Ss. 118-118ZD repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 12, Sch. 3 Pt. 1 (with Sch. 2)
118ZC Member’s contribution to trade.U.K.
F326. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F326Ss. 118-118ZD repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 12, Sch. 3 Pt. 1 (with Sch. 2)
118ZD Carry forward of unrelieved losses.U.K.
F327. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F327Ss. 118-118ZD repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 12, Sch. 3 Pt. 1 (with Sch. 2)
[F328Non-active general partners and non-active members of limited liability partnershipsU.K.
Textual Amendments
F328Ss. 118ZE-118ZK and preceding cross-heading inserted (22.7.2004) by Finance Act 2004 (c. 12), s. 124(1)
118ZERestriction on relief for non-active partnersU.K.
F329. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F329Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
118ZFMeaning of “the aggregate amount”U.K.
F330. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F330Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
118ZG“The individual’s contribution to the trade”U.K.
F331. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F331Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
118ZH“A significant amount of time”U.K.
F332. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F332Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
118ZICarry forward of unrelieved losses of non-active partnersU.K.
F333. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F333Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
18ZJCommencement: the first restricted yearU.K.
F334. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F334Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
118ZKTransitional provision for years after the first restricted yearU.K.
F335. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F335Ss. 118ZE-118ZK repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
[F336Partnerships exploiting filmsU.K.
Textual Amendments
F336Ss. 118ZL, 118ZM and preceding cross-heading inserted (22.7.2004) by Finance Act 2004 (c. 12), s. 125
118ZLPartnerships exploiting filmsU.K.
F337. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F337Ss. 118ZL, 118ZM repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 19, Sch. 3 Pt. 1 (with Sch. 2)
118ZMPartnerships exploiting films: supplementaryU.K.
F338. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F338Ss. 118ZL, 118ZM repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 19, Sch. 3 Pt. 1 (with Sch. 2)
[F339Partners: meaning of “contribution to the trade”U.K.
Textual Amendments
F339Ss. 118ZN, 118ZO and preceding cross-heading inserted (retrospective to 2.12.2004) by Finance Act 2005 (c. 7), s. 73(1)(5)
118ZNPartners: meaning of “contribution to the trade”U.K.
F340. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F340Ss. 118ZN, 118ZO repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 20, Sch. 3 Pt. 1 (with Sch. 2)
118ZOMeaning of “relevant loss” in section 118ZNU.K.
F341. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F341Ss. 118ZN, 118ZO repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 20, Sch. 3 Pt. 1 (with Sch. 2)
[F342[F343Chapter VIIAU.K. Paying and collecting agents]
Textual Amendments
F342Pt. 4 Ch. 7A (ss. 118A-118K) inserted (29.4.1996) by Finance Act 1996 (c. 8), Sch. 29 para. 1
F343Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118A Definitions.U.K.
F344. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F344Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118B Paying agents.U.K.
F345. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F345Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118C Collecting agents.U.K.
F346. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F346Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118D Chargeable payments and chargeable receipts.U.K.
F347. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F347Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118E Deduction of tax from chargeable payments and chargeable receipts.U.K.
F348. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F348Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118F Accounting for tax on chargeable payments and chargeable receipts.U.K.
F349. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F349Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118G Relevant securities of eligible persons.U.K.
F350. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F350Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118H Relevant securities of eligible persons: administration.U.K.
F351. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F351Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118I Deduction of tax at reduced rate.U.K.
F352. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F352Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118J Prevention of double accounting.U.K.
F353. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F353Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
118K Regulations.U.K.
F354. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F354Pt. 4 Ch. 7A (ss. 118A-118K) repealed (with effect in accordance with s. 111(6)(a) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(1), Sch. 40 Pt. 2(17), Note 1
CHAPTER VIIIU.K. MISCELLANEOUS AND SUPPLEMENTAL
119 Rent etc. payable in connection with mines, quarries and similar concerns.U.K.
F355. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F355S. 119 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
120 Rent etc. payable in respect of electric line wayleaves.U.K.
F356. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F356S. 120 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 89, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
121 Management expenses of owner of mineral rights.U.K.
F357. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F357S. 121 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 90, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
122 Relief in respect of mineral royalties.U.K.
F358. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F358S. 122 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 91, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
123 Foreign dividends.U.K.
F359. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F359S. 123 repealed (with effect in accordance with Sch. 7 para. 32 of the repealing Act) by Finance Act 1996 (c. 8), Sch. 7 para. 13, Sch. 41 Pt. 5(2), Note (with Sch. 7 paras. 33-35)
124 Interest on quoted Eurobonds.U.K.
F360. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F360S. 124 repealed (with effect in accordance with s. 111(6)(b) of the repealing Act) by Finance Act 2000 (c. 17), s. 111(2), Sch. 40 Pt. 2(17), Note 2
125[F361Annual payments for dividends or non-taxable consideration]U.K.
F362. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F361S. 125 title substituted (retrospective to 2.12.2004) by virtue of Finance Act 2005 (c. 7), s. 91(3)
F362S. 125 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 92, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
126 Treasury securities issued at a discount.U.K.
F363. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
126A Charge to tax on appropriation of securities and bonds.U.K.
F364. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
127 Enterprise allowance.U.K.
F365. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F365S. 127 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 108, Sch. 3 (with Sch. 2)
[F366127A Futures and options: transactions with guaranteed returns.U.K.
F367. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F366S. 127A inserted (with effect in accordance with s. 80(6) of the amending Act) by Finance Act 1997 (c. 16), s. 80(1)
F367S. 127A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 109, Sch. 3 (with Sch. 2)
128 Commodity and financial futures etc.: losses and gains.U.K.
(1)F368. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F369(2)F370. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(3)F370. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F368S. 128(1) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 110, Sch. 3 (with Sch. 2)
F369S. 128(2) inserted (with effect in accordance with s. 83(3) of the amending Act) by Finance Act 2002 (c. 23), Sch. 27 para. 3(2) (with Sch. 28)
F370S. 128(2)(3) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 93, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
129 Stock lending.U.K.
F371. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F371Ss. 129, 129A repealed (with effect in accordance with Sch. 10 para. 7(1) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 10 para. 1, Sch. 18 Pt. 6(10), Note 1; S.I. 1997/991, art. 2
[F372129A Stock lending: interest on cash collateral.U.K.
F373. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F372S. 129A inserted (with application in accordance with s. 85(3) of the amending Act) by Finance Act 1995 (c. 4), s. 85(1)
F373Ss. 129, 129A repealed (with effect in accordance with Sch. 10 para. 7(1) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 10 para. 1, Sch. 18 Pt. 6(10), Note 1; S.I. 1997/991, art. 2
[F374129B Stock lending fees.U.K.
(1)The income which, as income deriving from investments of a description specified in any of the relevant provisions, is eligible for relief from tax by virtue of that provision shall be taken to include any relevant stock lending fee.
(2)For the purposes of this section the relevant provisions are [F375sections 613(4) and 614(3) and section 186 of the Finance Act 2004].
(3)In this section “relevant stock lending fee”, in relation to investments of any description, means any amount, in the nature of a fee, which is payable in connection with [F376any] stock lending arrangement relating to investments which, but for any transfer under the arrangement, would be investments of that description.
[F377(4)In this section “stock lending arrangement” has the same meaning as in section 263B of the 1992 Act.]]
Textual Amendments
F374S. 129B inserted (with effect in accordance with s. 157(2) of the amending Act) by Finance Act 1996 (c. 8), s. 157(1)
F375Words in s. 129B(2) substituted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 6 (with Sch. 36)
F376Word in s. 129B(3) substituted (with effect in accordance with Sch. 10 para. 7(1) of the amending Act) by Finance Act 1997 (c. 16), Sch. 10 para. 2(1); S.I. 1997/991, art. 2
F377S. 129B(4) substituted (with effect in accordance with Sch. 10 para. 7(1) of the amending Act) by Finance Act 1997 (c. 16), Sch. 10 para. 2(2); S.I. 1997/991, art. 2
130[F378Meaning of “investment company” in Part 4]U.K.
M6In this Part of this Act [F379—
F380. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
“investment company”, means any company whose business consists wholly or mainly in the making of investments and the principal part of whose income is derived therefrom, but includes any savings bank or other bank for savings except any which, for the purposes of the M7Trustee Savings Bank Act 1985, is a successor or a further successor to a trustee savings bank.
Textual Amendments
F378S. 130 title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 94(3) (with Sch. 2 Pts. 1, 2)
F379S. 130: definition of "company with investment business" inserted (with effect in accordance with ss. 38(5), 42, 43 of the amending Act) by Finance Act 2004 (c. 12), s. 38(3)
F380S. 130: definition of "company with investment business" repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 94(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Marginal Citations
M6Source—1970 s.304(5); 1980 Sch.11
PART VU.K. PROVISIONS RELATING TO THE SCHEDULE E CHARGE
CHAPTER IU.K. SUPPLEMENTARY CHARGING PROVISIONS OF GENERAL APPLICATION
Miscellaneous provisionsU.K.
131 Chargeable emoluments.U.K.
F381. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F381Ss. 131-134 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 14, Sch. 8 Pt. 1 (with Sch. 7)
132 Place of performance, and meaning of emoluments received in the U.K.U.K.
F382. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F382Ss. 131-134 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 14, Sch. 8 Pt. 1 (with Sch. 7)
133 Voluntary pensions.U.K.
F383. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F383Ss. 131-134 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 14, Sch. 8 Pt. 1 (with Sch. 7)
134 Workers supplied by agencies.U.K.
F384. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F384Ss. 131-134 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 14, Sch. 8 Pt. 1 (with Sch. 7)
Shareholdings, loans etc.U.K.
135 Gains by directors and employees from share options.U.K.
F385. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F385Ss. 135-137 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 15, Sch. 8 Pt. 1 (with Sch. 7)
136 Provisions supplementary to section 135.U.K.
F386. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F386Ss. 135-137 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 15, Sch. 8 Pt. 1 (with Sch. 7)
137 Payment of tax under section 135 by instalments.U.K.
F387. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F387Ss. 135-137 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 15, Sch. 8 Pt. 1 (with Sch. 7)
138 Share acquisitions by directors and employees.U.K.
F388. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F388Ss. 138, 139 omitted (with effect in accordance with s. 50(3) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 50(1)
F389139 Provisions supplementary to section 138.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F389Ss. 138, 139 omitted (with effect in accordance with s. 50(3) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 50(1)
140 Further interpretation of sections 135 to 139.U.K.
F390. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F390S. 140 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 17, Sch. 8 Pt. 1 (with s. 418(4), Sch. 7)
[F391140A Conditional acquisition of shares.U.K.
F392. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F391Ss. 140A-140C inserted (with application in accordance with s. 50(4) of the amending Act) by Finance Act 1998 (c. 36), s. 50(1)
F392Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
140B Consideration for shares conditionally acquired.U.K.
F393. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F391Ss. 140A-140C inserted (with application in accordance with s. 50(4) of the amending Act) by Finance Act 1998 (c. 36), s. 50(1)
F393Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
140C Cases where interest to be treated as only conditional.U.K.
F394. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F391Ss. 140A-140C inserted (with application in accordance with s. 50(4) of the amending Act) by Finance Act 1998 (c. 36), s. 50(1)
F394Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
[F395140D Convertible shares.U.K.
F396. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F395Ss. 140D-140F inserted (with application in accordance with s. 51(3) of the amending Act) by Finance Act 1998 (c. 36), s. 51(1)
F396Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
140E Consideration for convertible shares.U.K.
F397. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F395Ss. 140D-140F inserted (with application in accordance with s. 51(3) of the amending Act) by Finance Act 1998 (c. 36), s. 51(1)
F397Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
140F Supplemental provision with respect to convertible shares.U.K.
F398. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F395Ss. 140D-140F inserted (with application in accordance with s. 51(3) of the amending Act) by Finance Act 1998 (c. 36), s. 51(1)
F398Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
[F399140G Information for the purposes of sections 140A to 140F.U.K.
F400. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F399S. 140G inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 52(1)
F400Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
[F401140H Construction of sections 140A to 140G.U.K.
F402. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F401S. 140H inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 53
F402Ss. 140A-140H repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 18, Sch. 8 Pt. 1 (with Sch. 7)
Vouchers etc.U.K.
141 Non-cash vouchers.U.K.
F403. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F403Ss. 141-144 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 19, Sch. 8 Pt. 1 (with Sch. 7)
142 Credit-tokens.U.K.
F404. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F404Ss. 141-144 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 19, Sch. 8 Pt. 1 (with Sch. 7)
143 Cash vouchers taxable under P.A.Y.E.U.K.
F405. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F405Ss. 141-144 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 19, Sch. 8 Pt. 1 (with Sch. 7)
144 Supplementary provisions.U.K.
F406. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F406Ss. 141-144 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 19, Sch. 8 Pt. 1 (with Sch. 7)
[F407144A Payments etc. received free of tax.U.K.
F408. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F407S. 144A inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 132
F408S. 144A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 20, Sch. 8 Pt. 1 (with Sch. 7)
Living accommodationU.K.
145 Living accommodation provided for employee.U.K.
F409. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F409Ss. 145-147 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 21, Sch. 8 Pt. 1 (with Sch. 7)
146 Additional charge in respect of certain living accommodation.U.K.
F410. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F410Ss. 145-147 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 21, Sch. 8 Pt. 1 (with Sch. 7)
[F411146A Priority of rules applying to living accommodation.U.K.
F412. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F411S. 146A inserted (with application in accordance with s. 106(3) of the amending Act) by Finance Act 1996 (c. 8), s. 106(2)
F412Ss. 145-147 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 21, Sch. 8 Pt. 1 (with Sch. 7)
147 Occupation of Chevening House.U.K.
F413. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F413Ss. 145-147 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 21, Sch. 8 Pt. 1 (with Sch. 7)
Payments on retirement, sick pay etc.U.K.
148 Payments and other benefits in connection with termination of employment, etc.U.K.
F414. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F414Ss. 148-151A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 22, Sch. 8 Pt. 1 (with Sch. 7)
149 Sick pay.U.K.
F415. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F415Ss. 148-151A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 22, Sch. 8 Pt. 1 (with Sch. 7)
150 Job release scheme allowances, maternity pay and statutory sick pay.U.K.
F416. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F416Ss. 148-151A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 22, Sch. 8 Pt. 1 (with Sch. 7)
151 Income support etc.U.K.
F417. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F417Ss. 148-151A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 22, Sch. 8 Pt. 1 (with Sch. 7)
[F418151A Jobseeker’s allowance.U.K.
F419. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F418S. 151A inserted (2.9.1996) by Jobseekers Act 1995 (c. 18), s. 41(2)(4), Sch. 2 para. 12; S.I. 1996/2208, art. 2(a)
F419Ss. 148-151A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 22, Sch. 8 Pt. 1 (with Sch. 7)
152[F420Notification of taxable amount of certain benefits].U.K.
F421. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F420S. 152 sidenote substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 23 (with Sch. 7)
F421S. 152 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 34, Sch. 10 Pt. 12 (with Sch. 9)
CHAPTER IIU.K.[F422EMPLOYEES EARNING £8,500 OR MORE AND DIRECTORS]
Textual Amendments
F422Pt. 5 Ch. 2 heading substituted by Finance Act 1989 (c. 26), s. 53(2)(a)
ExpensesU.K.
153 Payments in respect of expenses.U.K.
F423. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F423Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
Benefits in kindU.K.
154 General charging provision.U.K.
F424. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F424Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
155 Exceptions from the general charge.U.K.
F425. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F425Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F426155ZA Accommodation, supplies or services used in performing duties of employment.U.K.
F427. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F426S. 155ZA inserted (with effect in accordance with s. 57(2) of the amending Act) by Finance Act 2000 (c. 17), s. 57(1), Sch. 10 para. 2(1)
F427Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F428155ZB Power to provide for exemption of minor benefits.U.K.
F429. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F428S. 155ZB inserted (with effect in accordance with s. 57(2) of the amending Act) by Finance Act 2000 (c. 17), s. 57(1), Sch. 10 para. 3(1)
F429Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F430155AA Mobile telephones.U.K.
F431. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F430S. 155AA inserted (with effect in accordance with s. 44(6) of the amending Act) by Finance Act 1999 (c. 16), s. 44(1)
F431Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F432155A Care for children.U.K.
F433. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F432S. 155A inserted (1990-91 and subsequent years of assessment) by Finance Act 1990 (c. 29), s. 21(1)(3)
F433Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
156 Cash equivalent of benefits charged under section 154.U.K.
F434. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F434Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F435156A Limited exemption for computer equipment.U.K.
F436. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F435S. 156A inserted (with application in accordance with s. 45(3) of the amending Act) by Finance Act 1999 (c. 16), s. 45(1)
F436Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
157 Cars available for private use.U.K.
F437. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F437Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F438157A Cars available for private use: cash alternative, etc.U.K.
F439. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F438S. 157A inserted (with effect in accordance with s. 43(4) of the amending Act) by Finance Act 1995 (c. 4), s. 43(1)
F439Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
158 Car fuel.U.K.
F440. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F440Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
159 Pooled cars.U.K.
F441. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F441Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F442159AA Vans available for private use.U.K.
F443. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F442Ss. 159AA, 159AB inserted after s. 159 (27.7.1993 with effect for the year 1993-94 and subsequent years of assessment) by 1993 c. 34, s. 73, Sch. 4 paras. 4, 8
F443Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F444159AB Pooled vans.U.K.
F445. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F444Ss. 159AA, 159AB inserted after s. 159 (27.7.1993 with effect for the year 1993-94 and subsequent years of assessment) by 1993 c. 34, s. 73, Sch. 4 paras. 4, 8
F445Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F446159AC Heavier commercial vehicles available for private use.U.K.
F447. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F446S. 159AC inserted (27.7.1993 with effect for the year 1993-94 and subsequent years of assessment) by 1993 c. 34, s. 74(1)(3)
F447Ss. 153-159AC repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F448159A. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F449. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F448S. 159A inserted (1991-92 and subsequent years of assessment) by Finance Act 1991 (c. 31), s. 30(2)(3)
F449S. 159A repealed (with effect in accordance with s. 44(6) of the repealing Act) by Finance Act 1999 (c. 16), ss. 44(2), 139, Sch. 20 Pt. 3(9), Note
160 Beneficial loan arrangements.U.K.
F450. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F450Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
161 Exceptions from section 160.U.K.
F451. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F451Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F452161A Treatment of qualifying loans.U.K.
F453. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F452S. 161A inserted (with effect in accordance with s. 57(2) of the amending Act) by Finance Act 2000 (c. 17), s. 57(1), Sch. 10 para. 4(1)
F453Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F454161B Beneficial loans: loans on ordinary commercial terms.U.K.
F455. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F454S. 161B inserted (with effect in accordance with s. 57(2) of the amending Act) by Finance Act 2000 (c. 17), s. 57(1), Sch. 10 para. 5(1)
F455Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
162 Employee shareholdings.U.K.
F456. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F456Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
163 Expenses connected with living accommodation.U.K.
F457. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F457Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
164 Director’s tax paid by employer.U.K.
F458. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F458Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
165 Scholarships.U.K.
F459. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F459Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
General supplementary provisionsU.K.
166 Notice of nil liability under this Chapter.U.K.
F460. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F460Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
167 Employment to which this Chapter applies.U.K.
F461. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F461Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
168 Other interpretative provisions.U.K.
F462. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F462Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F463168A Price of a car as regards a year.U.K.
F464. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F463Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F464Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F465168AA Equipment to enable disabled person to use car.U.K.
F466. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F465S. 168AA inserted (with effect in accordance with s. 44(3) of the amending Act) by Finance Act 1995 (c. 4), s. 44(2)
F466Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
[F467168AB Equipment etc. to enable car to run on road fuel gas.U.K.
F468. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F467S. 168AB inserted (with effect in accordance with s. 60(6) of the amending Act) by Finance Act 1998 (c. 36), s. 60(3)
F468Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F469168B Price of a car: accessories not included in list price.U.K.
F470. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F469Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F470Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F471168C Price of a car: accessories available after car first made available.U.K.
F472. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F471Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F472Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F473168D Price of a car: capital contributions.U.K.
F474. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F473Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F474Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F475168E Price of a car: replacement accessories.U.K.
F476. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F475Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F476Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F477168F Price of a car: classic cars.U.K.
F478. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F477Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F478Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
F479168G Price of a car: cap for expensive car.U.K.
F480. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F479Ss. 168A-168G inserted (with effect for the year 1994-95 and subsequent years of assessment) by 1993 c. 34, s. 72, Sch. 3 paras. 4, 7
F480Ss. 160-168G repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 24, Sch. 8 Pt. 1 (with Sch. 7)
CHAPTER IIIU.K. PROFIT-RELATED PAY
PreliminaryU.K.
169 Interpretation.U.K.
F481. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F481Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
170 Taxation of profit-related pay.U.K.
F482. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F482Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
The reliefU.K.
171 Relief from tax.U.K.
F483. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F483Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
172 Exceptions from tax.U.K.
F484. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F484Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
RegistrationU.K.
173 Persons who may apply for registration.U.K.
F485. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F485Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
174 Excluded employments.U.K.
F486. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F486Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
175 Applications for registration.U.K.
F487. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F487Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
176 Registration.U.K.
F488. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F488Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
177 Change of scheme employer.U.K.
F489. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F489Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
[F490177A Death of scheme employer.U.K.
F491. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F490Ss. 177A, 177B inserted by Finance Act 1989 (c. 26), Sch. 4 para. 3
F491Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
177B Alteration of scheme’s terms.U.K.
F492. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F492Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
178 Cancellation of registration.U.K.
F493. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F493Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
AdministrationU.K.
179 Recovery of tax from scheme employer.U.K.
F494. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F494Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
180 Annual returns etc.U.K.
F495. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F495Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
181 Other information.U.K.
F496. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F496Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
182 Appeals.U.K.
F497. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F497Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
SupplementaryU.K.
183 Partnerships.U.K.
F498. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F498Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
184 Independent accountants.U.K.
F499. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F499Ss. 169-184 (Pt. 5 Ch. 3) repealed (with effect in accordance with s. 61(2)(3) of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3), Note 1 (with saving in Note 2; and Ch. 3 modified, as so saved, by s. 61(1) of the repealing Act)
CHAPTER IVU.K. OTHER EXEMPTIONS AND RELIEFS
Share option and profit sharing schemesU.K.
185 Approved share option schemes.U.K.
F500. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F500S. 185 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 25, Sch. 8 Pt. 1 (with Sch. 7)
186 Approved profit sharing schemes.U.K.
(1)M8The provisions of this section apply where, after 5th April 1979 [F501and before 1st January 2003], the trustees of an approved profit sharing scheme appropriate shares—
(a)which have previously been acquired by the trustees, and
(b)as to which the conditions in Part II of Schedule 9 are fulfilled,
to an individual who participates in the scheme (“the participant”).
(2)M9Notwithstanding that, by virtue of such an appropriation of shares as is mentioned in subsection (1) above, the beneficial interest in the shares passes to the participant to whom they are appropriated—
(a)the value of the shares at the time of the appropriation shall be treated as not being income of his chargeable to tax under Schedule E; and
(b)he shall not be chargeable to income tax under that Schedule by virtue of [F502section 78 or 79 of the Finance Act 1988 in respect of the shares] or by virtue of section 162 in any case where the shares are appropriated to him at an undervalue within the meaning of that section.
(3)M10Subject to the provisions of this section and paragraph 4 of Schedule 10, if, in respect of or by reference to any of a participant’s shares, the trustees become or the participant becomes entitled, before the release date, to receive any money or money’s worth (“a capital receipt”), F503. . . the appropriate percentage (determined as at the time the trustees become or the participant becomes so entitled) of so much of the amount or value of the receipt as exceeds the appropriate allowance for that year, as determined under subsection (12) below[F504 counts as employment income of the participant for the year of assessment in which the entitlement arises].
(4)M11If the trustees dispose of any of a participant’s shares at any time before the release date or, if it is earlier, the date of the participant’s death, then, subject to subsections (6) and (7) below, F505. . . the appropriate percentage of the locked-in value of the shares at the time of the disposal[F506 counts as employment income of the participant for the year of assessment in which the disposal takes place].
(5)M12Subject to paragraphs 5 and 6(6) of Schedule 10, the locked-in value of a participant’s shares at any time is—
(a)if prior to that time he has become [F507 entitled to a capital receipt (within the meaning of subsection (3) above) which is referable to those shares and—
(i)an amount calculated by reference to that capital receipt counts as his employment income by virtue of subsection (3) above, or
(ii)if the entitlement to the capital receipt arose before 6th April 2003, he was chargeable to income tax by virtue of that subsection (as it had effect before that date) in respect of that capital receipt,]
the amount by which their initial market value exceeds the amount or value of that capital receipt or, if there has been more than one such receipt, the aggregate of them; and
(b)in any other case, their initial market value.
(6)Subject to subsection (7) below, if, on a disposal of shares falling within subsection (4) above, the proceeds of the disposal are less than the locked-in value of the shares at the time of the disposal, subsection (4) above shall have effect as if that locked-in value were reduced to an amount equal to the proceeds of the disposal.
(7)If, at any time prior to the disposal of any of a participant’s shares, a payment was made to the trustees to enable them to exercise rights arising under a rights issue, then, subject to subsection (8) below, subsections (4) and (6) above shall have effect as if the proceeds of the disposal were reduced by an amount equal to that proportion of that payment or, if there was more than one, of the aggregate of those payments which, immediately before the disposal, the market value of the shares disposed of bore to the market value of all the participant’s shares held by the trustees at that time.
(8)M13For the purposes of subsection (7) above—
(a)no account shall be taken of any payment to the trustees if or to the extent that it consists of the proceeds of a disposal of rights arising under a rights issue; and
(b)in relation to a particular disposal the amount of the payment or, as the case may be, of the aggregate of the payments referred to in that subsection shall be taken to be reduced by an amount equal to the total of the reduction (if any) previously made under that subsection in relation to earlier disposals;
and any reference in subsection (7) or paragraph (a) above to the rights arising under a rights issue is a reference to rights conferred in respect of a participant’s shares, being rights to be allotted, on payment, other shares or securities or rights of any description in the same company.
(9)M14If at any time the participant’s beneficial interest in any of his shares is disposed of, the shares in question shall be treated for the purposes of the relevant provisions as having been disposed of at that time by the trustees for (subject to subsection (10) below) the like consideration as was obtained for the disposal of the beneficial interest; and for the purposes of this subsection there is no disposal of the participant’s beneficial interest if and at the time when—
(a)in England and Wales or Northern Ireland, that interest becomes vested in any person on the insolvency of the participant or otherwise by operation of law, or
(b)in Scotland, that interest becomes vested in a judicial factor, in a trustee on the participant’s sequestrated estate or in a trustee for the benefit of the participant’s creditors.
(10)If—
(a)a disposal of shares falling within subsection (4) above is a transfer to which paragraph 2(2)(c) of Schedule 9 applies, or
[F508(b)any other disposal falling within that subsection is not at arm’s length,]
(c)a disposal of shares falling within [F509that subsection] is one which is treated as taking place by virtue of subsection (9) above and takes place within the period of retention,
then for the purposes of the relevant provisions the proceeds of the disposal shall be taken to be equal to the market value of the shares at the time of the disposal.
(11)M15Where the trustees of an approved scheme acquire any shares as to which the requirements of Part II of Schedule 9 are fulfilled and, within the period of 18 months beginning with the date of their acquisition, those shares are appropriated in accordance with the scheme, section 686 shall not apply to income consisting of dividends on those shares received by the trustees; and, for the purpose of determining whether any shares are appropriated within that period, shares which were acquired at an earlier time shall be taken to be appropriated before shares of the same class which were acquired at a later time.
(12)M16For the purposes of subsection (3) above, “the appropriate allowance”, in relation to any year of assessment, means a sum which, subject to a maximum of [F510£60], is the product of multiplying £20 by 1 plus the number of years which fall within the period of [F511three years] immediately preceding the year in question and in which shares were appropriated to the participant under the scheme; and if in any year (and before the release date) the trustees become or the participant becomes entitled, in respect of or by reference to any of his shares, to more than one capital receipt, the receipts shall be set against the appropriate allowance for that year in the order in which they are received.
(13)Schedule 10 shall have effect with respect to profit sharing schemes.
Textual Amendments
F501Words in s. 186(1) inserted (28.7.2000) by Finance Act 2000 (c. 17), s. 49(3)
F502Words in s. 186(2)(b) substituted (in respect of acquisitions of shares on or after 26.10.1987) by Finance Act 1988 (c. 39), s. 89
F503Words in s. 186(3) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 26(2)(a), Sch. 8 Pt. 1 (with Sch. 7)
F504Words in s. 186(3) added (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 26(2)(b) (with Sch. 7)
F505Words in s. 186(4) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 26(3)(a), Sch. 8 Pt. 1 (with Sch. 7)
F506Words in s. 186(4) added (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 26(3)(b) (with Sch. 7)
F507Words in s. 186(5)(a) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 26(4) (with Sch. 7)
F508S. 186(10)(b) substituted (with effect in accordance with s. 134(2) of the amending Act) by Finance Act 1996 (c. 8), s. 134(1), Sch. 20 para. 11(a)
F509Words in s. 186(10)(c) substituted (with effect in accordance with s. 134(2) of the amending Act) by Finance Act 1996 (c. 8), s. 134(1), Sch. 20 para. 11(b)
F510Words in s. 186(12) substituted (with effect in accordance with s. 118(2) of the amending Act) by Finance Act 1996 (c. 8), s. 118(1)(a)
F511Words in s. 186(12) substituted (with effect in accordance with s. 118(2) of the amending Act) by Finance Act 1996 (c. 8), s. 118(1)(b)
Modifications etc. (not altering text)
C22S. 186 modified (29.4.1996) by Finance Act 1996 (c. 8), ss. 115(1), 116(3)
C23S. 186 continued (6.4.2003 with effect in accordance with s. 723(1) of the affecting Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 418(3) (with Sch. 7)
Marginal Citations
M8Source—1978 s.53(1)
M9Source—1978 s.53(3)
M10Source—1978 s.56(1); 1982 s.42(1)
M11Source—1978 s.55(1)
M12Source—1978 s.55(2)-(4)
M13Source—1978 s.55(5), (9)
M14Source—1978 s.55(7), (8)
M15Source—1978 s.53(6)
M16Source—1978 s.56(6); 1980 s.46(6); 1982 s.42(2); 1985 s.45(4)
187 Interpretation of sections 185 and 186 and Schedules 9 and 10.U.K.
(1)[F512M17In sections 185 and 186, this section and Schedules 9 and 10 “the relevant provisions” means those sections (including this section) and Schedules.]
(2)[F512For the purposes of the relevant provisions, except where the context otherwise requires—
“appropriate percentage” shall be construed in accordance with paragraph 3 of Schedule 10;
“approved”, in relation to a scheme, means approved under Schedule 9;
“associated company” has the same meaning as in section 416, except that, for the purposes of paragraph 23 of Schedule 9, subsection (1) of that section shall have effect with the omission of the words “ or at any time within one year previously ”;
“bonus date” has the meaning given by paragraph 17 of Schedule 9;
“capital receipt” means money or money’s worth to which the trustees of or a participant in a profit sharing scheme become or becomes entitled as mentioned in section 186(3), but subject to paragraph 4 of Schedule 10;
“certified contractual savings scheme” has the meaning given by section 326;
“control” has the same meaning as in section 840;
“grantor”, in relation to any scheme, means the company which has established the scheme;
“group scheme” and, in relation to such a scheme, “participating company” have the meanings given by paragraph 1(3) and (4) of Schedule 9;
“initial market value”, in relation to shares in a profit sharing scheme, has the meaning given by paragraph 30(4) of Schedule 9;
“locked-in value”, in relation to any shares, shall be construed in accordance with section 186(5);
“market value” has the same meaning as in Part VIII of the [F5131992 Act];
“new holding” has the meaning given by section [F513126(1)(b) of the 1992 Act];
“participant”, in relation to a profit sharing scheme, means an individual to whom the trustees of the scheme have appropriated shares;
“”, in relation to a participant in a profit sharing scheme, means, subject to paragraph 5(4) of Schedule 10, shares which have been appropriated to the participant by the trustees;
F514. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
“period of retention” has the meaning given by paragraph 2 of Schedule 10;
“release date”, in relation to any of the shares of a participant in a profit sharing scheme, means the [F515third] anniversary of the date on which they were appropriated to him;
“relevant amount”, in relation to a participant in a profit sharing scheme, means an amount which is [F516not less than £3,000 and not more than £8,000] but which, subject to that, is 10 per cent. of his salary (determined under subsection (5) below) for the year of assessment in question or the preceding year of assessment, whichever is the greater;
“relevant requirements” has the meaning given by paragraph 1 of Schedule 9;
“” has the meaning given by paragraph 1 of Schedule 9;
“scheme” means a savings-related share option scheme, a share option scheme which is not a savings-related share option scheme or a profit sharing scheme, as the context may require;
“” includes stock;
[F517“specified age”, in relation to a scheme, means the age specified in pursuance of paragraph 8A of Schedule 9 as the specified age for the purposes of the scheme;]
“the trustees”, in relation to an approved profit sharing scheme or the shares of a participant in such a scheme, means the body of persons for the establishment of which the scheme must provide as mentioned in paragraph 30 of Schedule 9; and
“just instrument”, in relation to an approved profit sharing scheme, means the instrument referred to in paragraph 30(1)(c) of Schedule 9.]
(3)[F512M18For the purposes of the application of the relevant provisions in relation to any share option scheme or profit sharing scheme, a person has a material interest [F518in a company if he, either on his own or with one or more associates, or if any associate of his with or without such other associates,—
(a)is the beneficial owner of, or able, directly or through the medium of other companies, or by any other indirect means to control, more than 25 per cent., or in the case of a share option scheme which is not a savings-related share option scheme more than 10 per cent., of the ordinary share capital of the company, or
(b)where the company is a close company, possesses, or is entitled to acquire, such rights as would, in the event of the winding-up of the company or in any other circumstances, give an entitlement to receive more than 25 per cent., or in the case of a share option scheme which is not a savings-related share option scheme more than 10 per cent., of the assets which would then be available for distribution among the participators.]
In this subsection “associate” has the meaning given by section 417(3) and (4) [F518and “participator” has the meaning given by section 417(1)].]
(4)[F512M19Subsection (3) above shall have effect subject to the provisions of Part VI of Schedule 9.]
(5)M20For the purposes of subsection (2) above, a participant’s salary for a year of assessment means such of the emoluments of the office or employment by virtue of which he is entitled to participate in a profit sharing scheme as are liable to be paid in that year under deduction of tax pursuant to section 203 after deducting therefrom amounts included by virtue of Chapter II of this Part.
(6)[F512M21Section 839 shall apply for the purposes of the relevant provisions.]
(7)[F512M22For the purposes of the relevant provisions a company is a member of a consortium owning another company if it is one of a number of companies which between them beneficially own not less than three-quarters of the other company’s ordinary share capital and each of which beneficially owns not less than one-twentieth of that capital.]
(8)M23Where the disposal referred to in section 186(4) is made from a holding of shares which were appropriated to the participant at different times, then, in determining for the purposes of the relevant provisions—
(a)the initial market value and the locked-in value of each of those shares, F519. . .
(b)F519. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(9)M24Any of the relevant provisions with respect to—
(a)the order in which any of a participant’s shares are to be treated as disposed of for the purposes of those provisions, or
(b)the shares in relation to which an event is to be treated as occurring for any such purpose,
shall have effect in relation to a profit sharing scheme notwithstanding any direction given to the trustees with respect to shares of a particular description or to shares appropriated to the participant at a particular time.
(10)M25In the relevant provisions “workers’ cooperative” means a [F520registered society][F521, as defined in [F522section 1119 of CTA 2010]], which is a cooperative society and the rules of which include provisions which secure—
(a)that the only persons who may be members of it are those who are employed by, or by a subsidiary of, the society and those who are the trustees of its profit sharing scheme; and
(b)that, subject to any provision about qualifications for membership which is from time to time made by the members of the society by reference to age, length of service or other factors of any description, all such persons may be members of the society;
and in this subsection “cooperative society” has the same meaning as in [F523section 2 of the Co-operative and Community Benefit Societies Act 2014] or, as the case may be, [F524section 1 of] the M26Industrial and Provident Societies Act (Northern Ireland) 1969.
Textual Amendments
F512S. 187(1)-(4)(6)(7) repealed (except so far as relating to profit sharing schemes) (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 27, Sch. 8 Pt. 1 (with Sch. 7)
F513Words in s. 187(2) substituted (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(13) (with ss. 60, 101(1), 171, 201(3)).
F514S. 187(2): definition of "pensionable age" repealed (19.7.1995) by Pensions Act 1995 (c. 26), ss. 126, 177, 180(2)(a), Sch. 4 para. 12(a), Sch. 7 Pt. 2
F515Word in s. 187(2) substituted (with effect in accordance with s. 116(2)(3) of the amending Act) by Finance Act 1996 (c. 8), s. 116(1)
F516Words in s. 187(2) substituted (for the year 1991-92 and subsequent years of assessment) by virtue of Finance Act 1991 (c. 31), s. 41(1)(2)
F517S. 187(2): definition of "specified age" inserted by Finance Act 1991 (c. 31), s. 38(4)
F518Words in s. 187(3) substituted (in relation to accounting periods beginning after 31.3.1989) by Finance Act 1989 (c. 26), Sch. 12 para. 9
F519S. 187(8)(b) and preceding word repealed (with effect in accordance with s. 117(3) of the repealing Act) by Finance Act 1996 (c. 8), ss. 117(2), 205, Sch. 41 Pt. 5(5), Note 1
F520Words in s. 187(10) substituted (1.8.2014 in accordance with s. 154 of the amending Act) by Co-operative and Community Benefit Societies Act 2014 (c. 14), Sch. 4 para. 40(a) (with Sch. 5)
F521Words in s. 187(10) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 95 (with Sch. 2 Pts. 1, 2)
F522Words in s. 187(10) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 13 (with Sch. 2)
F523Words in s. 187(10) substituted (1.8.2014 in accordance with s. 154 of the amending Act) by Co-operative and Community Benefit Societies Act 2014 (c. 14), Sch. 4 para. 40(b) (with Sch. 5)
F524Words in s. 187(10) inserted (1.8.2014 in accordance with s. 154 of the amending Act) by Co-operative and Community Benefit Societies Act 2014 (c. 14), Sch. 4 para. 40(c) (with Sch. 5)
Modifications etc. (not altering text)
C24S. 187 modified (29.4.1996) by Finance Act 1996 (c. 8), ss. 115(1), 116(3)
C25S. 187 applied (29.4.1996) by Finance Act 1996 (c. 8), s. 114, Sch. 16 para. 5(1)
C26S. 187 continued so far as relating to APS schemes (6.4.2003 with effect in accordance with s. 723(1) of the affecting Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 418(3) (with Sch. 7)
Marginal Citations
M17Source—1978 ss.53(2), 54(2), (4)(b), 6, 56(1), 57(1), (4), 61(1), Sch.9 1, 16; 1980 s.46(4), Sch.10 5(b), 8, 26(1); 1982 s.40(8); 1983 s.25(1); 1984 Sch.10 15(1), (2); 1985 s.45(2)
M18Source—1970 s.285(6); 1978 Sch.9 11(3)(b); 1980 Sch.10 26(2); 1984 Sch.10 4(4)
M19Source—1987 s.33(2)
M20Source—1978 s.61(4); 1983 s.25(2)
M21Source—1978 Sch.9 16; 1980 Sch.10 26(4); 1984 Sch.10 15(3)
M22Source—1978 Sch.9 17; 1980 Sch.10 26(5); 1984 Sch.10 15(4); 1986 s.23(5)
M23Source—1978 s.55(6)
M24Source—1978 s.61(2)
M25Source—1978 Sch.9 18; 1986 s.24(1)
M261969 c. 24. (N.I.).
[F525 Contributions in respect of share option gainsU.K.
Textual Amendments
F525S. 187A and preceding cross-heading inserted (with application in accordance with s. 56(1) of the amending Act) by Finance Act 2000 (c. 17), s. 56(1)
187A Relief for contributions in respect of share option gains.U.K.
F526. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F526S. 187A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(a), Sch. 8 Pt. 1 (with Sch. 7)
Retirement benefits etc.U.K.
188 Exemptions from section 148.U.K.
F527. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F527S. 188 repealed (with application in accordance with s. 58(4) of the repealing Act) by Finance Act 1998 (c. 36), s. 165, Sch. 27 Pt. 3(9), Note
189 Lump sum benefits on retirement.U.K.
F528. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F528Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
190Payments to MPs and others.U.K.
F529. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F529Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
191 Job release scheme allowances not to be treated as income.U.K.
F530. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F530Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F531 Removal expenses and benefitsU.K.
Textual Amendments
F531Ss. 191A, 191B and preceding cross-heading inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 76, Sch. 5 para.1
F532191A Removal expenses and benefits.U.K.
F533. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F532Ss. 191A, 191B and preceding cross-heading inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 76, Sch. 5 para.1
F533Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
F534191B Removal benefits: beneficial loan arrangements.U.K.
F535. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F534Ss. 191A, 191B and preceding cross-heading inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 76, Sch. 5 para.1
F535Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
Foreign emoluments and earnings, pensions and certain travel facilitiesU.K.
192 Relief from tax for foreign emoluments.U.K.
F536. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F536Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F537192A Foreign earnings deduction for seafarers.U.K.
F538. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F537S. 192A inserted (with effect in accordance with s. 63(5) of the amending Act) by Finance Act 1998 (c. 36), s. 63(2) (with s. 63(6)(7))
F538Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
193 Foreign earnings and travel expenses.U.K.
F539. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F539Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
194 Other foreign travel expenses.U.K.
F540. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F540Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
195 Travel expenses of employees not domiciled in the United Kingdom.U.K.
F541. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F541Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
196 Foreign pensions.U.K.
F542. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F542Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
197 Leave travel facilities for the armed forces.U.K.
F543. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F543Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F544197A Car parking facilitiesU.K.
F545. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F544S. 197A inserted (1988-89 and subsequent years of assessment) by Finance Act 1988 (c. 39), s. 46(4)
F545Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F546197AA Works bus services.U.K.
F547. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F546Ss. 197AA, 197AB inserted (with effect in accordance with s. 48(2) of the amending Act) by Finance Act 1999 (c. 16), s. 48(1)
F547Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
197AB Support for public transport road services.U.K.
F548. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F546Ss. 197AA, 197AB inserted (with effect in accordance with s. 48(2) of the amending Act) by Finance Act 1999 (c. 16), s. 48(1)
F548Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F549197AC Provision of cycle or cyclist’s safety equipment.U.K.
F550. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F549S. 197AC inserted (with effect in accordance with s. 50(3) of the amending Act) by Finance Act 1999 (c. 16), s. 50(1)
F550Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F551 Mileage allowancesU.K.
Textual Amendments
F551Ss. 197AD-197AH and preceding cross-heading inserted (with effect in accordance with s. 57(4) of the amending Act) by Finance Act 2001 (c. 9), s. 57(1)
197AD Mileage allowance paymentsU.K.
F552. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F552Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
197AE Passenger paymentsU.K.
F553. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F553Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
197AF Mileage allowance reliefU.K.
F554. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F554Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
197AG Giving effect to mileage allowance reliefU.K.
F555. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F555Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
197AH Interpretation of sections 197AD to 197AGU.K.
F556. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F556Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F557 Mileage allowancesU.K.
Textual Amendments
F557Ss. 197B-197F and preceding cross-heading inserted by Finance Act 1990 (c. 29), s. 23, Sch. 4
197B. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F558. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F558Ss. 197B-197F repealed (with effect in accordance with Sch. 33 Pt. 2(1) Note of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(1)
197C. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F559. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F559Ss. 197B-197F repealed (with effect in accordance with Sch. 33 Pt. 2(1) Note of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(1)
197D. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F560. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F560Ss. 197B-197F repealed (with effect in accordance with Sch. 33 Pt. 2(1) Note of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(1)
197E. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F561. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F561Ss. 197B-197F repealed (with effect in accordance with Sch. 33 Pt. 2(1) Note of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(1)
197F. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F562. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F562Ss. 197B-197F repealed (with effect in accordance with Sch. 33 Pt. 2(1) Note of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(1)
[F563 Sporting and recreational facilitiesU.K.
Textual Amendments
F563S. 197G and preceding cross-heading inserted (27.7.1993 with application for the year 1993-94 and subsequent years of assessment) by Finance Act 1993 (c. 34), s. 75(1)(2)
197G Sporting and recreational facilities.U.K.
F564. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F564Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
Other expenses, subscriptions etc.U.K.
198 Relief for necessary expenses.U.K.
F565. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F565Ss. 189-198 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(b), Sch. 8 Pt. 1 (with Sch. 7)
[F566198A. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
F567. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F566S. 198A inserted (with effect in accordance with s. 62(5) of the amending Act) by Finance Act 1997 (c. 16), s. 62(2)
F567S. 198A repealed (with effect in accordance with Sch. 27 Pt. 3(10) Note of the repealing Act) by Finance Act 1998 (c. 36), s. 165, Sch. 27 Pt. 3(10)
199 Expenses necessarily incurred and defrayed from official emoluments.U.K.
F568. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F568Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200 Expenses of Members of Parliament.U.K.
F569. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F569Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F570200ZA Expenses of members of Scottish Parliament, National Assembly for Wales or Northern Ireland Assembly.U.K.
F571. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F570S. 200ZA inserted (with effect in accordance with s. 52(2) of the amending Act) by Finance Act 1999 (c. 16), s. 52(1), Sch. 5 para. 2(1)
F571Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F572200AA Incidental benefits for holders of certain offices etc.U.K.
F573. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F572S. 200AA inserted (with effect in accordance with s. 108(2) of the amending Act) by Finance Act 1996 (c. 8), s. 108(1)
F573Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F574200A Incidental overnight expenses.U.K.
F575. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F574S. 200A inserted (with effect in accordance with s. 93(5) of the amending Act) by Finance Act 1995 (c. 4), s. 93(4)
F575Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F576200B Work-related training provided by employers.U.K.
F577. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F576Ss. 200B-200D inserted (with application in accordance with s. 63(3) of the amending Act) by Finance Act 1997 (c. 16), s. 63(1)
F577Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200C Expenditure excluded from section 200B.U.K.
F578. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F576Ss. 200B-200D inserted (with application in accordance with s. 63(3) of the amending Act) by Finance Act 1997 (c. 16), s. 63(1)
F578Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200D Other work-related training.U.K.
F579. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F576Ss. 200B-200D inserted (with application in accordance with s. 63(3) of the amending Act) by Finance Act 1997 (c. 16), s. 63(1)
F579Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F580200E Education and training funded by employers.U.K.
F581. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F580Ss. 200E-200H, 200J inserted (with application in accordance with s. 58(3) of the amending Act) by Finance Act 2000 (c. 17), s. 58(1)
F581Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200F Section 200E: exclusion of expenditure not directly related to training.U.K.
F582. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F580Ss. 200E-200H, 200J inserted (with application in accordance with s. 58(3) of the amending Act) by Finance Act 2000 (c. 17), s. 58(1)
F582Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200G Section 200E: exclusion of expenditure if contributions not generally available to staff.U.K.
F583. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F580Ss. 200E-200H, 200J inserted (with application in accordance with s. 58(3) of the amending Act) by Finance Act 2000 (c. 17), s. 58(1)
F583Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200H Section 200E: exclusion of expenditure otherwise relieved.U.K.
F584. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F580Ss. 200E-200H, 200J inserted (with application in accordance with s. 58(3) of the amending Act) by Finance Act 2000 (c. 17), s. 58(1)
F584Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
200J Education or training funded by third parties.U.K.
F585. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F580Ss. 200E-200H, 200J inserted (with application in accordance with s. 58(3) of the amending Act) by Finance Act 2000 (c. 17), s. 58(1)
F585Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
201 Fees and subscriptions to professional bodies, learned societies etc.U.K.
F586. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F586Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F587201AA Employee liabilities and indemnity insurance.U.K.
F588. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F587S. 201AA inserted (with effect in accordance with s. 91(3) of the amending Act) by Finance Act 1995 (c. 4), s. 91(1)
F588Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
[F589201A Expense of entertainers.U.K.
F590. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F589S. 201A inserted by Finance Act 1990 (c. 29), s. 77
F590Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
202 Donations to charity: payroll deduction scheme.U.K.
F591. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F591Ss. 199-202 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 28(c), Sch. 8 Pt. 1 (with Sch. 7)
CHAPTER VU.K. ASSESSMENT, COLLECTION, RECOVERY AND APPEALS
[F592202A Assessment on receipts basis.U.K.
F593. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F592Ss. 202A, 202B inserted by Finance Act 1989 (c. 26), s. 37
F593Ss. 202A, 202B repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 29, Sch. 8 Pt. 1 (with Sch. 7)
202B Receipts basis: meaning of receipt.U.K.
F594. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F594Ss. 202A, 202B repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 29, Sch. 8 Pt. 1 (with Sch. 7)
203 Pay as you earn.U.K.
F595. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F595Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F596203A P.A.Y.E.: meaning of payment.U.K.
F597. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F596S. 203A inserted by Finance Act 1989 (c. 26), s. 37(2)(4)(5)
F597Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F598203B PAYE: payment by intermediary.U.K.
F599. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F598S. 203B inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 125
F599Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F600203C PAYE: employee of non-UK employer.U.K.
F601. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F600Ss. 203C-203E inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 126
F601Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
203D PAYE: employee non-resident, etc.U.K.
F602. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F600Ss. 203C-203E inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 126
F602Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
203E PAYE: mobile UK workforce.U.K.
F603. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F600Ss. 203C-203E inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 126
F603Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F604203F PAYE: tradeable assets.U.K.
F605. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F604S. 203F inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 127
F605Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F606203FA PAYE: enhancing the value of an asset.U.K.
F607. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F606S. 203FA inserted (with effect in accordance with s. 66(2) of the amending Act) by Finance Act 1998 (c. 36), s. 66(1) (with s. 66(3))
F607Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F608203FB PAYE: gains from share options etc.U.K.
F609. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F608S. 203FB inserted (with effect in accordance with s. 67(2) of the amending Act) by Finance Act 1998 (c. 36), s. 67(1) (with s. 67(3))
F609Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F610203G PAYE: non-cash vouchers.U.K.
F611. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F610S. 203G inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 128
F611Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F612203H PAYE: credit-tokens.U.K.
F613. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F612S. 203H inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 129
F613Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F614203I PAYE: cash vouchers.U.K.
F615. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F614S. 203I inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 130
F615Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
[F616203J S.203B to s.203I: accounting for tax.U.K.
F617. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F616Ss. 203J-203L inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 131
F617Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
203K Trading arrangements.U.K.
F618. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F616Ss. 203J-203L inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 131
F618Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
203L S.203B to s.203K: interpretation, etc.U.K.
F619. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F616Ss. 203J-203L inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 131
F619Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
204 P.A.Y.E repayments.U.K.
F620. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F620Ss. 203-204 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 30, Sch. 8 Pt. 1 (with Sch. 7)
205 Assessments unnecessary in certain circumstances.U.K.
F621. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F621Ss. 205, 206 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 31, Sch. 8 Pt. 1 (with Sch. 7)
206 Additional provision for certain assessments.U.K.
F622. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F622Ss. 205, 206 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 31, Sch. 8 Pt. 1 (with Sch. 7)
[F623206A PAYE settlement agreements.U.K.
F624. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F623S. 206A inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 110
F624S. 206A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 32, Sch. 8 Pt. 1 (with Sch. 7)
207 Disputes as to domicile or ordinary residence.U.K.
F625. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F625S. 207 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 32, Sch. 8 Pt. 1 (with Sch. 7)
PART VIU.K. COMPANY DISTRIBUTIONS, TAX CREDITS ETC
CHAPTER IU.K. TAXATION OF COMPANY DISTRIBUTIONS
Modifications etc. (not altering text)
C27Pt. 6 Chs. 1-3: power to amend conferred (1.4.2009 with effect in accordance with s. 1329(1) of the affecting Act) by Corporation Tax Act 2009 (c. 4), s. 533(2)(3)(d)
[F626207A Application of lower rate to company distributions.U.K.
F627. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F626S. 207A inserted (27.7.1993 with application in relation to the year 1993-94 and subsequent years of assessment) by 1993 c. 34, s. 77(1)(2)(5)
208 U.K. company distributions not generally chargeable to corporation tax.U.K.
F628. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F628S. 208 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 96, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F629CHAPTER IIU.K. MATTERS WHICH ARE DISTRIBUTIONS FOR THE PURPOSES OF THE CORPORATION TAX ACTS]
Textual Amendments
F629Pt. 6 Ch. 2 (ss. 209-211) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2)
209 Meaning of “distribution”.U.K.
F630. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F630Pt. 6 Ch. 2 (ss. 209-211) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2)
[F631209A Section 209(3AA): link to shares of company or associated companyU.K.
F632. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F631Ss. 209A, 209B inserted (with effect in accordance with s. 102(3) of the amending Act) by Finance Act 2002 (c. 23), s. 102(2)
F632Pt. 6 Ch. 2 (ss. 209-211) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2)
209B Section 209(3AA): hedging arrangementsU.K.
F633. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F631Ss. 209A, 209B inserted (with effect in accordance with s. 102(3) of the amending Act) by Finance Act 2002 (c. 23), s. 102(2)
F633Pt. 6 Ch. 2 (ss. 209-211) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2)
210 Bonus issue following repayment of share capital.U.K.
F634. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F634Pt. 6 Ch. 2 (ss. 209-211) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2)
211 Matters to be treated or not to be treated as repayments of share capital.U.K.
F635. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F635Pt. 6 Ch. 2 (ss. 209-211) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 14, Sch. 3 Pt. 1 (with Sch. 2)
[F636CHAPTER IIIU.K. MATTERS WHICH ARE NOT DISTRIBUTIONS FOR THE PURPOSES OF THE CORPORATION TAX ACTS]
Textual Amendments
F636Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
Payments of interestU.K.
212 Interest etc. paid in respect of certain securities.U.K.
F637. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F637Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
DemergersU.K.
213 Exempt distributions.U.K.
F638. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F638Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
[F639213AExempt distributions: division of businessU.K.
F640. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F639S. 213A inserted (29.11.2007 with effect in accordance with reg. 3(1) of the amending S.I. (as retrospectively amended by S.I. 2008/1579, reg. 4(1)) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), reg. 1(2), Sch. 1 para. 13
F640Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
214 Chargeable payments connected with exempt distributions.U.K.
F641. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F641Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
215 Advance clearance by Board of distributions and payments.U.K.
F642. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F642Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
216 Returns.U.K.
F643. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F643Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
217 Information.U.K.
F644. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F644Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2) (subject to the omission of s. 217(4), so far as it continues to have effect, by virtue of Finance Act 2011 (c. 11), Sch. 23 paras. 55(b), 65)
218 Interpretation of sections 213 to 217.U.K.
F645. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F645Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
Purchase of own sharesU.K.
219 Purchase by unquoted trading company of own shares.U.K.
F646. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F646Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
220 Conditions as to residence and period of ownership.U.K.
F647. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F647Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
221 Reduction of vendor’s interest as shareholder.U.K.
F648. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F648Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
222 Conditions applicable where purchasing company is member of group.U.K.
F649. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F649Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
223 Other conditions.U.K.
F650. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F650Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
224 Relaxation of conditions in certain cases.U.K.
F651. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F651Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
225 Advance clearance of payments by Board.U.K.
F652. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F652Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
226 Returns and information.U.K.
F653. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F653Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2) (subject to the omission of s. 226(4), so far as it continues to have effect, by virtue of Finance Act 2011 (c. 11), Sch. 23 paras. 55(c), 65)
227 Associated persons.U.K.
F654. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F654Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
228 Connected persons.U.K.
F655. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F655Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
229 Other interpretative provisions.U.K.
F656. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F656Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
Stock dividendsU.K.
230 Stock dividends: distributions.U.K.
F657. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F657Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
[F658Industrial and provident society dividends etcU.K.
Textual Amendments
F658S. 230A and preceding cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 100 (with Sch. 2 Pts. 1, 2)
230ADividend or bonus granted by industrial and provident societyU.K.
F659. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F659Pt. 6 Ch. 3 (ss. 212-230A) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 15, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER IVU.K. TAX CREDITS
231 Tax credits for certain recipients of qualifying distributions.U.K.
F660. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F660S. 231 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 16, Sch. 3 Pt. 1 (with Sch. 2)
[F661231A Restrictions on the use of tax credits by pension funds.U.K.
F662. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F661S. 231A inserted (with effect in accordance with s. 19(3) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 19(2)
F662S. 231A repealed (with effect in accordance with s. 30(11), Sch. 8 Pt. 2(9) Note 3 of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), s. 30(8), Sch. 8 Pt. 2(9)
[F663231AA No tax credit for borrower under stock lending arrangement or interim holder under repurchase agreement.U.K.
F664. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F663S. 231AA inserted (with effect in accordance with s. 102(9) of the amending Act) by Finance Act 1998 (c. 36), s. 102(1)
F664S. 231AA repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 17, Sch. 3 Pt. 1 (with Sch. 2)
[F665231AB No tax credit for original owner under repurchase agreement in respect of certain manufactured dividends.U.K.
F666. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F665S. 231AB inserted (with effect in accordance with s. 102(10) of the amending Act) by Finance Act 1998 (c. 36), s. 102(2)
F666S. 231AB repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 18, Sch. 3 Pt. 1 (with Sch. 2)
[F667231B Consequences of certain arrangements to pass on the value of a tax credit.U.K.
F668. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F667S. 231B inserted (with effect in accordance with s. 28(2) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 28(1)
F668S. 231B omitted (with effect in accordance with Sch. 1 para. 73(1) of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(2)
232 Tax credits for non-U.K. residents.U.K.
F669. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F669S. 232 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 117, Sch. 3 (with Sch. 2)
233 Taxation of certain recipients of distributions and in respect of non-qualifying distributions.U.K.
F670. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F670S. 233 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 118, Sch. 3 (with Sch. 2)
234 Information relating to distributions.U.K.
F671. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F671S. 234 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 20, Sch. 3 Pt. 1 (with Sch. 2)
[F672234A Information relating to distributions: further provisions.U.K.
F673. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F672S. 234A inserted (with application in relation to distributions begun after 16.7.1992) by Finance (No. 2) Act 1992 (c. 48), s. 32(1)(4).
F673S. 234A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 21, Sch. 3 Pt. 1 (with Sch. 2)
F674235 Distributions of exempt funds etc.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F674Ss. 235-237 repealed (with effect in accordance with Sch. 4 para. 7(2), Sch. 8 Pt. 2(9) Note 3 of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 4 para. 7(1), Sch. 8 Pt. 2(9)
F675236 Provisions supplementary to section 235.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F675Ss. 235-237 repealed (with effect in accordance with Sch. 4 para. 7(2), Sch. 8 Pt. 2(9) Note 3 of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 4 para. 7(1), Sch. 8 Pt. 2(9)
F676237 Disallowance of reliefs in respect of bonus issues.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F676Ss. 235-237 repealed (with effect in accordance with Sch. 4 para. 7(2), Sch. 8 Pt. 2(9) Note 3 of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 4 para. 7(1), Sch. 8 Pt. 2(9)
CHAPTER VU.K. ADVANCE CORPORATION TAX AND FRANKED INVESTMENT INCOME
238 Interpretation of terms and collection of ACT.U.K.
F677. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F677S. 238 repealed (with effect in accordance with Sch. 3 para. 11(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 11(1), Sch. 27 Pt. 3(2), Note
239 Set-off of ACT against liability to corporation tax.U.K.
F678. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F678S. 239 repealed (with effect in accordance with Sch. 3 para. 12(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 12(1), Sch. 27 Pt. 3(2), Note (with Sch. 3 para. 12(3)-(6))
240 Set-off of company’s surplus ACT against subsidiary’s liability to corporation tax.U.K.
F679. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F679S. 240 repealed (with effect in accordance with Sch. 3 para. 13(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 13(1), Sch. 27 Pt. 3(2), Note
241 Calculation of ACT where company receives franked investment income.U.K.
F680. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F680S. 241 repealed (with effect in accordance with Sch. 3 para. 14(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 14(1), Sch. 27 Pt. 3(2), Note
242 Set-off of losses etc. against surplus of franked investment income.U.K.
F681. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F681Ss. 242-244 repealed (with effect in accordance with s. 20(1)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), s. 20(5), Sch. 8 Pt. 2(4), Note
243 Set-off of loss brought forward, or terminal loss.U.K.
F682. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F682Ss. 242-244 repealed (with effect in accordance with s. 20(1)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), s. 20(5), Sch. 8 Pt. 2(4), Note
244 Further provisions relating to claims under section 242 or 243.U.K.
F683. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F683Ss. 242-244 repealed (with effect in accordance with s. 20(1)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), s. 20(5), Sch. 8 Pt. 2(4), Note
245 Calculation etc. of ACT on change of ownership of company.U.K.
F684. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F684S. 245 repealed (with effect in accordance with Sch. 3 para. 15(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 15(1), Sch. 27 Pt. 3(2), Note
[F685245A Restriction on application of section 240 in certain circumstances.U.K.
F686. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F685Ss. 245A, 245B inserted (in relation to changes in ownership on or after 14 March 1989) by Finance Act 1989 (c. 26), s. 98
F686S. 245A repealed (with effect in accordance with Sch. 3 para. 16(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 16(1), Sch. 27 Pt. 3(2), Note
245B Restriction on set-off where asset transferred after change in ownership of company.U.K.
F687. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F687S. 245B repealed (with effect in accordance with Sch. 3 para. 17(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 17(1), Sch. 27 Pt. 3(2), Note
246 Charge of ACT at previous rate until new rate fixed, and changes of rate.U.K.
F688. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F688S. 246 repealed (with effect in accordance with Sch. 3 para. 18(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 18(1), Sch. 27 Pt. 3(2), Note
[F689F690Chapter VAU.K. Foreign Income Dividends
Textual Amendments
F689Pt. 6 Ch. 5A (ss. 246A-246Y) inserted (3.5.1994) by Finance Act 1994 (c. 9), Sch. 16 para. 1
F690Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Election by company paying dividendU.K.
246A Election by company paying dividend.U.K.
F691. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F691Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246B Procedure for making election.U.K.
F692. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F692Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Recipient of foreign income dividendU.K.
246C No tax credit for recipient.U.K.
F693. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F693Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246D Individuals etc.U.K.
F694. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F694Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Companies: payments and receiptsU.K.
246E Foreign income dividend not franked payment.U.K.
F695. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F695Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246F Calculation of ACT where company receives foreign income dividend.U.K.
F696. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F696Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246G Information relating to foreign income dividends.U.K.
F697. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F697Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246H Power of inspector to require information.U.K.
F698. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F698Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Foreign source profit and distributable foreign profitU.K.
246I Foreign source profit and distributable foreign profit.U.K.
F699. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F699Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Matching of dividend with distributable foreign profitU.K.
246J Matching of dividend with distributable foreign profit.U.K.
F700. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F700Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246K Matching: subsidiaries.U.K.
F701. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F701Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246L Requirement as to subsidiaries.U.K.
F702. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F702Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246M Matching: further provisions.U.K.
F703. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F703Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Repayment or set-off of advance corporation taxU.K.
246N ACT to be repaid or set off against corporation tax liability.U.K.
F704. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F704Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246P Notional foreign source advance corporation tax.U.K.
F705. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F705Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246Q Repayment or set-off: supplementary.U.K.
F706. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F706Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246R Supplementary claims.U.K.
F707. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F707Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
International headquarters companiesU.K.
246S International headquarters companies.U.K.
F708. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F708Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246T Liability to pay ACT displaced.U.K.
F709. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F709Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246U Settlement of liability by IHC as to ACT.U.K.
F710. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F710Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246V Settlement of liability by non-IHC as to ACT.U.K.
F711. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F711Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
246W Payments and repayments where further matching takes place.U.K.
F712. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F712Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
AdjustmentsU.K.
246X Adjustments where profits or foreign tax altered.U.K.
F713. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F713Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
Application of this ChapterU.K.
246Y Application of this Chapter.U.K.
F714. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F714Ss. 246A-246Y (Pt. 6 Ch. 5A) repealed (with effect in accordance with Sch. 6 para. 3(2)-(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 3(1), Sch. 8 Pt. 2(11), Note
[F715CHAPTER VIU.K. MISCELLANEOUS AND SUPPLEMENTAL]
Textual Amendments
F715Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
Group incomeU.K.
247 Dividends etc. paid by one member of a group to another.U.K.
F716. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F716S. 247 repealed (with application in accordance with s. 85(6), Sch. 33 Pt. 2(10) Note of the repealing Act) by Finance Act 2001 (c. 9), s. 85(5), Sch. 33 Pt. 2(10)
248 Provisions supplementary to section 247.U.K.
F717. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F717S. 248 repealed (with application in accordance with s. 85(6), Sch. 33 Pt. 2(10) Note of the repealing Act) by Finance Act 2001 (c. 9), s. 85(5), Sch. 33 Pt. 2(10)
Stock dividendsU.K.
249 Stock dividends treated as income.U.K.
F718. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F718Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
250 Returns.U.K.
F719. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F719Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
251 Interpretation of sections 249 and 250.U.K.
F720. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F720Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
[F721Approved share incentive plansU.K.
Textual Amendments
F721Ss. 251A-251D and preceding cross-heading inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 34 (with Sch. 7)
251AApplication of sections 251B and 251CU.K.
F722. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F722Ss. 251A-251D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 122, Sch. 3 (with Sch. 2)
251BTreatment of cash dividend retained and then later paid outU.K.
F723. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F723Ss. 251A-251D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 122, Sch. 3 (with Sch. 2)
251CCharge on dividend shares ceasing to be subject to planU.K.
F724. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F724Ss. 251A-251D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 122, Sch. 3 (with Sch. 2)
251DInterpretation of sections 251A to 251CU.K.
F725. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F725Ss. 251A-251D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 122, Sch. 3 (with Sch. 2)
SupplementalU.K.
252 Rectification of excessive set-off etc. of ACT or tax credit.U.K.
F726. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F726Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
253 Power to modify or replace section 234(5) to (9) and Schedule 13.U.K.
F727. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F727Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
254 Interpretation of Part VI.U.K.
F728. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F728Pt. 6 Ch. 6 (ss. 249-254) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 22, Sch. 3 Pt. 1 (with Sch. 2)
255“Gross rate” and “gross amount” of distributions to include ACT.U.K.
F729. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F729S. 255 repealed (with effect in accordance with Sch. 3 para. 23(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 23(1), Sch. 27 Pt. 3(2), Note
PART VIIU.K. GENERAL PROVISIONS RELATING TO TAXATION OF INCOME OF INDIVIDUALS
CHAPTER IU.K. PERSONAL RELIEFS
The reliefsU.K.
256 General.U.K.
F730. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F730S. 256 omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(a)
[F731256AMeaning of “adjusted net income”U.K.
F732. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F731Ss. 256A, 256B inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 28 (with Sch. 2)
F732S. 256A omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(b)
256BMeaning of “the minimum amount”U.K.
F733. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F731Ss. 256A, 256B inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 28 (with Sch. 2)
F733S. 256B omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(c)
257 Personal allowance.U.K.
F734. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F734S. 257 omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(d)
[F735257AA Children’s tax credit.U.K.
F736. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F735S. 257AA inserted (with effect in accordance with s. 30(5) of the amending Act) by Finance Act 1999 (c. 16), s. 30(1)
F736S. 257AA repealed (6.4.2003) by Tax Credits Act 2002 (c. 21), s. 61, Sch. 6; S.I. 2003/962, art. 2(3)(e), Sch. 1 (with arts. 3, 5)
257A Married couple’s allowance[F737(pre-5th December 2005 marriages)].U.K.
F738. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F737Words in s. 257A heading inserted (5.12.2005 with effect in accordance with reg. 1(4) of the amending S.I.) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 51(5)
F738Ss. 257A-257BB omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(e)
[F739257ABMarried couple's allowance (post-5th December 2005 marriages and civil partnerships etc.)U.K.
F740. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F739S. 257AB inserted (5.12.2005 with effect in accordance with reg. 1(4) of the amending S.I.) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 52
F740Ss. 257A-257BB omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(e)
[F741257BA Elections as to transfer of relief under section 257A [F742or 257AB].U.K.
F743. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F741Ss. 257BA, 257BB substituted for s. 257B (16.7.1992 with application in relation to tax for the year 1993-94 and subsequent years of assessment) by Finance (No. 2) Act 1992 (c. 48), s. 20, Sch. 5 paras.2, 10.
F742Words in s. 257BA heading inserted (5.12.2005 with effect in accordance with reg. 1(4) of the amending S.I.) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 53(9)
F743Ss. 257A-257BB omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(e)
F745257BB Transfer of relief under section 257A where relief exceeds income[F744 or 257AB.]U.K.
F746. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F744Words in s. 257BB heading inserted (5.12.2005 with effect in accordance with reg. 1(4) of the amending S.I.) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 54(6)
F745Ss. 257BA, 257BB substituted for s. 257B (16.7.1992 with application in relation to tax for the year 1993-94 and subsequent years of assessment) by Finance (No. 2) Act 1992 (c. 48), s. 20, Sch. 5 paras.2, 10.
F746Ss. 257A-257BB omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(e)
F747257B. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
257C Indexation of amounts in [F751sections 256B, 257][F752, 257A and 257AB].U.K.
F753. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F751Words in s. 257C sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 34(3) (with Sch. 2)
F752Words in s. 257C sidenote substituted (5.12.2005 with effect in accordance with reg. 1(4) of the amending S.I.) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 55(d)
F753S. 257C omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(f)
257D Transitional relief: husband with excess allowances.U.K.
F754. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F754Ss. 257D-257F repealed (with effect in accordance with s. 32(4), Sch. 20 Pt. 3(3) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 32(2), Sch. 20 Pt. 3(3)
257E Transitional relief: the elderly.U.K.
F755. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F755Ss. 257D-257F repealed (with effect in accordance with s. 32(4), Sch. 20 Pt. 3(3) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 32(2), Sch. 20 Pt. 3(3)
257F Transitional relief: separated couples.U.K.
F756. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F756Ss. 257D-257F repealed (with effect in accordance with s. 32(4), Sch. 20 Pt. 3(3) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 32(2), Sch. 20 Pt. 3(3)
F757258 Widower’s or widow’s housekeeper.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F757S. 258 repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 25(3), Sch.14 Part IV
259 Additional relief in respect of children.U.K.
F758. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F758Ss. 259-261A repealed (with effect in accordance with s. 33(2), Sch. 20 Pt. 3(4) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 33(1), Sch. 20 Pt. 3(4)
260 Apportionment of relief under section 259.U.K.
F759. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F759Ss. 259-261A repealed (with effect in accordance with s. 33(2), Sch. 20 Pt. 3(4) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 33(1), Sch. 20 Pt. 3(4)
261 Claims under section 259 for year of marriage.U.K.
F760. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F760Ss. 259-261A repealed (with effect in accordance with s. 33(2), Sch. 20 Pt. 3(4) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 33(1), Sch. 20 Pt. 3(4)
[F761261A Additional relief in respect of children for year of separation.U.K.
F762. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F761S. 261A inserted (16.7.1992 with application in relation to tax for the year 1993-94 and subsequent years of assessment) by Finance (No. 2) Act 1992 (c. 48), s. 20, Sch. 5 paras.6, 10.
F762Ss. 259-261A repealed (with effect in accordance with s. 33(2), Sch. 20 Pt. 3(4) Note of the repealing Act) by Finance Act 1999 (c. 16), s. 33(1), Sch. 20 Pt. 3(4)
262 Widow’s bereavement allowance.U.K.
F763. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F763S. 262 repealed (with effect in accordance with s. 34(2), Sch. 20 Pt. 3(5) Note 1 of the repealing Act) by Finance Act 1999 (c. 16), s. 34(1), Sch. 20 Pt. 3(5) (with s. 34(3))
F764263 Dependent relatives.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F764S. 263 repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 25(3), Sch.14 Part IV
F765264 Claimant depending on services of a son or daughter.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F765S. 264 repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 25(3), Sch.14 Part IV
265 Blind person’s allowance.U.K.
F766. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F766S. 265 omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(g)
266 Life assurance premiums.U.K.
(1)M27Subject to the provisions of this section, [F767section 274 and Schedules 14 and 15 and sections 192 to 194 of the Finance Act 2004,] an [F768eligible individual] who pays any such premium as is specified in subsection (2) below F769. . . shall (without making any claim) be entitled to relief under this section.
[F770(1A)For the purposes of subsection (1) above an individual is an eligible individual if the individual—
(a)is resident in the United Kingdom, or
(b)meets the conditions in section 56(3) of ITA 2007.]
(2)M28The premiums referred to in subsection (1) above are any premiums paid by an individual under a policy of insurance or contract for a deferred annuity, where—
(a)the payments are made to —
[F771(i)a person who has permission under [F772Part 4A] of the Financial Services and Markets Act 2000 or under paragraph 15 of Schedule 3 to that Act (as a result of qualifying for authorisation under paragraph 12(1) of that Schedule) to effect or carry out contracts of long-term insurance; or
(ii)a member of the Society who effects or carries out contracts of long-term insurance in accordance with Part 19 of the Financial Services and Markets Act 2000;]
(iv)in the case of a deferred annuity, the National Debt Commissioners; and
(b)the insurance or, as the case may be, the deferred annuity is on the life of the individual or on the life of his spouse [F773or civil partner]; and
(c)the insurance or contract was made by him or his spouse [F773or civil partner].
(3)Subject to subsections F774. . . (10) and (11) below, no relief under this section shall be given—
(a)M29except in respect of premiums payable under policies for securing a capital sum on death, whether in conjunction with any other benefit or not;
(b)M30in respect of premiums payable under any policy issued in respect of an insurance made after 19th March 1968 unless the policy is a qualifying policy;
(c)M31in respect of premiums payable under any policy issued in respect of an insurance made after 13th March 1984 F775. . . ;
(d)M32in respect of premiums payable during the period of deferment in respect of a policy of deferred assurance.
(4)M33Subject to [F776subsection] (8) below, relief under this section in respect of any premiums paid by an individual in a year of assessment shall be given by making good to the person to whom they are paid any deficiency arising from the deductions authorised under subsection (5) below; and this section and Schedule 14 shall have effect in relation to any premium or part of a premium which is paid otherwise than in the year of assessment in which it becomes due and payable as if it were paid in that year.
(5)Subject to the provisions of Schedule 14—
(a)an individual resident in the United Kingdom who is entitled to relief under this section in respect of any premium may deduct from any payment in respect of the premium and retain an amount equal to [F77712.5 per cent] of the payment; and
(b)the person to whom the payment is made shall accept the amount paid after the deduction in discharge of the individual’s liability to the same extent as if the deduction had not been made and may recover the deficiency from the Board.
(6)F778. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6A)F778. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(7)F779. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(8)M34Where the individual is not resident in the United Kingdom [F780(but is entitled to relief by virtue of subsection (1A)(b))], subsection (4) above shall not apply but F781. . . the like relief shall be given to him under paragraph 6 of Schedule 14.
(9)M35Subsections (5) and (8) above shall apply in relation to an individual who is not resident in the United Kingdom but is a member of the armed forces of the Crown or the [F782spouse][F783or civil partner] of such a member as if the individual were so resident.
(10)M36Subsection (3)(b) above shall not apply—
(a)to any policy of life insurance having as its sole object the provision on an individual’s death or disability of a sum substantially the same as any amount then outstanding under a mortgage of his residence, or of any premises occupied by him for the purposes of a business, being a mortgage the principal amount secured by which is repayable by instalments payable annually or at shorter regular intervals; or
(b)to any policy of life insurance issued in connection with an approved scheme as defined in Chapter I of Part XIV.
In the application of this subsection to Scotland, for any reference to a mortgage there shall be substituted a reference to a heritable security within the meaning of the M37Conveyancing (Scotland) Act 1924 (but including a security constituted by ex facie absolute disposition or assignation).
(11)M38Subsection (3)(a) and (d) above shall not affect premiums payable—
(a)under policies or contracts made in connection with any superannuation or bona fide pension scheme for the benefit of the employees of any employer, or of persons engaged in any particular trade, profession, vocation or business, or for the benefit of the [F784spouse, [F785civil partner,] widow, widower [F786, surviving civil partner] or children or other dependants of any such employee or person,] or
(b)under policies taken out by teachers in the schools known in the year 1918 as secondary schools, pending the establishment of a superannuation or pension scheme for those teachers.
(12)Schedule 14 shall have effect for the purpose of modifying, for certain cases, and supplementing the provisions of this section.
[F787(13)In F788. . . Schedule 14, “friendly society” means the same as in the Friendly Societies Act 1992 (and includes any society that by virtue of section 96(2) of that Act is to be treated as a registered friendly society within the meaning of that Act).]
[F789(14)In subsection (2)(a)—
“contracts of long-term insurance” means contracts which fall within Part II of Schedule 1 to the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001; and
“member of the society” has the same meaning as in Lloyd’s Act 1982 M39.]
Textual Amendments
F767Words in s. 266(1) substituted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 9 (with Sch. 36)
F768Words in s. 266(1) substituted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 3(2)(a)
F769Words in s. 266(1) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 3(2)(b)
F770S. 266(1A) inserted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 3(3)
F771S. 266(2)(a)(i)(ii) substituted for s. 266(2)(a)-(iii) (1.12.2001 in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 18(2)
F772Words in s. 266(2)(a)(i) substituted (1.4.2013) by Financial Services Act 2012 (c. 21), Sch. 18 para. 58(2) (with Sch. 20); S.I. 2013/423, art. 3, Sch.
F773Words in s. 266(2)(b)(c) inserted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 57(2)
F774Word in s. 266(3) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 3(4)
F775Words in s. 266(3)(c) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 36(2), Sch. 3 Pt. 1 (with Sch. 2)
F776Words in s. 266(4) substituted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 3(5)
F777Words in s. 266(5)(a) substituted (from 6.4.1989) by Finance Act 1988 (c. 39), s. 29
F778S. 266(6)(6A) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 36(4), Sch. 3 Pt. 1 (with Sch. 2)
F779S. 266(7) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 3(6)
F780Words in s. 266(8) substituted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 3(7)
F781Words in s. 266(8) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 36(6)(c), Sch. 3 Pt. 1 (with Sch. 2)
F782Words in s. 266(9) substituted (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 35, Sch. 3 para. 9(a)
F783Words in s. 266(9) inserted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 57(3)
F784Words in s. 266(11)(a) substituted (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 35, Sch. 3 para. 9(b)
F785Words in s. 266(11)(a) inserted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 57(4)(a)
F786Words in s. 266(11)(a) inserted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 57(4)(b)
F787S. 266(13) inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 paras. 2(3); S.I. 1993/236, art.2
F788Words in s. 266(13) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 36(7), Sch. 3 Pt. 1 (with Sch. 2)
F789S. 266(14) added (1.12.2001 in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 18(3)
Modifications etc. (not altering text)
C29S. 266 relief abolished and s. 266 restricted by Finance Act 2012 (c. 14), Sch 39 para. 23
Marginal Citations
M27Source-1970 s.19(1); 1976 Sch.4 3(1)
M28Source-1970 s.19(2); 1976 s.36(5), Sch.4 3(2)
M29Source-1970 s.19(3)(a)
M30Source-1970 s.19(4)
M31Source-1984 s.72(1)
M32Source-1970 s.19(3)(b)
M33Source-1976 Sch.4 4(1) 5; 1978 Sch.3 2; 1980 s.29(2)(b)
M34Source-1976 Sch.4 4(2)
M35Source-1976 Sch.4 5A; 1978 Sch.3 5
M36Source-1970 s.19(4)(a), (c); 1971 Sch.3 11
M38Source-1970 s.19(3)(i)(ii)
[F790266ALife assurance premiums paid by employerU.K.
(1)This section applies if—
(a)pursuant to [F791an employer-financed] retirement benefits scheme, the employer in any year of assessment pays a sum with a view to the provision of any relevant benefits for or in respect of any employee of that employer, and
(b)the payment is made under such an insurance or contract as is mentioned in section 266.
This section applies whether or not the accrual of the relevant benefits is dependent on any contingency.
(2)Relief, if not otherwise allowable, shall be given to that employee under section 266 in respect of the payment to the extent, if any, to which such relief would have been allowable to him if—
(a)the payment had been made by him, and
(b)the insurance or contract under which the payment is made had been made with him.
[F792(3)For the purposes of subsection (1)(a) benefits are provided in respect of an employee if they are provided for the employee’s spouse, widow or widower, children, dependants or personal representatives.
(4)If a sum within subsection (1) is paid with a view to the provision of benefits for or in respect of more than one employee of the employer, part of it is to be treated as paid for or in respect of each of them.
(5)The amount treated as paid for or in respect of each employee is—

where—
A is the sum paid,
B is the amount which would have had to be paid to secure the benefits to be provided for or in respect of the employee in question, and
C is the total amount which would have had to be paid to secure the benefits to be provided for or in respect of all the employees if separate payments had been made in the case of each of them.
(6)This section does not apply if—
(a)in the year of assessment in which the sum is paid the earnings from the employee’s employment are (or, if there are none, would be if there were any) earnings charged on remittance, or
(b)the employee is not domiciled in the United Kingdom in the tax year in which the sum is paid and the conditions in subsection (7) are met.
(7)Those conditions are—
(a)that the employment is with a foreign employer, and
(b)that, on a claim made by the employee, the Board are satisfied that the pension scheme corresponds to a registered pension scheme.
(8)In subsection (6)(a) “earnings charged on remittance” means earnings which are taxable earnings under—
(a)section 22 of ITEPA 2003 (chargeable overseas earnings for year when [F793remittance basis applies and employee outside section 26]), or
(b)section 26 of that Act (foreign earnings for year when [F794remittance basis applies and employee meets section 26A requirement]).
[F795(8A)Section 835BA of ITA 2007 (deemed domicile) applies for the purposes of subsection (6)(b).]
(9)In this section—
“employer-financed retirement benefits scheme”, and
“relevant benefits”,
have the same meaning as in Chapter 2 of Part 6 of ITEPA 2003 (see sections 393A and 393B of that Act).]]
Textual Amendments
F790S. 266A inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 36 (with Sch. 7)
F791Words in s. 266A(1) substituted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 10(2) (with Sch. 36)
F792S. 266A(3)-(9) substituted for s. 266A(3)-(6) (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 10(3) (with Sch. 36)
F793Words in s. 266A(8)(a) substituted (with effect in accordance with Sch. 46 para. 25 of the amending Act) by Finance Act 2013 (c. 29), Sch. 46 para. 16(a) (with Sch. 46 para. 26)
F794Words in s. 266A(8)(b) substituted (with effect in accordance with Sch. 46 para. 25 of the amending Act) by Finance Act 2013 (c. 29), Sch. 46 para. 16(b) (with Sch. 46 para. 26)
F795S. 266A(8A) inserted (with effect in accordance with Sch. 8 para 1(2) of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 8 para. 1(1)
267 Qualifying policies.U.K.
Schedule 15, Part I of which contains the basic rules for determining whether or not a policy is a qualifying policy, Part II of which makes provision for the certification etc. of policies as qualifying policies and Part III of which modifies Parts I and II in their application to certain policies issued by non-resident companies, shall have effect for the purpose of determining whether or not a policy is a qualifying policy; and, accordingly, any reference in this Act to a qualifying policy shall be construed in accordance with that Schedule.
268 Early conversion or surrender of life policies.U.K.
F796. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F796Ss. 268-272 omitted (with effect in accordance with Sch. 39 para. 31(3) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 39 para. 31(1)
269 Surrender etc. of policies after four years.U.K.
F797. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F797Ss. 268-272 omitted (with effect in accordance with Sch. 39 para. 31(3) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 39 para. 31(1)
270 Provisions supplementary to sections 268 and 269.U.K.
F798. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F798Ss. 268-272 omitted (with effect in accordance with Sch. 39 para. 31(3) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 39 para. 31(1)
271 Deemed surrender in cases of certain loans.U.K.
F799. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F799Ss. 268-272 omitted (with effect in accordance with Sch. 39 para. 31(3) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 39 para. 31(1)
272 Collection of sums payable under sections 268 and 269.U.K.
F800. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F800Ss. 268-272 omitted (with effect in accordance with Sch. 39 para. 31(3) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 39 para. 31(1)
273 Payments securing annuities.U.K.
F801. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F801S. 273 omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(h)
274 Limits on relief under [F802section 266].U.K.
(1)M40The aggregate of the premiums F803. . . in respect of which relief is given to any person under section 266 shall not exceed £1,500 in any year of assessment or one-sixth of that person’s total income, whichever is the greater.
(2)M41The aggregate of the relief given under [F804section 266] in respect of premiums F805. . . payable for securing any benefits other than capital sums on death shall not exceed the amount of the income tax calculated at [F80612.5%] on £100.
(3)F807. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)M42War insurance premiums shall not be taken into account in calculating the limits of one-sixth of total income or of £100 mentioned in this section.
In this subsection “” means any additional premium F808. . . paid in order to extend an existing life insurance policy to risks arising from war or war service abroad, and any part of any premium F808. . . paid in respect of a life insurance policy covering those risks, or either of them, which [F809is] attributable to those risks, or either of them.
Textual Amendments
F802Word in s. 274 heading substituted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 4(6)
F803Words in s. 274(1) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 4(2)
F804Words in s. 274(2) substituted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 4(3)(a)
F805Words in s. 274(2) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 4(3)(b)
F806Words in s. 274(2) substituted (with effect in accordance with Sch. 1 para. 7 of the amending Act) by Finance Act 2009 (c. 10), Sch. 1 para. 4(3)(c)
F807S. 274(3) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 4(4)
F808Words in s. 274(4) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 4(5)
F809Word in s. 274(4) substituted (with effect in accordance with s. 134(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 20 para. 20
Marginal Citations
M40Source-1970 s.21(1); 1976 Sch.4 21
M41Source-1970 s.21(3); 1975 Sch.2 6
M42Source-1970 s.21(5)
SupplementalU.K.
F810275 Meaning of “relative”.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F810S. 275 repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part IV
276 Effect on relief of charges on income.U.K.
F811. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F811S. 276 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 38, Sch. 3 Pt. 1 (with Sch. 2)
277 Partners.U.K.
F812. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F812S. 277 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
278 Non-residents.U.K.
F813. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F813S. 278 omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 2(i)
CHAPTER IIU.K. TAXATION OF INCOME OF SPOUSES[F814 AND CIVIL PARTNERS]
Textual Amendments
F814Words in Pt. 7 Ch. 2 heading inserted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 61
General rulesU.K.
F815279 Aggregation of wife’s income with husband’s.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F815S. 279 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), ss. 32, 148, Sch. 14 Part VIII
F816280 Transfer of reliefs.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F816S. 280 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
F817281 Tax repayments to wives.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F817S. 281 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
282 Construction of references to [F818spouses or civil partners] living together.U.K.
F819. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F818Words in s. 282 heading substituted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 62(b)
F819S. 282 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 41, Sch. 3 Pt. 1 (with Sch. 2)
[F820282A Jointly held property.U.K.
F821. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F820Ss. 282A, 282B inserted (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 34
F821Ss. 282A, 282B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 42, Sch. 3 Pt. 1 (with Sch. 2)
282B Jointly held property: declarations.U.K.
F822. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F822Ss. 282A, 282B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 42, Sch. 3 Pt. 1 (with Sch. 2)
Separate assessmentsU.K.
F823283 Option for separate assessment.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F823Ss. 283-288 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
F824284 Effect of separate assessment on personal reliefs.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F824Ss. 283-288 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
F825285 Collection from wife of tax assessed on husband but attributable to her income.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F825Ss. 283-288 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
F826286 Right of husband to disclaim liability for tax on deceased wife’s income.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F826Ss. 283-288 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
Separate taxationU.K.
F827287 Separate taxation of wife’s earnings.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F827Ss. 283-288 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
F828288 Elections under section 287.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F828Ss. 283-288 repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Part VIII
[F829CHAPTER IIIU.K. ENTERPRISE INVESTMENT SCHEME]
Textual Amendments
F829Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
289 Eligibility for relief.U.K.
F830. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F830Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 289(9) amended (as saved) (retrospective to 6.4.2007) by Finance Act 2007 (c. 11), Sch. 16 paras. 16(1)(a), 18; and s. 289 further amended (as saved) (17.7.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Income Tax Act 2007 (Amendment) (No. 2) Order 2007 (S.I. 2007/1820), arts. 1(1), 2(2)
[F831289A Form of relief.U.K.
F832. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F831Ss. 289-289B substituted for s. 289 (with effect in accordance with s. 137(2) of the amending Act) by Finance Act 1994 (c. 9), s. 137(1), Sch. 15 para. 2
F832Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F833289B Attribution of relief to shares.U.K.
F834. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F833Ss. 289-289B substituted for s. 289 (with effect in accordance with s. 137(2) of the amending Act) by Finance Act 1994 (c. 9), s. 137(1), Sch. 15 para. 2
F834Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
290 Minimum and maximum subscriptions.U.K.
F835. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F835Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F836F837290A Restriction of relief where amounts raised exceed permitted maximum.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F836S. 290A inserted (retrospectively) by Finance Act 1988 (c. 39) s. 51(1)(b)
F837S. 290A repealed (with effect in accordance with s. 74(3), Sch. 27 Pt. 3(14) Note 4 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 13 para. 5, Sch. 27 Pt. 3(14)
291 Individuals qualifying for relief.U.K.
F838. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F838Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F839291A Connected persons: directors.U.K.
F840. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F839Ss. 291-291B substituted for s. 291 (with effect in accordance with s. 137(2) of the amending Act) by Finance Act 1994 (c. 9), s. 137(1), Sch. 15 para. 5
F840Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F841291B Connected persons: persons interested in capital etc. of company.U.K.
F842. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F841Ss. 291-291B substituted for s. 291 (with effect in accordance with s. 137(2) of the amending Act) by Finance Act 1994 (c. 9), s. 137(1), Sch. 15 para. 5
F842Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 291B amended (as saved) (17.7.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Income Tax Act 2007 (Amendment) (No. 2) Order 2007 (S.I. 2007/1820), arts. 1(1), 2(2)
292 Parallel trades.U.K.
F843. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F843Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
293 Qualifying companies.U.K.
F844. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F844Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 293 amended (as saved) (17.7.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Income Tax Act 2007 (Amendment) (No. 2) Order 2007 (S.I. 2007/1820), arts. 1(1), 2(2)
294 Companies with interests in land.U.K.
F845. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F845Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
295 Valuation of interests in land for purposes of section 294(1)(b).U.K.
F846. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F846Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
296 Section 294 disapplied where amounts raised total £50,000 or less.U.K.
F847. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F847Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
297 Qualifying trades.U.K.
F848. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F848Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 297 amended (as saved) (retrospective to 6.4.2007) by Finance Act 2007 (c. 11), Sch. 16 paras. 11(1), 13, Sch. 27 Pt. 2(16), Note
298 Provisions supplementary to sections 293 and 297.U.K.
F849. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F849Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 298 amended (as saved) (17.7.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Income Tax Act 2007 (Amendment) (No. 2) Order 2007 (S.I. 2007/1820), arts. 1(1), 2(3)
299 Disposal of shares.U.K.
F850. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F850Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 299 (as saved) applied (with modifications) by s. 149(1)(a) of that repealing Act
[F851299A Loan linked investments.U.K.
F852. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F851S. 299A inserted (27.7.1993 with application in relation to any case in which the claim for relief is made on or after 16.3.1993) by 1993 c. 34, s. 111(1)(4)
F852Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F853299B Pre-arranged exits.U.K.
F854. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F853S. 299B inserted (with effect in accordance with s. 71(5) of the amending Act) by Finance Act 1998 (c. 36), s. 71(1)
F854Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
300 Value received from company.U.K.
F855. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F855Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F856300A Receipt of replacement valueU.K.
F857. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F856S. 300A inserted (with effect in accordance with Sch. 15 para. 40(3) of the amending Act) by Finance Act 2001 (c. 9), Sch. 15 para. 16
F857Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
301 Provisions supplementary to section 300.U.K.
F858. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F858Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F859301A Receipts of insignificant value: supplementary provisionU.K.
F860. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F859S. 301A inserted (with effect in accordance with Sch. 15 para. 40(3) of the amending Act) by Finance Act 2001 (c. 9), Sch. 15 para. 18
F860Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
302 Replacement capital.U.K.
F861. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F861Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
303 Value received by persons other than claimants.U.K.
F862. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F862Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F863303AA Insignificant repayments disregarded for purposes of s.303(1)U.K.
F864. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F863S. 303AA inserted (with effect in accordance with Sch. 15 para. 40(3) of the amending Act) by Finance Act 2001 (c. 9), Sch. 15 para. 20
F864Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F865303A Restriction on withdrawal of relief under section 303.U.K.
F866. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F865S. 303A inserted (with effect in accordance with s. 63(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 16 para. 2(3)
F866Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
304[F867Spouses and civil partners.]U.K.
F868. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F867S. 304 heading substituted (5.12.2005) by The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 65(c)
F868Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F869304A Acquisition of share capital by new company.U.K.
F870. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F869S. 304A inserted (with effect in accordance with s. 74(3), Sch. 13 para. 17(2) of the amending Act) by Finance Act 1998 (c. 36), Sch. 13 para. 17(1); and see also the s. 304A inserted (with effect in accordance with s. 74(3), Sch. 13 para. 41(2) of the amending Act) by Finance Act 1998 (c. 36), Sch. 13 paras. 37, 41(1)
F870Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 304A amended (as saved) (retrospective to 6.4.2007) by Finance Act 2007 (c. 11), Sch. 16 paras. 11(2), 13
305 Reorganisation of share capital.U.K.
F871. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F871Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
[F872305A Relief for loss on disposal of shares.U.K.
F873. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F872S. 305A inserted (with effect in accordance with s. 137(2) of the amending Act) by Finance Act 1994 (c. 9), s. 137(1), Sch. 15 para. 20
F873S. 305A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 43, Sch. 3 Pt. 1 (with Sch. 2)
306 Claims.U.K.
F874. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F874Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
307 Withdrawal of relief.U.K.
F875. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F875Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
308 Application to subsidiaries.U.K.
F876. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F876Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 308 amended (as saved) (17.7.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Income Tax Act 2007 (Amendment) (No. 2) Order 2007 (S.I. 2007/1820), arts. 1(1), 2(2)
309 Further provisions as to subsidiaries.U.K.
F877. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F877S. 309 repealed (with effect as mentioned in s. 137(1)(2), Sch. 26 Pt. 5(17) Note of the repealing Act) by Finance Act 1994 (c. 9), Sch. 15 para. 24, Sch. 26 Pt. 5(17)
310 Information.U.K.
F878. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F878Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
311 Nominees, bare trustees and approved investment funds.U.K.
F879. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F879Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2)
312 Interpretation of Chapter III.U.K.
F880. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F880Pt. 7 Ch. 3 (ss. 289-312), except s. 305A, repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 627, Sch. 3 Pt. 2 (with savings in s. 1034(3), Sch. 2); and s. 312 amended (as saved) (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 44 (with Sch. 2); and s. 312 further amended (as saved) (retrospective to 6.4.2007) by Finance Act 2007 (c. 11), Sch. 16 paras. 16(1)(b), 18, Sch. 27 Pt. 2(16), Note; and s. 312 further amended (as saved) (17.7.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Income Tax Act 2007 (Amendment) (No. 2) Order 2007 (S.I. 2007/1820), arts. 1(1), 2(4)(5); and s. 312 further amended (as saved) (19.7.2007) by Finance Act 2007 (c. 11), Sch. 26 para. 7(3)
CHAPTER IVU.K. SPECIAL PROVISIONS
313 Taxation of consideration for certain restrictive undertakings.U.K.
F881. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F881S. 313 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 39, Sch. 8 Pt. 1(with Sch. 7)
314 Divers and diving supervisors.U.K.
F882. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F882S. 314 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 128, Sch. 3 (with Sch. 2)
315 Wounds and disability pensions.U.K.
F883. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F883Ss. 315-318 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 41, Sch. 8 Pt. 1 (with Sch. 7)
316 Allowances, bounties and gratuities.U.K.
F884. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F884Ss. 315-318 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 41, Sch. 8 Pt. 1 (with Sch. 7)
317 Victoria Cross and other awards.U.K.
F885. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F885Ss. 315-318 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 41, Sch. 8 Pt. 1 (with Sch. 7)
318 Other pensions in respect of death due to war service etc.U.K.
F886. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F886Ss. 315-318 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 41, Sch. 8 Pt. 1 (with Sch. 7)
319 Crown servants: foreign service allowance.U.K.
F887. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F887S. 319 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 42, Sch. 8 Pt. 1 (with Sch. 7)
320 Commonwealth Agents-General and official agents etc.U.K.
F888. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F888S. 320 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 45, Sch. 3 Pt. 1 (with Sch. 2)
321 Consuls and other official agents.U.K.
F889. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F889S. 321 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 43, Sch. 8 Pt. 1 (with Sch. 7)
322 Consular officers and employees.U.K.
F890. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F890S. 322 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 129, Sch. 3 (with Sch. 2)
323 Visiting forces.U.K.
F891. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F891S. 323 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 46, Sch. 3 Pt. 1 (with Sch. 2)
324 Designated international organisations.U.K.
F892. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F892S. 324 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 130, Sch. 3 (with Sch. 2)
325 Interest on deposits with National Savings Bank.U.K.
F893. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F893S. 325 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 131, Sch. 3 (with Sch. 2)
326 Interest etc. under contractual savings schemes.U.K.
F894. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F894S. 326 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 132, Sch. 3 (with Sch. 2)
[F895326A Tax-exempt special savings accounts.U.K.
F896. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F895Ss. 326A-326C inserted by Finance Act 1990 (c. 29), s. 28(1)
F896Ss. 326A-326D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 133, Sch. 3 (with Sch. 2)
[F897326B Loss of exemption for special savings accounts.U.K.
F898. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F897Ss. 326A-326C inserted by Finance Act 1990 (c. 29), s. 28(1)
F898Ss. 326A-326D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 133, Sch. 3 (with Sch. 2)
[F899326BB Follow-up TESSAs.U.K.
F900. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F899S. 326BB inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 62(2)
F900Ss. 326A-326D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 133, Sch. 3 (with Sch. 2)
[F901326C Tax-exempt special savings accounts: supplementary.U.K.
F902. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F901Ss. 326A-326C inserted by Finance Act 1990 (c. 29), s. 28(1)
F902Ss. 326A-326D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 133, Sch. 3 (with Sch. 2)
[F903326D Tax-exempt special savings accounts: tax representatives.U.K.
F904. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F903S. 326D inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 63(4)
F904Ss. 326A-326D repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 133, Sch. 3 (with Sch. 2)
327 Disabled person’s vehicle maintenance grant.U.K.
F905. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F905S. 327 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 134, Sch. 3 (with Sch. 2)
[F906327APayments to adoptersU.K.
F907. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F906S. 327A inserted (with effect in accordance with s. 175(2) of the amending Act) by Finance Act 2003 (c. 14), s. 175(1)
F907S. 327A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 135, Sch. 3 (with Sch. 2)
F908328 Funds in court.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F908S. 328 repealed (with effect in accordance with s. 68(3)-(5) of the repealing Act) by Finance Act 1999 (c. 16), s. 68(2), Sch. 20 Pt. 3(17), Note
329 Interest on damages for personal injuries.U.K.
F909. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F909Ss. 329-329AB repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 136, Sch. 3 (with Sch. 2)
[F910329AA Personal injury damages in the form of periodical payments.U.K.
F911. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F910Ss. 329AA, 329AB inserted (with effect in accordance with s. 150(2)-(4) of the amending Act) by Finance Act 1996 (c. 8), s. 150(1), Sch. 26
F911Ss. 329-329AB repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 136, Sch. 3 (with Sch. 2)
329AB Compensation for personal injury under statutory or other schemes.U.K.
F912. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F910Ss. 329AA, 329AB inserted (with effect in accordance with s. 150(2)-(4) of the amending Act) by Finance Act 1996 (c. 8), s. 150(1), Sch. 26
F912Ss. 329-329AB repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 136, Sch. 3 (with Sch. 2)
[F913F914329A Annuities purchased for certain persons.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F913Ss. 329A, 329B inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 142
F914Ss. 329A-329C repealed and superseded (29.4 1996) by Finance Act 1996 (c. 8), s. 150(2)(3), Sch. 41 Pt. 5(16) (with s. 150(4))
F915329B Annuities assigned in favour of certain persons.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F913Ss. 329A, 329B inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 142
F915Ss. 329A-329C repealed and superseded (29.4 1996) by Finance Act 1996 (c. 8), s. 150(2)(3), Sch. 41 Pt. 5(16) (with s. 150(4))
[F916F917329C Annuities: criminal injuries.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F916S. 329C inserted (8.11.1995) by Criminal Injuries Compensation Act 1995 (c. 53), s. 8
F917Ss. 329A-329C repealed and superseded (29.4 1996) by Finance Act 1996 (c. 8), s. 150(2)(3), Sch. 41 Pt. 5(16) (with s. 150(4))
330 Compensation for National-Socialist persecution.U.K.
F918. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F918S. 330 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 46, Sch. 8 Pt. 1 (with Sch. 7)
331 Scholarship income.U.K.
F919. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F919S. 331 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 137, Sch. 3 (with Sch. 2)
[F920331A Student loans: certain interest to be disregarded.U.K.
F921. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F920S. 331A inserted (27.7.1999) by Finance Act 1999 (c. 16), s. 60
F921S. 331A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 138, Sch. 3 (with Sch. 2)
332 Expenditure and houses of ministers of religion.U.K.
(1)F922. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F922. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F923. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F924(3A)F925. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3B)F925. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(4)F925. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F922S. 332(1)(2) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 47(2), Sch. 8 Pt. 1 (with Sch. 7)
F923S. 332(3) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 139, Sch. 3 (with Sch. 2)
F924S. 332(3A)(3B) inserted (with effect in accordance with s. 57(4) of the amending Act) by Finance Act 2001 (c. 9), Sch. 12 para. 10
F925S. 332(3A)(3B)(4) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 47(4), Sch. 8 Pt. 1 (with Sch. 7)
[F926332A Venture capital trusts: relief.U.K.
F927. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F926S. 332A inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 71(1)
F927S. 332A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 47, Sch. 3 Pt. 1 (with Sch. 2)
[F928333Investment plan regulationsU.K.
Regulations under Chapter 3 of Part 6 of ITTOIA 2005 (income from individual investment plans) may include provision generally for the purpose of the administration of corporation tax in relation to plans.]
Textual Amendments
F928S. 333 substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 141 (with Sch. 2)
[F929333A Personal equity plans: tax representatives.U.K.
F930. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F929S. 333A inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 64(1)
F930S. 333A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 142, Sch. 3 (with Sch. 2)
[F931333B Involvement of insurance companies with plans and accounts.U.K.
F932. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F931S. 333B inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 77(1)
F932S. 333B repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 4, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
CHAPTER VU.K. RESIDENCE OF INDIVIDUALS
334 Commonwealth citizens and others temporarily abroad.U.K.
F933. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F933S. 334 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 48, Sch. 3 Pt. 1 (with Sch. 2)
335 Residence of persons working abroad.U.K.
F934. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F934S. 335 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 49, Sch. 3 Pt. 1 (with Sch. 2)
336 Temporary residents in the United Kingdom.U.K.
F935. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F935S. 336 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 50, Sch. 3 Pt. 1 (with Sch. 2)
PART VIIIU.K. TAXATION OF INCOME AND CHARGEABLE GAINS OF COMPANIES
Taxation of incomeU.K.
337 Company beginning or ceasing to carry on tradeU.K.
F936. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F936S. 337 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 103, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F937[F938337A Computation of company’s profits or income: exclusion of general deductionsU.K.
(1)F939. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F940. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F937Ss. 337, 337A substituted (24.7.2002) by Finance Act 2002 (c. 23), Sch. 30 para. 1(1)
F938S. 337A inserted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 15 (with Sch. 15)
F939S. 337A(1) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 23, Sch. 3 Pt. 1 (with Sch. 2)
F940S. 337A(2) repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 37, Sch. 10 Pt. 12 (with Sch. 9)
338 Charges on income deducted from total profitsU.K.
F941. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F941S. 338 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 24, Sch. 3 Pt. 1 (with Sch. 2)
[F942338A Meaning of “charges on income"U.K.
F943. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F942Ss. 338-338B substituted for s. 338 (24.7.2002) by Finance Act 2002 (c. 23), Sch. 30 para. 1(2)
F943S. 338A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 25, Sch. 3 Pt. 1 (with Sch. 2)
[F944338B Charges on income: annuities or other annual paymentsU.K.
F945. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F944Ss. 338-338B substituted for s. 338 (24.7.2002) by Finance Act 2002 (c. 23), Sch. 30 para. 1(2)
F945S. 338B repealed (with effect in accordance with s. 38(7) of the repealing Act) by Finance (No. 2) Act 2005 (c. 22), Sch. 11 Pt. 2(7), Note
339 Charges on income: donations to charity.U.K.
F946. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F946S. 339 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 26, Sch. 3 Pt. 1 (with Sch. 2); and s. 339 amended (1.4.2010 with effect in accordance with art. 5(2) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2010 (S.I. 2010/157), arts. 1, 5(1)
[F947F948339A. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F947S. 339A inserted (in relation to accounting periods ending on or after 1 October 1990) by Finance Act 1990 (c. 29), s. 27(3)(4)
F948S. 339A repealed (in relation to accounting periods beginning on or after 19.3.1991) by Finance Act 1991 (c. 31), ss. 71(1)(3), 123, Sch. 19 Pt. V, Note 5; and s. 339A modified in its application to accounting periods beginning before 19.3.1991 and ending on or after that date by s. 71(4) of that repealing Act
F949340 Charges on income: interest payable to non-residents.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F949S. 340 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 14 para. 17, Sch. 41 Pt. 5(3), Note (with Sch. 15)
F950341 Payments of interest etc. between related companies.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F950S. 341 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 14 para. 17, Sch. 41 Pt. 5(3), Note (with Sch. 15)
342 Tax on company in liquidation.U.K.
F951. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F951S. 342 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 27, Sch. 3 Pt. 1 (with Sch. 2)
[F952342ATax on companies in administrationU.K.
F953. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F952S. 342A inserted (with effect in accordance with Sch. 41 para. 5(1) of the amending Act) by Finance Act 2003 (c. 14), Sch. 41 para. 3
F953S. 342A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 28, Sch. 3 Pt. 1 (with Sch. 2)
343 Company reconstructions without a change of ownership.U.K.
F954. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F954S. 343 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 29, Sch. 3 Pt. 1 (with Sch. 2)
[F955343ZATransfers of trade to obtain balancing allowancesU.K.
F956. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F955S. 343ZA inserted (with effect in accordance with s. 89(2) of the amending Act) by Finance Act 2008 (c. 9), s. 89(1)
F956S. 343ZA repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 30, Sch. 3 Pt. 1 (with Sch. 2)
[F957343ACompany reconstructions involving business of leasing plant or machineryU.K.
F958. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F957S. 343A inserted (19.7.2007, the inserted subsections (2) and (3) having effect in accordance with Sch. 6 para. 1(3)-(5) of the amending Act) by Finance Act 2007 (c. 11), Sch. 6 para. 1(2)
F958S. 343A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 31, Sch. 3 Pt. 1 (with Sch. 2)
344 Company reconstructions: supplemental.U.K.
F959. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F959S. 344 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 32, Sch. 3 Pt. 1 (with Sch. 2)
Chargeable gainsU.K.
F960345. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F960S. 345 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch.12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 20, 22, 26(2), 27).
F961346. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F961S. 346 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch.12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 20, 22, 26(2), 27).
F962347. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F962S. 347 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch.12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 20, 22, 26(2), 27).
PART IXU.K. ANNUAL PAYMENTS AND INTEREST
Annual paymentsU.K.
[F963347A General rule.U.K.
F964. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F963Ss. 347A, 347B inserted by Finance Act 1988 (c. 39), s. 36(1)(3)-(5)
F964S. 347A repealed (with effect in accordance with Sch. 5 para. 1(3)(5) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 5 para. 1(2)(4), Sch. 27 Pt. 2(3), Note
[F965347B Qualifying maintenance payments.U.K.
F966. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F965Ss. 347A, 347B inserted by Finance Act 1988 (c. 39), s. 36(1)(3)-(5)
F966S. 347B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 53, Sch. 3 Pt. 1 (with Sch. 2)
348 Payments out of profits or gains brought into charge to income tax: deduction of tax.U.K.
F967. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F967S. 348 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 54, Sch. 3 Pt. 1 (with Sch. 2); and s. 348 amended (6.4.2007) by Finance Act 2005 (c. 7), Sch. 10 paras. 62, 64(2), Sch. 11 Pt. 4, Note 1
349 Payments not out of profits or gains brought into charge to income tax, and annual interest.U.K.
F968. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F968S. 349 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 55, Sch. 3 Pt. 1 (with Sch. 2); and s. 349 amended (6.4.2007) by Finance Act 2005 (c. 7), Sch. 10 paras. 62, 64(2), Sch. 11 Pt. 4, Note 1
[F969349ZAExtension of section 349: proceeds of sale of UK patent rightsU.K.
F970. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F969S. 349ZA inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 149 (with Sch. 2)
F970S. 349ZA repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 56, Sch. 3 Pt. 1 (with Sch. 2)
[F971349A Exceptions to section 349 for payments between companies etcU.K.
F972. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F971Ss. 349A-349D inserted (with application in accordance with s. 85(4) of the amending Act) by Finance Act 2001 (c. 9), s. 85(1)
F972Ss. 349A-349D repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 57, Sch. 3 Pt. 1 (with Sch. 2)
349B The conditions mentioned in section 349A(1)U.K.
F973. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F971Ss. 349A-349D inserted (with application in accordance with s. 85(4) of the amending Act) by Finance Act 2001 (c. 9), s. 85(1)
F973Ss. 349A-349D repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 57, Sch. 3 Pt. 1 (with Sch. 2)
349C Directions disapplying section 349A(1)U.K.
F974. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F971Ss. 349A-349D inserted (with application in accordance with s. 85(4) of the amending Act) by Finance Act 2001 (c. 9), s. 85(1)
F974Ss. 349A-349D repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 57, Sch. 3 Pt. 1 (with Sch. 2)
349D Section 349A(1): consequences of reasonable but incorrect beliefU.K.
F975. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F971Ss. 349A-349D inserted (with application in accordance with s. 85(4) of the amending Act) by Finance Act 2001 (c. 9), s. 85(1)
F975Ss. 349A-349D repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 57, Sch. 3 Pt. 1 (with Sch. 2)
[F976349E Deductions under section 349(1): payment of royalties overseasU.K.
F977. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F976S. 349E inserted (with application in accordance with s. 96(4) of the amending Act) by Finance Act 2002 (c. 23), s. 96(1)
F977S. 349E repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 58, Sch. 3 Pt. 1 (with Sch. 2)
350 Charge to tax where payments made under section 349.U.K.
F978. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F978S. 350 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 59, Sch. 3 Pt. 1 (with Sch. 2)
[F979350A UK public revenue dividends: deduction of tax.U.K.
F980. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F979S. 350A inserted (with application in accordance with s. 112(5) of the amending Act) by Finance Act 2000 (c. 17), s. 112(4)
F980S. 350A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 60, Sch. 3 Pt. 1 (with Sch. 2)
F981351 Small maintenance payments.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F981S. 351 repealed by Finance Act 1988 (c. 39) s. 36(6), Sch.14 Part IV, Note 5 (with s. 36(3))
352 Certificates of deduction of tax.U.K.
F982. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F982S. 352 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 61, Sch. 3 Pt. 1 (with Sch. 2)
Relief for payments of interest (excluding MIRAS)U.K.
353 General provision.U.K.
[F983(1)Where a person pays interest in any year of assessment, that person, if he makes a claim to the relief, shall for that year of assessment be entitled (subject to F984. . . [F985section 52 of ITTOIA 2005]) to relief in accordance with this section in respect of so much (if any) of the amount of that interest as is eligible for relief under this section by virtue of [F986section 365].]
[F987[F988(1A)Where a person is entitled for a year of assessment to relief under this section in respect of an amount of interest which is eligible for relief by virtue of section 365, the relief is given as a tax reduction for that tax year.
(1AA)The amount of the tax reduction is 23% of the amount of the interest.
(1AB)The tax reduction is given effect at Step 6 of the calculation in section 23 of ITA 2007.]
(1B)F989. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(1C)F990. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(1D)F990. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(1E)Where any person is entitled for any year of assessment to relief F991. . . in respect of any amount of interest as is eligible for that relief partly as mentioned in subsection (1A) above and partly as mentioned in [F992section 383 of ITA 2007 (relief for interest payments)], that amount of interest shall be apportioned between the cases to which each of [F993those provisions] applies without regard to what parts of the total amount borrowed remain outstanding but according to F994. . . —
(a)the proportions of the total amount borrowed which were applied for different purposes; F995. . .
(b)F995. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F996and subsection (1A) above or section 383 of ITA 2007 shall apply accordingly to the case in which that subsection or section applies].
(1F)F997. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(1G)F997. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(1H)F997. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(2)M43This section does not apply to a payment of relevant loan interest to which section 369 applies.
(3)M44Relief under this section shall not be given in respect of—
(a)interest on a debt incurred by overdrawing an account or by debiting the account of any person as the holder of a credit card or under similar arrangements; or
(b)where interest is paid at a rate in excess of a reasonable commercial rate, so much of the interest as represents the excess.
(4)F998. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F998. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F983S. 353(1) substituted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), s. 81(1)
F984Words in s. 353(1) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(2)(a), Sch. 3 Pt. 1 (with Sch. 2)
F985Words in s. 353(1) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 152 (with Sch. 2)
F986Words in s. 353(1) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(2)(b) (with Sch. 2)
F987S. 353(1A)-(1H) inserted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), s. 81(2)
F988S. 353(1A)-(1AB) substituted for s. 353(1A) (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(3) (with Sch. 2)
F989S. 353(1B) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(4), Sch. 3 Pt. 1 (with Sch. 2)
F990S. 353(1C)(1D) repealed (with effect in accordance with s. 42(3)-(5) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(2), Note
F991Words in s. 353(1E) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(5)(a), Sch. 3 Pt. 1 (with Sch. 2)
F992Words in s. 353(1E) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(5)(b) (with Sch. 2)
F993Words in s. 353(1E) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(5)(c) (with Sch. 2)
F994Words in s. 353(1E) repealed (with effect in accordance with s. 42(3)-(5) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(2), Note
F995S. 353(1E)(b) and preceding word repealed (with effect in accordance with s. 42(3)-(5) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(2), Note
F996Words in s. 353(1E) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(5)(d) (with Sch. 2)
F997S. 353(1F)-(1H) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 62(6), Sch. 3 Pt. 1 (with Sch. 2)
F998S. 353(4)(5) repealed (with effect in accordance with s. 81(6) of the repealing Act) by Finance Act 1994 (c. 9), Sch. 9 para. 3, Sch. 26 Pt. 5(2), Note
Modifications etc. (not altering text)
C30S. 353 restricted (1.5.1995) by Finance Act 1995 (c. 4), s. 123, Sch. 22 para. 2
C31S. 353 restricted (27.7.1999) by Finance Act 1999 (c. 16), s. 38(1)
Marginal Citations
M43Source-1986 s.26(1)
M44Source-1972 s.75(1A), (2); 1974 s.19(1)(b)
354 Loans to buy land etc.U.K.
F999. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F999Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
355 Matters excluded from section 354.U.K.
F1000. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1000Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
356 Job-related accommodation.U.K.
F1001. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1001Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1002356A Limit on relief for home loans: residence basis.U.K.
F1003. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1002Ss. 356A-356D inserted (1.8.1988) by Finance Act 1988 (c. 39), s.42(1)(4)
F1003Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1004356B Residence basis: married couples.U.K.
F1005. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1004Ss. 356A-356D inserted (1.8.1988) by Finance Act 1988 (c. 39), s. 42(1)(4); and s. 356B substituted (1990-91 and subsequent years) by Finance Act 1988 (c. 39), Sch. 3 para. 14
F1005Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1006356C Payments to which sections 356A and 356B apply.U.K.
F1007. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1006Ss. 356A-356D inserted (1.8.1988) by Finance Act 1988 (c. 39), s.42(1)(4)
F1007Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1008356D Provisions supplementary to sections 356A to 356C.U.K.
F1009. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1008Ss. 356A-356D inserted (1.8.1988) by Finance Act 1988 (c. 39), s.42(1)(4)
F1009Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
357 Limit on amount of loan eligible for relief by virtue of section 354.U.K.
F1010. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1010Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1011357A Substitution of security.U.K.
F1012. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1011Ss. 357A-357C inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 56
F1012Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1013357B Treatment of loans following security substitution.U.K.
F1014. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1013Ss. 357A-357C inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 56
F1014Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
[F1015357C Substitution of security: supplemental.U.K.
F1016. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1015Ss. 357A-357C inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 56
F1016Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
358 Relief where borrower deceased.U.K.
F1017. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1017Ss. 354-358 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 2, Sch. 20 Pt. 3(7)
359 Loan to buy machinery or plant.U.K.
F1018. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1018S. 359 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 63, Sch. 3 Pt. 1 (with Sch. 2)
360 Loan to buy interest in close company.U.K.
F1019. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1019S. 360 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 64, Sch. 3 Pt. 1 (with Sch. 2)
[F1020360A Meaning of “material interest” in section 360.U.K.
F1021. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1020S. 360A inserted by Finance Act 1989 (c. 26), s. 48(2)
F1021S. 360A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 65, Sch. 3 Pt. 1 (with Sch. 2)
361 Loan to buy interest in co-operative or employee-controlled company.U.K.
F1022. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1022S. 361 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 66, Sch. 3 Pt. 1 (with Sch. 2)
362 Loan to buy into partnership.U.K.
F1023. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1023S. 362 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 67, Sch. 3 Pt. 1 (with Sch. 2)
363 Provisions supplementary to sections 360 to 362.U.K.
F1024. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1024S. 363 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 68, Sch. 3 Pt. 1 (with Sch. 2)
364 Loan to pay inheritance tax.U.K.
F1025. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1025S. 364 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 69, Sch. 3 Pt. 1 (with Sch. 2)
365 Loan to buy life annuity.U.K.
M45(1)Subject to the following provisions of this section, interest is eligible for relief under section 353 if it is interest on a loan in respect of which the following conditions are satisfied—
[F1026(aa)that the loan was made before 9th March 1999;]
(a)that the loan was made as part of a scheme under which not less than nine-tenths of the proceeds of the loan were applied to the purchase by the person to whom it was made of an annuity ending with his life or with the life of the survivor of two or more persons (“the annuitants”) who include the person to whom the loan was made;
(b)that at the time the loan was made the person to whom it was made or each of the annuitants had attained the age of 65 years;
(c)that the loan was secured on land in the United Kingdom or the Republic of Ireland and the person to whom it was made or one of the annuitants owns an estate or interest in that land; and
(d)that, if the loan was made after 26th March 1974, the person to whom it was made or each of the annuitants [F1027used the land on which it was secured as his only or main residence immediately before 9th March 1999] .
[F1028(1AA)Where—
(a)a loan made on or after 9th March 1999 was made in pursuance of an offer made by the lender before that date, and
(b)the offer was either in writing or evidenced by a note or memorandum made by the lender before that date,
the loan shall be deemed for the purposes of subsection (1)(aa) above to have been made before that date.]
[F1029(1AB)Subject to subsection (1AC) below, the conditions in paragraphs (aa) and (a) of subsection (1) above shall be treated as satisfied in relation to a loan (“the new loan”) if—
(a)the new loan was made on or after the day on which the Finance Act 1999 was passed;
(b)the new loan was made as part of a scheme (“the scheme”) under which the whole or any part of the proceeds of the loan was used to defray money applied in paying off another loan (“the old loan”); and
(c)the conditions in subsection (1) above were, or were treated by virtue of this subsection as, satisfied with respect to the old loan.
(1AC)If only part of the proceeds of the new loan was used to defray money applied in paying off the old loan, subsection (1AB) above applies only if, under the scheme, not less than nine-tenths of the remaining part of the proceeds of the new loan was applied to the purchase by the person to whom it was made of an annuity ending with his life or with the life of the survivor of two or more persons who include him.
(1AD)In subsection (1AC) above “the remaining part” means the part of the proceeds of the new loan that was not used to defray money applied in paying off the old loan.]
[F1030[F1031(1A)The condition in subsection (1)(d) above shall be treated as satisfied in relation to a loan if—
(a)the person to whom the loan was made, or any of the annuitants, ceased to use the land as his only or main residence at a time falling within the period of twelve months ending with 8th March 1999, and
(b)the intention at that time of the person to whom the loan was made, or each of the annuitants owning an estate or interest in the land, was to take steps, before the end of the period of twelve months after the day on which the land ceased to be so used, with a view to the disposal of his estate or interest.]
(1B)If it appears to the Board reasonable to do so, having regard to all the circumstances of a particular case, they may direct that in relation to that case subsection (1A) above shall have effect as if for the reference to 12 months there were substituted a reference to such longer period as meets the circumstances of that case.]
(2)Interest is not eligible for relief by virtue of this section unless it is payable by the person to whom the loan was made or by one of the annuitants.
(3)If the loan was made after 26th March 1974 interest on it is eligible for relief by virtue of this section only to the extent that the amount on which it is payable does not exceed [F1032the sum of £30,000]; and if the interest is payable by two or more persons the interest payable by each of them is so eligible only to the extent that the amount on which it is payable does not exceed such amount as bears to [F1033that sum] the same proportion as the interest payable by him bears to the interest payable by both or all of them.
Textual Amendments
F1026S. 365(1)(aa) inserted (with effect in accordance with s. 39(3) of the amending Act) by Finance Act 1999 (c. 16), s. 39(1)
F1027Words in s. 365(1)(d) inserted (with effect in accordance with s. 40(5) of the amending Act) by Finance Act 1999 (c. 16), s. 40(2)
F1028S. 365(1AA) inserted (with effect in accordance with s. 39(3) of the amending Act) by Finance Act 1999 (c. 16), s. 39(2)
F1029S. 365(1AB)-(1AD) inserted (with effect in accordance with s. 40(5) of the amending Act) by Finance Act 1999 (c. 16), s. 40(3)
F1030S. 365(1A)(1B) inserted (27.7.1993 with effect in relation to payments of interest made on or after 16 March 1993 (whenever falling due)) by Finance Act 1993 (c. 34), s. 57(3)(5)(6)
F1031S. 365(1A) substituted (with effect in accordance with s. 40(5) of the amending Act) by Finance Act 1999 (c. 16), s. 40(4)
F1032Words in s. 365(3) substituted (with effect in accordance with s. 83(4) of the amending Act) by Finance Act 2000 (c. 17), s. 83(1)(a)
F1033Words in s. 365(3) substituted (with effect in accordance with s. 83(4) of the amending Act) by Finance Act 2000 (c. 17), s. 83(1)(b)
Marginal Citations
M45Source-1974 Sch.1 24; 1984 s.22(3)
366 Information.U.K.
(1)M46A person who claims relief under section 353 in respect of any payment of interest shall furnish to the inspector a statement in writing by the person to whom the payment is made, showing—
(a)the date when the debt was incurred;
(b)the amount of the debt when incurred;
(c)the interest paid in the year of assessment for which the claim is made F1034. . . ; and
(d)the name and address of the debtor.
(2)M47Where any such interest as is mentioned in section 353 is paid, the person to whom it is paid shall, if the person who pays it so requests in writing, furnish him with such statement as regards that interest as is mentioned in subsection (1) above; and the duty imposed by this subsection shall be enforceable at the suit or instance of the person making the request.
(3)Subsections (1) and (2) above do not apply to interest paid to a building society, or to a local authority.
Textual Amendments
F1034Words in s. 366(1)(c) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
Marginal Citations
M46Source-1972 Sch.10 7; 1974 Sch.1 25(1)
M47Source-1972 Sch.10 8, 9
367 Provisions supplementary to sections 354 to 366.U.K.
(1)F1035. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1036. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1036. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F1036. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)M48In [F1037section] 365(3) references to the qualifying maximum for the year of assessment are references to such sum as Parliament may determine for the purpose for that year.
Textual Amendments
F1035S. 367(1) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 3(2), Sch. 20 Pt. 3(7)
F1036S. 367(2)-(4) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 71, Sch. 3 Pt. 1 (with Sch. 2)
F1037Words in s. 367(5) substituted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 3(4)
Modifications etc. (not altering text)
C32S. 367(5): £30,000 specified (1988-89) by Finance Act 1988 (c. 39), s. 41
S. 367(5): £30,000 specified (1989-90) by Finance Act 1989 (c. 26), s. 46
S. 367(5): £30,000 specified (1990-91) by Finance Act 1990 (c. 29), s. 71
S. 367(5): £30,000 specified (1991-92) by Finance Act 1991 (c. 31), s. 26
S. 367(5): £30,000 specified (1992-93) by Finance Act 1992 (c. 20), s. 10(4) (with s. 10(5))
S. 367(5): £30,000 specified (1993-94) by Finance Act 1993 (c. 34), s. 55
S. 367(5): £30,000 specified (1994-95, 1995-96) by Finance Act 1994 (c. 9), s. 80
S. 367(5): £30,000 specified (1996-97) by Finance Act 1996 (c. 8), s. 76
S. 367(5): £30,000 specified (1997-98) by Finance Act 1997 (c. 16), s. 57
S. 367(5): £30,000 specified (1998-99) by Finance (No. 2) Act 1997 (c. 58), s. 16
S. 367(5): £30,000 specified (1999-2000) by Finance Act 1999 (c. 16), s. 37
Marginal Citations
M48Source-1972 Sch.9 5(1A); 1984 s.22(1)(c)
[F1038367AAlternative finance arrangementsU.K.
(1)Sections 353 and 365 have effect as if—
(a)purchase and resale arrangements involved the making of a loan, and
(b)alternative finance return were interest.
(2)Section 366 has effect accordingly.
(3)In this section—
“alternative finance return” has the meaning given in sections 564I to 564L of ITA 2007, and
“purchase and resale arrangements” means arrangements to which section 564C of ITA 2007 applies.]
Textual Amendments
F1038S. 367A inserted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 2 para. 47 (with Sch. 9)
368 Exclusion of double relief etc.U.K.
F1039. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1039S. 368 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 72, Sch. 3 Pt. 1 (with Sch. 2)
Mortgage interest relief at sourceU.K.
369 Mortgage interest payable under deduction of tax.U.K.
(1)M49If a person who is a qualifying borrower makes a payment of relevant loan interest to which this section applies, he shall be entitled, on making the payment, to deduct and retain out of it a sum equal to [F1040the applicable percentage thereof.]
[F1041(1A)In subsection (1) above “the applicable percentage” means [F104223 per cent.].]
(2)Where a sum is deducted under subsection (1) above from a payment of relevant loan interest—
(a)the person to whom the payment is made shall allow the deduction on receipt of the residue;
(b)the borrower shall be acquitted and discharged of so much money as is represented by the deduction as if the sum had been actually paid; and
(c)the sum deducted shall be treated as income tax paid by the person to whom the payment is made.
[F1043(3)The following payments, that is to say—
(a)payments of relevant loan interest to which this section applies, and
(b)payments which would be such payments but for section 373(5),
shall not be allowable as deductions for any purpose of the Income Tax Acts except in so far as they fall to be treated as such payments by virtue only of section 375(2) and would be allowable apart from this subsection.]
(6)[F1044M50Sections 967(2) and 968(2) of CTA 2010 do not apply to a payment of relevant loan interest to which this section applies, but any person by whom such a payment] is received shall be entitled to recover from the Board, in accordance with regulations, an amount which by virtue of subsection (2)(c) above is treated as income tax paid by him; and any amount so recovered shall be treated for the purposes of the Tax Acts in like manner as the payment of relevant loan interest to which it relates.
[F1045(7)The following provisions of the Management Act, namely—
[F1046(a)section 29(1)(c) (excessive relief) as it has effect apart from section 29(2) to (10) of that Act;]
(b)section 30 (tax repaid in error etc.) [F1047apart from subsection (1B)],
(c)[F1048section 86] (interest), and
(d)section 95 (incorrect return or accounts),
shall apply in relation to an amount which is paid to any person by the Board as an amount recoverable in accordance with regulations made by virtue of subsection (6) above but to which that person is not entitled as if it were income tax which ought not to have been repaid and, where that amount was claimed by that person, as if it had been repaid [F1049as respects a chargeable period] as a relief which was not due.]
[F1050(8)In the application of section 86 of the Management Act by virtue of subsection (7) above in relation to sums due and payable by virtue of an assessment made for the whole or part of a year of assessment (“the relevant year of assessment”) under section 29(1)(c) or 30 of that Act, as applied by that subsection, the relevant date—
(a)is 1st January in the relevant year of assessment in a case where the person falling within subsection (6) above has made a relevant interim claim; and
(b)in any other case, is the later of the following dates, that is to say—
(i)1st January in the relevant year of assessment; or
(ii)the date of the making of the payment by the Board which gives rise to the assessment.
(9)In this section—
“financial year”, in relation to any person, means a financial year of that person for the purposes of the relevant regulations;
“interim claim” means an interim claim within the meaning of the relevant regulations;
“relevant interim claim” means, in relation to an assessment made for a period coterminous with, or falling wholly within, a person’s financial year, an interim claim made for a period falling wholly or partly within that financial year; and
“the relevant regulations” means regulations made under section 378(3) for the purposes of subsection (6) above.]
Textual Amendments
F1040Words in s. 369(1) substituted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), s. 81(3)
F1041S. 369(1A) substituted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 4
F1042Words in s. 369(1A) substituted (with effect in accordance with s. 83(4) of the amending Act) by Finance Act 2000 (c. 17), s. 83(3)
F1043S. 369(3) substituted for s. 369(3)-(5B) (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), s. 81(4)
F1044Words in s. 369(6) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 33 (with Sch. 2)
F1045S. 369(7) inserted (27.7.1993) by 1993 c. 34, s. 58(1)(2)
F1046S. 369(7)(a) substituted (with effect in accordance with Sch. 18 para. 17(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 6(2)(a)
F1047Words in s. 369(7)(b) inserted (with effect in accordance with Sch. 18 para. 17(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 6(2)(b)
F1048Words in s. 369(7)(c) substituted (with effect in accordance with Sch. 18 para. 17(3) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 6(2)(c)
F1049Words in s. 369(7) inserted (with effect in accordance with Sch. 18 para. 17(8) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 6(2)(d)
F1050S. 369(8)(9) inserted (with effect in accordance with Sch. 18 para. 17(3) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 6(3)
Modifications etc. (not altering text)
C33S. 369(1) excluded (27.7.1999) by Finance Act 1999 (c. 16), s. 38(2)-(7)
Marginal Citations
M49Source-1982 s.26(1), (2)
M50Source-1982 s.26(7)
370 Relevant loan interest.U.K.
(1)M51Subject to this section and [F1051sections 373] to 376, in this Part “relevant loan interest” means interest which is paid and payable in the United Kingdom to a qualifying lender and to which subsection (2) F1052. . . below applies.
(2)Subject to subsection (4) below, this subsection applies to interest if, disregarding section 353(2) [F1053and any other provision applying to interest falling to be treated as relevant loan interest]—
(a)it is interest falling within section F1054. . . 365; and
(b)apart [F1055(where applicable) from] section F1054. . . 365(3), the whole of the interest [F1056would be eligible for relief under section 353];F1057. . .
(c)F1057. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1058. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F1058. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)M52In determining whether subsection (2) above applies to any interest, [F1059section 365 shall] have effect as if the words “or the Republic of Ireland” were omitted.
(6)F1058. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1060(6A)F1061. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(7)F1058. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1051Words in s. 370(1) substituted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 5(2)(a)
F1052Words in s. 370(1) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 5(2)(b), Sch. 20 Pt. 3(7)
F1053Words in s. 370(2) inserted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), Sch. 9 para. 10(1)(a)
F1054Words in s. 370(2) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 5(3), Sch. 20 Pt. 3(7)
F1055Words in s. 370(2)(b) substituted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), Sch. 9 para. 10(1)(b)
F1056Words in s. 370(2)(b) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 155 (with Sch. 2)
F1057S. 370(2)(c) and preceding word repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 5(3), Sch. 20 Pt. 3(7)
F1058S. 370(3)(4)(6)(7) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 5(4), Sch. 20 Pt. 3(7)
F1059Words in s. 370(5) substituted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 5(5)
F1060S. 370(6A) inserted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), Sch. 9 para. 10(2)
F1061S. 370(6A) repealed (with effect in accordance with s. 42(3)-(5) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(2), Note
Marginal Citations
M51Source-1982 Sch.7 2(1)-(3)
M52Source-1982 Sch.7 3(1)-(3)
F1062371 Second loans.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1062S. 371 repealed (27.7.1993 with effect in relation to payments of interest made on or after 16 March 1993 (whenever falling due)) by Finance Act 1993 (c. 34), ss. 57, 213, Sch. 23 Pt.III
372 Home improvement loans.U.K.
F1063. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1063S. 372 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 6, Sch. 20 Pt. 3(7)
373 Loans in excess of the qualifying maximum, and joint borrowers.U.K.
(1)M53The provisions of this section have effect in relation to a loan where, by virtue of F1064. . . section 365(3), only part of the interest on the loan would (apart from section 353(2)) be eligible for relief under section 353; and in this section any such loan is referred to as a “limited loan”.
(2)None of the interest on a limited loan is relevant loan interest unless—
(a)the loan is made on or after 6th April 1987; or
(b)the qualifying lender to whom the interest is payable has given notice to the Board in accordance with regulations that he is prepared to have limited loans of a description which includes that limited loan brought within the tax deduction scheme.
(3)F1065. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F1065. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)M54Where the condition in paragraph (a) or (b) of subsection (2) above is fulfilled F1066. . . only so much of the interest as (apart from section 353(2)) would be eligible for relief under section 353 is relevant loan interest.
(6)M55Where a loan on which interest is payable by the borrower was made jointly to the borrower and another person who is not the borrower’s husband or wife, the interest on the loan is not relevant loan interest unless—
(a)each of the persons to whom the loan was made is a qualifying borrower; and
(b)in relation to each of them considered separately, the whole of that interest is relevant loan interest, in accordance with [F1067section 370] and this section.
(7)In subsection (6) above references to the borrower’s husband or wife do not include references to a separated husband or wife F1068. . . .
Textual Amendments
F1064Words in s. 373(1) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 7(2)(a), Sch. 20 Pt. 3(7)
F1065S. 370(3)(4) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 7(2)(b), Sch. 20 Pt. 3(7)
F1066Words in s. 373(5) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 7(2)(c), Sch. 20 Pt. 3(7)
F1067Words in s. 373(6) substituted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 7(3)
F1068Words in s. 373(7) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 7(2)(d), Sch. 20 Pt. 3(7)
Marginal Citations
M53Source-1982 Sch.7 5(1)-(3); 1985 s.37(2)
M54Source-1982 Sch.7 5(4); 1983 s.17(2); 1985 s.37(3)
M55Source-1982 Sch.7 6(1), (2)
374 Conditions for application of section 369.U.K.
(1)M56Section 369 does not apply to any relevant loan interest unless—
(a)in the case of a loan of a description specified by regulations for the purposes of this paragraph, the borrower or, in the case of joint borrowers, each of them has given notice to the lender in the prescribed form certifying—
(i)that he is a qualifying borrower; and
(ii)that the interest is relevant loan interest; and
(iii)such other matters as may be prescribed; or
(b)the Board have given notice to the lender and the borrower that the interest may be paid under deduction of tax; or
(c)F1069. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(d)M57the loan to which the interest relates is of a description specified by regulations for the purposes of this paragraph and was made—
(i)if sub-paragraph (2) of paragraph 2 of Schedule 7 to the Finance Act 1982 applied to interest on the loan which became due on or after a date earlier than 6th April 1983, being a date specified by the Board in pursuance of sub-paragraph (5) of that paragraph, before that earlier date; or
(ii)if the qualifying lender is a building society or a local authority, before 1st April 1983; or
(iii)if sub-paragraphs (i) and (ii) above do not apply and the interest falls within section 370(2), before 6th April 1983.
(2)M58Where notice has been given as mentioned in paragraph (a) or (b) of subsection (1) above, section 369 applies to any relevant loan interest to which the notice relates and which becomes due on or after the relevant date, as defined by subsection (3) below; and in a case falling within paragraph F1070. . . (d) of subsection (1) above, section 369 applies to the relevant loan interest referred to in that paragraph.
(3)In subsection (2) above “the relevant date” means—
(a)in the case of a notice under subsection (1)(a) above, the date the notice is given, and
(b)in the case of a notice under subsection (1)(b) above, a date specified in the notice as being the relevant date (which may be earlier than the date so specified as the date from which the interest may be paid under deduction of tax).
Textual Amendments
F1069S. 374(1)(c) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 8, Sch. 20 Pt. 3(7)
F1070Words in s. 374(2) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 8, Sch. 20 Pt. 3(7)
Marginal Citations
M56Source-1982 Sch.7 7(1)(a)-(c)
M57Source-1982 Sch.7 7(1)(d), (4), (5)
M58Source-1982 Sch.7 7(2)(3)
[F1071374A Interest which never has been relevant loan interest etc.U.K.
(1)This section applies where, in the case of any loan, interest on the loan never has been relevant loan interest or the borrower never has been a qualifying borrower.
(2)Without prejudice to subsection (3) below, in relation to a payment of interest—
(a)as respects which either of the conditions mentioned in paragraphs (a) and (b) of section 374(1) is fulfilled, and
(b)from which a deduction was made as mentioned in section 369(1),
section 369 shall have effect as if the payment of interest were a payment of relevant loan interest made by a qualifying borrower.
(3)Nothing in subsection (2) above shall be taken as regards the borrower as entitling him to make any deduction or to retain any amount deducted and, accordingly, where any amount has been deducted, he shall be liable to make good that amount and an officer of the Board may make such assessments as may in his judgment be required for recovering that amount.
(4)The Management Act shall apply to an assessment under subsection (3) above as if it were an assessment to income tax for the year of assessment in which the deduction was made F1072. . . .
(5)If the borrower fraudulently or negligently makes any false statement or representation in connection with the making of any deduction, he shall be liable to a penalty not exceeding the amount deducted.]
Textual Amendments
F1071S. 374A inserted (with application in accordance with s. 112(5) of the amending Act) by Finance Act 1995 (c. 4), s. 112(1)
F1072Words in s. 374A(4) repealed (with effect in accordance with Sch. 18 para. 17(5) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 18 para. 7, Sch. 41 Pt. 5(8), Note
375 Interest ceasing to be relevant loan interest, etc.U.K.
(1)M59If at any time—
(a)the interest on a loan ceases to be relevant loan interest; or
(b)a person making payments of relevant loan interest ceases to be a qualifying borrower;
the borrower shall give notice of the fact to the lender.
(2)Without prejudice to subsection (3) below, in relation to a payment of interest—
(a)which is due after the time referred to in subsection (1) above and before the date on which notice is given under that subsection, and
[F1073(aa)as respects which any of the conditions mentioned in section 374(1) is fulfilled, and]
(b)from which a deduction was made as mentioned in section 369(1),
section 369 shall have effect as if the payment were a payment of relevant loan interest made by a qualifying borrower.
(3)Nothing in subsection (2) above [F1074shall be taken as regards the borrower as entitling him to any deduction or to retain any amount deducted and, accordingly, where any amount that has been deducted exceeds the amount which ought to have been deducted], he shall be liable to make good the excess and an inspector may make such assessments as may in his judgment be required for recovering the excess.
[F1075(4)The Management Act shall apply to an assessment under subsection (3) above [F1076as if it were an assessment to income tax for the year of assessment in which the deduction was made].
(4A)If there is any unreasonable delay in the giving of a notice under subsection (1) above, the borrower shall be liable to a penalty not exceeding so much of the aggregate amount that he is liable to make good under subsection (3) above as is attributable to that delay.]
(5)M60If, as a result of receiving a notice under subsection (1) above or otherwise, a qualifying lender has reason to believe that any interest is no longer relevant loan interest or that a borrower is no longer a qualifying borrower, the lender shall furnish the Board with such information as is in his possession with respect to those matters.
(6)M61Where it appears to the Board that any of the provisions of sections 370 to 373 is not or may not be fulfilled with respect to any interest, or that a qualifying borrower has or may have ceased to be a qualifying borrower, they shall give notice of that fact to the lender and the borrower specifying the description of relevant loan interest concerned or, as the case may be, that the borrower has or may have ceased to be a qualifying borrower.
(7)Section 369 shall not apply to any payment of relevant loan interest of a description to which a notice under subsection (6) above relates and which becomes due or is made after such date as may be specified in the notice and before such date as may be specified in a further notice given by the Board to the lender and the borrower.
(8)M62In any case where—
(a)section 369 applies to any relevant loan interest by virtue of a notice under section 374(1)(b), and
(b)the relevant date specified in the notice is earlier than the date from which the interest begins to be paid under deduction of tax, and
(c)a payment of that interest was made on or after the relevant date but not under deduction of tax,
regulations may provide for a sum to be paid by the Board of an amount equal to that which the borrower would have been able to deduct from that payment by virtue of section 369 if it had been made after the relevant date.
[F1077(8A)In any case where an amount to which a person is not entitled is paid to him by the Board in pursuance of regulations made by virtue of subsection (8) above, regulations may—
(a)provide for an officer of the Board to make such assessments as may in his judgment be required for recovering that amount from that person; and
(b)make provision corresponding to that made by subsection (4A) above and subsections (4) and (5) of section 374A.]
[F1078(8B)Subsections (1), (5) and (6) above shall not apply where interest ceases to be relevant loan interest by virtue of section 38 of the Finance Act 1999.]
(9)F1079. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(10)F1079. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1073S. 375(2)(aa) inserted (with application in accordance with s. 112(5) of the amending Act) by Finance Act 1995 (c. 4), s. 112(2)
F1074Words in s. 375(3) substituted (with effect in accordance with s. 81(6) of the amending Act) by Finance Act 1994 (c. 9), Sch. 9 para. 11
F1075S. 375(4)(4A) substituted for s. 375(4) (with application in accordance with s. 112(5) of the amending Act) by Finance Act 1995 (c. 4), s. 112(3)
F1076Words in s. 375(4) substituted (with effect in accordance with Sch. 18 para. 17(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 8
F1077S. 375(8A) inserted (with application in accordance with s. 112(5) of the amending Act) by Finance Act 1995 (c. 4), s. 112(4)
F1078S. 375(8B) inserted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 9(1)
F1079S. 375(9)(10) repealed (with effect in accordance with Sch. 4 para. 18(1) of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 9(2), Sch. 20 Pt. 3(7), Note 1
Marginal Citations
M59Source-1982 Sch.7 8
M60Source-1982 Sch.7 9(1)
M61Source-1982 Sch.7 10(1), (2)
M62Source-1982 Sch.7 11
[F1080375A Option to deduct interest for the purposes of Schedule A.U.K.
F1081. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1080S. 375A inserted (with effect in accordance with s. 39(4)(5) of the amending Act) by Finance Act 1995 (c. 4), Sch. 6 para. 18
F1081S. 375A repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 10, Sch. 20 Pt. 3(7)
376 Qualifying borrowers and qualifying lenders.U.K.
(1)M63Subject to subsection (2) below, an individual is a qualifying borrower with respect to the interest on any loan.
(2)In relation to interest paid at a time when the borrower or the borrower’s husband or wife holds [F1082an office or employment which would, but for some special exemption or immunity from tax, be a taxable employment under Part 2 of ITEPA 2003 (as defined by section 66(3) of that Act)], the borrower is not a qualifying borrower.
(3)In subsection (2) above references to the borrower’s husband or wife do not include references to a separated husband or wife F1083. . . .
(4)M64The following bodies are qualifying lenders:—
(a)a building society;
(b)a local authority;
(c)the Bank of England;
(d)F1084. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1085(e)a person who has permission under [F1086Part 4A] of the Financial Services and Markets Act 2000 to effect or carry out contracts of long-term insurance;]
(f)any company to which property and rights belonging to a trustee savings bank were transferred by section 3 of the M65Trustee Savings Bank Act 1985;
(g)F1087. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(h)a development corporation within the meaning of the M66New Towns Act 1981 or the M67New Towns (Scotland) Act 1968;
[F1088(j)the Homes and Communities Agency;]
[F1089(ja)the Greater London Authority so far as exercising its housing or regeneration functions or its new towns and urban development functions;]
[F1090(k)the Regulator of Social Housing,]
[F1091(ka)the Secretary of State if the loan is made by him under section 79 of the M68Housing Associations Act 1985;]
(l)the Northern Ireland Housing Executive;
(m)the Scottish Special Housing Association;
(n)F1092. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(o)the Church of England Pensions Board;
[F1093(p)any body which is for the time being registered under section 376A.]
[F1094(4A)F1095. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(5)F1096. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)F1097. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1082Words in s. 376(2) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 52 (with Sch. 7)
F1083Words in s. 376(3) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 11(a), Sch. 20 Pt. 3(7)
F1084S. 376(4)(d) repealed (26.3.2001) by The Postal Services Act 2000 (Consequential Modifications No. 1) Order 2001 (S.I. 2001/1149), arts. 1(2), 3(2), Sch. 2
F1085S. 376(4)(e) substituted (1.12.2001 in accordance with art. 1(2)(a) of the amending Order) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 23(2)(a)
F1086Words in s. 376(4)(e) substituted (1.4.2013) by Financial Services Act 2012 (c. 21), s. 122(3), Sch. 18 para. 58(3) (with Sch. 20); S.I. 2013/423, art. 3, Sch.
F1087S. 376(4)(g) omitted (1.12.2001 in accordance with art. 1(2)(a) of the amending Order) by virtue of The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 23(2)(b)
F1088S. 376(4)(j) substituted (1.12.2008) by Housing and Regeneration Act 2008 (c. 17), s. 325(1), Sch. 8 para. 42; S.I. 2008/3068, art. 2(1)(w) (with arts. 6-13)
F1089S. 376(4)(ja) inserted (1.4.2012) by Localism Act 2011 (c. 20), s. 240(2), Sch. 19 para. 24; S.I. 2012/628, art. 6(1) (with arts. 9-20)
F1090S. 376(4)(k) substituted (1.4.2010) by Housing and Regeneration Act 2008 (c. 17), s. 325(1), Sch. 9 para. 12; S.I. 2010/862, art. 2 (with Sch.)
F1091S. 376(4)(ka) substituted (1.11.1998) by Government of Wales Act 1998 (c. 38), ss. 140(2), 158(1), Sch. 16 para. 55; S.I. 1998/2244, art. 5
F1092S. 376(4)(n) repealed (1.10.1998) by Government of Wales Act 1998 (c. 38), ss. 152, 158(1), Sch. 18 Pt. 4; S.I. 1998/2244, art. 4
F1093S. 376(4)(p) substituted (1.12.2001 in accordance with art. 1(2)(a) of the amending Order) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 23(2)(c)
F1094S. 376(4A) inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 paras. 3(3), 22; S.I. 1993/236, art. 2
F1095S. 376(4A) omitted (1.12.2001 in accordance with art. 1(2)(a) of the amending Order) by virtue of The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 23(3)
F1096S. 376(5) repealed (3.5.1994) by Finance Act 1994 (c. 9), s. 142(1)(b), Sch. 26 Pt. 5(19)
F1097S. 376(6) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 11(b), Sch. 20 Pt. 3(7)
Marginal Citations
M63Source-1982 Sch.7 13
M64Source-1982 Sch.7 14(1); 1983 s.17(3)
[F1098376A The register of qualifying lenders.U.K.
(1)The Board shall maintain, and publish in such manner as they consider appropriate, a register for the purposes of section 376(4).
[F1099(1A)The following are entitled to be registered—
(a)a person who has permission under [F1100Part 4A] of the Financial Services and Markets Act 2000—
(i)to accept deposits; or
(ii)to effect or carry out contracts of general insurance;
(b)a 90 per cent subsidiary of a person mentioned in—
(i)section 376(4)(e); or
(ii)paragraph (a) above;
(c)any other body whose activities and objects appear to the Board to qualify it for registration.]
(2)If the Board are satisfied that an applicant for registration is entitled to be registered, they may register the applicant generally or in relation to any description of loan specified in the register, with effect from such date as may be so specified; and a body which is so registered shall become a qualifying lender in accordance with the terms of its registration.
(3)The registration of any body may be varied by the Board—
(a)where it is general, by providing for it to be in relation to a specified description of loan, or
(b)where it is in relation to a specified description of loan, by removing or varying the reference to that description of loan,
and where they do so, they shall give the body written notice of the variation and of the date from which it is to have effect.
(4)If it appears to the Board at any time that a body which is registered under this section would not be entitled to be registered if it applied for registration at that time, the Board may by written notice given to the body cancel its registration with effect from such date as may be specified in the notice.
(5)The date specified in a notice under subsection (3) or (4) above shall not be earlier than the end of the period of 30 days beginning with the date on which the notice is served.
(6)Any body which is aggrieved by the failure of the Board to register it under this section, or by the variation or cancellation of its registration, may [F1101appeal], by notice given to the Board before the end of the period of 30 days beginning with the date on which the body is notified of the Board’s decisionF1102. . . .]
Textual Amendments
F1098S. 376A inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 142(2)
F1099S. 376A(1A) inserted (1.12.2001 in accordance with art. 1(2)(a) of the amending Order) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 24
F1100Words in s. 376A(1A)(a) substituted (1.4.2013) by Financial Services Act 2012 (c. 21), s. 122(3), Sch. 18 para. 58(4) (with Sch. 20); S.I. 2013/423, art. 3, Sch.
F1101Word in s. 376A(6) inserted (1.4.2009) by The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 138(a)
F1102Words in s. 376A(6) omitted (1.4.2009) by virtue of The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 138(b)
377 Variation of terms of repayment of certain loans.U.K.
F1103. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1103S. 377 repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 12, Sch. 20 Pt. 3(7)
378 Supplementary regulations.U.K.
M69(1)F1104. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1104. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)The Board may by regulations make provision—
(a)for the purposes of any provision of sections 369 to [F1105376A] which relates to any matter or thing to be specified by or done in accordance with regulations;
(b)for the application of those sections in relation to loan interest paid by personal representatives and trustees;
(c)with respect to the furnishing of information by borrowers or lenders, including, in the case of lenders, the inspection of books, documents and other records on behalf of the Board;
(d)for, and with respect to, appeals to [F1106the tribunal] against the refusal of the Board to issue a notice under section 374(1)(b) or the issue of a notice under section 375(6) or (7); and
(e)generally for giving effect to sections 369 to [F1105376A].
(4)F1104. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1104S. 378(1)(2)(4) repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 13(a), Sch. 20 Pt. 3(7)
F1105Words in s. 378(3) substituted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 13(b)
F1106Words in s. 378(3) substituted (1.4.2009) by The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 139
Marginal Citations
M69Source-1982 s.29; 1984 s.56(2)
379
In sections 369 to 378—
[F1107“contracts of general insurance” means contracts which fall within Part I of Schedule 1 to the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001 and “contracts of long-term insurance” means contracts which fall within Part II of that Schedule;]
“prescribed” F1108. . . means prescribed by the Board;
“qualifying borrower” has the meaning given by section 376(1) to (3);
“qualifying lender” has the meaning given by section 376(4) F1109. . . ;
“regulations” F1110 . . . means regulations made by the Board under section 378;
“relevant loan interest” has the meaning given by section 370(1);
[F1111“separated” means separated under an order of a court of competent jurisdiction or by deed of separation or in such circumstances that the separation is likely to be permanent.]
Textual Amendments
F1107S. 379: definition of "contracts of general insurance" inserted (1.12.2001 in accordance with art. 1(2)(a) of the amending Order) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 25
F1108S. 379: words in definition of "prescribed" repealed (3.5.1994) by Finance Act 1994 (c. 9), Sch. 26 Pt. 5(19)
F1109S. 379: words in definition of "qualifying lender" repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 14(a), Sch. 20 Pt. 3(7)
F1110S. 379: words in definition of "regulations" repealed (with effect in accordance with Sch. 4 para. 18(5), Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 4 para. 14(b), Sch. 20 Pt. 3(7)
F1111S. 379: definition of "separated" inserted (with effect in accordance with Sch. 4 para. 18(5) of the amending Act) by Finance Act 1999 (c. 16), Sch. 4 para. 14(c)
PART XU.K. LOSS RELIEF AND GROUP RELIEF
[F1112CHAPTER IU.K. LOSS RELIEF: INCOME TAX]
Textual Amendments
F1112Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
[F1113[F1114Losses from [F1115UK property] business or overseas property business]U.K.
Textual Amendments
F1113S. 379A and preceding cross-heading inserted (with effect in accordance with s. 39(4)(5) of the amending Act) by Finance Act 1995 (c. 4), Sch. 6 para. 19(1)
F1114S. 379A cross-heading substituted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 26 (with Sch. 5 para. 73)
F1115Words in cross-heading preceding s. 379A substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 156(8) (with Sch. 2)
379A[F1116Losses from UK property business].U.K.
F1117. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1116S. 379A sidenote substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by virtue of Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 156(7) (with Sch. 2)
F1117Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
[F1118379B Losses from overseas property business.U.K.
F1119. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F1118S. 379B inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 27 (with Sch. 5 para. 73)
F1119Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
Trade etc. lossesU.K.
380 Set-off against general income.U.K.
F1120. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1120Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
381 Further relief for individuals for losses in early years of trade.U.K.
F1121. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1121Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
382 Provisions supplementary to sections 380 and 381.U.K.
F1122. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1122Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
383 Extension of right of set-off to capital allowances.U.K.
F1123. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1123S. 383 repealed (with effect in accordance with ss. 211(2), 218(1)(b) of the repealing Act) by Finance Act 1994 (c. 9), s. 214(1)(b), Sch. 26 Pt. 5(24), Note 5
384 Restrictions on right of set-off.U.K.
F1124. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1124Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
[F1125384A Restriction of set-off of allowances against general incomeU.K.
F1126. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1125S. 384A inserted (with effect in accordance with s. 579(1) of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 30 (with Sch. 3)
F1126Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
385 Carry-forward against subsequent profits.U.K.
F1127. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1127Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
386 Carry-forward where business transferred to a company.U.K.
F1128. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1128Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
387 Carry-forward as losses of amounts taxed under section 350.U.K.
F1129. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1129Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
388 Carry-back of terminal losses.U.K.
F1130. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1130Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
389 Supplementary provisions relating to carry-back of terminal losses.U.K.
F1131. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1131Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
390 Treatment of interest as a loss for purposes of carry-forward and carry-back.U.K.
F1132. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1132Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
391 Losses from trade etc. carried on abroadU.K.
F1133. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1133Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
Case VI lossesU.K.
392Losses from miscellaneous transactionsU.K.
F1134. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1134Pt. 10 Ch. 1 (ss. 379A-392) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
[F1135CHAPTER IIU.K. LOSS RELIEF: CORPORATION TAX]
Textual Amendments
F1135Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
[F1136 Losses from [F1137UK property business] or overseas property businessU.K.
Textual Amendments
F1136Ss. 392A, 392B and preceding cross-heading inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 28 (with Sch. 5 paras. 72, 73)
F1137Words in cross-heading preceding s. 392A substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 108(8) (with Sch. 2 Pts. 1, 2)
392A[F1138UK property business losses]U.K.
F1139. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1138S. 392A title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 108(7) (with Sch. 2 Pts. 1, 2)
F1139Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
392B Losses from overseas property business.U.K.
F1140. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1140Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
Trade etc. lossesU.K.
393 Losses other than terminal losses.U.K.
F1141. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1141Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
[F1142393A Losses: set off against profits of the same, or an earlier, accounting period.U.K.
F1143. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1142S. 393A inserted by Finance Act 1991 (c. 31), s. 73(1)(4)(5)
F1143Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
[F1144393BLosses of ring fence trade: set off against profits of an earlier accounting periodU.K.
F1145. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1144S. 393B inserted (with effect in accordance with s. 111(3) of the amending Act) by Finance Act 2008 (c. 9), s. 111(1)
F1145Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
F1146394 Terminal losses.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1146S. 394 repealed by Finance Act 1991 (c. 31), ss. 73(2)(4)(5), 123, Sch. 19 Pt. V
395 Leasing contracts and company reconstructions.U.K.
F1147. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1147Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
Case VI lossesU.K.
396[F1148Losses from miscellaneous transactions]U.K.
F1149. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1148S. 396 title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 112(5) (with Sch. 2 Pts. 1, 2)
F1149Pt. 10 Ch. 2 (ss. 392A-396) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 34, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER IIIU.K. LOSS RELIEF: MISCELLANEOUS PROVISIONS
397 Restriction of relief in case of farming and market gardening.U.K.
F1150. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1150S. 397 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 35, Sch. 3 Pt. 1 (with Sch. 2)
398 Transactions in deposits with and without certificates or in debts.U.K.
M70Where [F1151a company] sustains a loss on the exercise or disposal of a right to receive any amount, being a right to which section 56(2) F1152. . . applies, in a case where—
(a)if a profit had arisen from that exercise or disposal, that profit would have been chargeable to [F1153corporation] tax by virtue of section 56(2) F1154. . . , and
(b)[F1155the company is chargeable to corporation tax under [F1156Part 5 of CTA 2009 (loan relationships)]] in respect of interest payable on that amount,
then the amount of that interest shall be included in the amounts against which [F1157the amount of its loss may be set off under [F1158section 91 of CTA 2010].]
Textual Amendments
F1151Words in s. 398 substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 75(2) (with Sch. 2)
F1152Words in s. 398 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 75(3), Sch. 3 Pt. 1 (with Sch. 2)
F1153Words in s. 398(a) inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 75(4)(a) (with Sch. 2)
F1154Words in s. 398(a) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 75(4)(b), Sch. 3 Pt. 1 (with Sch. 2)
F1155Words in s. 398(b) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 75(5) (with Sch. 2)
F1156Words in s. 398(b) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 114 (with Sch. 2 Pts. 1, 2)
F1157Words in s. 398 substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 75(6) (with Sch. 2)
F1158Words in s. 398 substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 36 (with Sch. 2)
Marginal Citations
M70Source—1973 s.26(2); 1974 s.30(2)
399 Dealings in commodity futures etc: withdrawal of loss relief.U.K.
F1159. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1159S. 399 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 37, Sch. 3 Pt. 1 (with Sch. 2)
400 Write-off of government investment.U.K.
F1160. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1160S. 400 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 38, Sch. 3 Pt. 1 (with Sch. 2)
401 Relief for pre-trading expenditure.U.K.
F1161. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1161S. 401 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 117, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1162CHAPTER IVU.K. GROUP RELIEF]
Textual Amendments
F1162Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
402 Surrender of relief between members of groups and consortia.U.K.
F1163. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1163Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403 Losses etc. which may be surrendered by way of group relief.U.K.
F1164. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1164Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1165403ZA Amounts eligible for group relief: trading losses.U.K.
F1166. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1165Ss. 403-403ZE substituted for s. 403 (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 29 (with Sch. 5 para. 73)
F1166Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403ZB Amounts eligible for group relief: excess capital allowances.U.K.
F1167. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1165Ss. 403-403ZE substituted for s. 403 (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 29 (with Sch. 5 para. 73)
F1167Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403ZC Amounts eligible for group relief: non-trading deficit on loan relationships.U.K.
F1168. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1165Ss. 403-403ZE substituted for s. 403 (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 29 (with Sch. 5 para. 73)
F1168Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403ZD Other amounts available by way of group relief.U.K.
F1169. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1165Ss. 403-403ZE substituted for s. 403 (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 29 (with Sch. 5 para. 73)
F1169Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403ZE Computation of gross profits.U.K.
F1170. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1165Ss. 403-403ZE substituted for s. 403 (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 29 (with Sch. 5 para. 73)
F1170Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1171403A Limits on group relief.U.K.
F1172. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1171Ss. 403A-403C inserted (with effect in accordance with Sch. 7 para. 9 of the amending Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 7 para. 2
F1172Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403B Apportionments under section 403A.U.K.
F1173. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1171Ss. 403A-403C inserted (with effect in accordance with Sch. 7 para. 9 of the amending Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 7 para. 2
F1173Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403C Amount of relief in consortium cases.U.K.
F1174. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1171Ss. 403A-403C inserted (with effect in accordance with Sch. 7 para. 9 of the amending Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 7 para. 2
F1174Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1175403D[F1176Relief for or in respect of UK losses of non-resident companies]U.K.
F1177. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1175Ss. 403D, 403E inserted (with effect in accordance with Sch. 27 para. 6(1)(2)(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 27 para. 4
F1176S. 403D title substituted (with effect in accordance with Sch. 1 para. 9 of the amending Act) by virtue of Finance Act 2006 (c. 25), Sch. 1 para. 3(4)
F1177Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
403E Relief for overseas losses of UK resident companies.U.K.
F1178. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1175Ss. 403D, 403E inserted (with effect in accordance with Sch. 27 para. 6(1)(2)(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 27 para. 4
F1178Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1179403FRelief in respect of overseas losses of non-resident companiesU.K.
F1180. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1179S. 403F inserted (with effect in accordance with Sch. 1 para. 9 of the amending Act) by Finance Act 2006 (c. 25), Sch. 1 para. 4(1)
F1180Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1181403GUnallowable overseas losses of non-resident companiesU.K.
F1182. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1181S. 403G inserted (with effect in accordance with Sch. 1 para. 9 of the amending Act) by Finance Act 2006 (c. 25), Sch. 1 para. 4(2)
F1182Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
404 Limitation of group relief in relation to certain dual resident companies.U.K.
F1183. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1183Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
405 Claims relating to losses etc. of members of both group and consortium.U.K.
F1184. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1184Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
406 Claims relating to losses etc. of consortium company or group member.U.K.
F1185. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1185Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
407 Relationship between group relief and other relief.U.K.
F1186. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1186Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
408 Corresponding accounting periods.U.K.
F1187. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1187Ss. 408, 409 repealed (with effect in accordance with Sch. 7 para. 9, Sch. Pt. 2(14) Note of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 7 para. 6, Sch. 8 Pt. 2(14)
409 Companies joining or leaving group or consortium.U.K.
F1188. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1188Ss. 408, 409 repealed (with effect in accordance with Sch. 7 para. 9, Sch. Pt. 2(14) Note of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 7 para. 6, Sch. 8 Pt. 2(14)
410 Arrangements for transfer of company to another group or consortium.U.K.
F1189. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1189Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
411 Exclusion of double allowances.U.K.
F1190. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1190Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1191411ZANo relief where deduction of relevant return under alternative finance arrangements disallowedU.K.
F1192. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1191S. 411ZA inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 124 (with Sch. 2 Pts. 1, 2)
F1192Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
[F1193411A Group relief by way of substitution for loss relief.U.K.
F1194. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1193S. 411A inserted (with effect in accordance with s. 101(2) of the amending Act) by Finance Act 1990 (c. 29), s. 101(1)
F1194S. 411A repealed (with effect in accordance with s. 93(2) of the repealing Act) by Finance Act 1999 (c. 16), Sch. 11 para. 1, Sch. 20 Pt. 3(21), Note
412 Claims and adjustments.U.K.
F1195. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1195Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
413 Interpretation of Chapter IV.U.K.
F1196. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1196Pt. 10 Ch. 4 (ss. 402-413) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 39, Sch. 3 Pt. 1 (with Sch. 2)
PART XIU.K. CLOSE COMPANIES
[F1197CHAPTER IU.K. INTERPRETATIVE PROVISIONS]
Textual Amendments
F1197Pt. 11 Ch. 1 (ss. 414-418) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 40, Sch. 3 Pt. 1 (with Sch. 2)
414 Close companies.U.K.
F1198. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1198Pt. 11 Ch. 1 (ss. 414-418) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 40, Sch. 3 Pt. 1 (with Sch. 2)
415 Certain quoted companies not to be close companies.U.K.
F1199. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1199Pt. 11 Ch. 1 (ss. 414-418) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 40, Sch. 3 Pt. 1 (with Sch. 2)
416 Meaning of “associated company” and “control”.U.K.
F1200. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1200Pt. 11 Ch. 1 (ss. 414-418) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 40, Sch. 3 Pt. 1 (with Sch. 2)
417 Meaning of “participator”, “associate”, “director” and “loan creditor”.U.K.
F1201. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1201Pt. 11 Ch. 1 (ss. 414-418) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 40, Sch. 3 Pt. 1 (with Sch. 2)
Additional matters to be treated as distributionsU.K.
418“Distribution” to include certain expenses of close companies.U.K.
F1202. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1202Pt. 11 Ch. 1 (ss. 414-418) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 40, Sch. 3 Pt. 1 (with Sch. 2)
[F1203CHAPTER IIU.K. CHARGES TO TAX IN CONNECTION WITH LOANS]
Textual Amendments
F1203Pt. 11 Ch. 2 (ss. 419-422) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 41, Sch. 3 Pt. 1 (with Sch. 2)
419 Loans to participators etc.U.K.
F1204. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1204Pt. 11 Ch. 2 (ss. 419-422) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 41, Sch. 3 Pt. 1 (with Sch. 2)
420 Exceptions from section 419.U.K.
F1205. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1205Pt. 11 Ch. 2 (ss. 419-422) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 41, Sch. 3 Pt. 1 (with Sch. 2)
421Taxation of borrower when loan under section 419 released etcU.K.
F1206. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1206Pt. 11 Ch. 2 (ss. 419-422) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 41, Sch. 3 Pt. 1 (with Sch. 2)
422 Extension of section 419 to loans by companies controlled by close companies.U.K.
F1207. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1207Pt. 11 Ch. 2 (ss. 419-422) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 41, Sch. 3 Pt. 1 (with Sch. 2)
[F1208CHAPTER IIIU.K. APPORTIONMENT OF UNDISTRIBUTED INCOME ETC.]
Textual Amendments
F1208Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1209423 Apportionment of certain income, deductions and interest.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1209Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1210424 Exclusions from section 423.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1210Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1211425 Manner of apportionment.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1211Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1212426 Charge to income tax where apportionment is to an individual.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1212Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1213427 Reduction of charge under section 426 in certain cases.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1213Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1214428 Increase of apportioned sum etc. by reference to ACT.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1214Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1215429 Payment and collection of income tax.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1215Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
F1216430 Consequences of apportionment: ACT.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1216Pt. 11 Ch. 3 (ss. 423-430) repealed (with effect in accordance with s. 103(1) of the repealing Act) by Finance Act 1989 (c. 4), Sch. 17 Pt. 5, Note 4 (with s. 103(2))
PART XIIU.K. SPECIAL CLASSES OF COMPANIES AND BUSINESSES
CHAPTER IU.K. INSURANCE COMPANIES, UNDERWRITERS AND CAPITAL REDEMPTION BUSINESS
Insurance companies: generalU.K.
431 Interpretative provisions relating to insurance companies.U.K.
F1217. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1217S. 431 omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 11 (with Sch. 17) (subject to an amendment (1.4.2013) by Financial Services Act 2012 (c. 21), s. 58(5); S.I. 2013/423, art. 3, Sch.)
[F1218431ZAElection that assets not be foreign business assetsU.K.
F1219. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1218S. 431ZA inserted (with effect in accordance with Sch. 17 para. 10(6)(7) of the amending Act) by Finance Act 2008 (c. 9), Sch. 17 para. 10(2)
F1219S. 431ZA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 12 (with Sch. 17)
[F1220431A Amendment of Chapter etcU.K.
F1221. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1220S. 431A inserted (1.1.1990) by Finance Act 1990 (c. 29), Sch. 6 paras. 2, 11(2) (with Sch. 6 para. 12)
F1221S. 431A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 13 (with Sch. 17)
[F1222431AA Relevant benefits for purposes of section 431(4)(d) and (e).U.K.
F1223. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1222S. 431AA inserted (with application in accordance with s. 143(5) of the amending Act) by Finance Act 1994 (c. 9), s. 143(4)
F1223S. 431AA repealed (with effect in accordance with Sch. 8 para. 57 of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(5), Note 2
[F1224Classes of life assurance business]U.K.
Textual Amendments
F1224Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
[F1225431B Meaning of “pension business”.U.K.
F1226. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1226S. 431B omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 14 (with Sch. 17)
[F1227431BAMeaning of “child trust fund business”U.K.
F1228. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1227Ss. 431BA, 431BB inserted (with effect in accordance with s. 38(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 7 para. 8 (with Sch. 7 Pt. 2)
F1228S. 431BA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 15 (with Sch. 17)
431BBMeaning of “individual savings account business”U.K.
F1229. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1227Ss. 431BA, 431BB inserted (with effect in accordance with s. 38(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 7 para. 8 (with Sch. 7 Pt. 2)
F1229S. 431BB omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 16 (with Sch. 17)
431C Meaning of “life reinsurance business”.U.K.
F1230. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1230S. 431C omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 17 (with Sch. 17)
431D Meaning of “overseas life assurance business”.U.K.
F1231. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1231Ss. 431D, 431E omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 18 (with Sch. 17)
431E Overseas life assurance business: regulations.U.K.
F1232. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1232Ss. 431D, 431E omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 18 (with Sch. 17)
[F1233431EAMeaning of “gross roll-up business”U.K.
F1234. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1233S. 431EA inserted (with effect in accordance with s. 38(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 7 para. 10 (with Sch. 7 Pt. 2)
F1234S. 431EA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 19 (with Sch. 17)
431F Meaning of “basic life assurance and general annuity business”.U.K.
F1235. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1225Ss. 431B-431F and cross-heading inserted (with effect in accordance with Sch. 8 paras. 55, 57 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 2
F1235S. 431F omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 20 (with Sch. 17)
[F1236[F1237Basis of taxation etc]]U.K.
Textual Amendments
F1236Cross-heading before s. 432 inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 51(2) (with Sch. 8 para. 55(2))
F1237Ss. 431G, 431H and preceding cross-heading substituted for s. 432 and preceding cross-heading (with effect in accordance with s. 39(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 8 para. 4 (with Sch. 8 Pt. 2)
[F1238431GCompany carrying on life assurance businessU.K.
F1239. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1238Ss. 431G, 431H and preceding cross-heading substituted for s. 432 and preceding cross-heading (with effect in accordance with s. 39(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 8 para. 4 (with Sch. 8 Pt. 2)
F1239S. 431G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 21 (with Sch. 17)
[F1240431HCompany carrying on life assurance business and other insurance businessU.K.
F1241. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1240Ss. 431G, 431H and preceding cross-heading substituted for s. 432 and preceding cross-heading (with effect in accordance with s. 39(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 8 para. 4 (with Sch. 8 Pt. 2)
F1241S. 431H omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 22 (with Sch. 17)
432. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1245432YA[F1246PHI business] other than life assurance business — adjustment consequent on change in Insurance Prudential SourcebookU.K.
F1247. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1245S. 432YA inserted (8.1.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Insurance Companies (Corporation Tax Acts) (Amendment No. 2) Order 2006 (S.I. 2006/3387), arts. 1(1), 2
F1246Words in s. 432YA heading substituted (27.12.2008 with effect in accordance with art. 1(2) of the amending S.I.) by The Insurance Companies (Corporation Tax Acts) (Amendment) (No. 2) Order 2008 (S.I. 2008/3096), arts. 1(1), 2(4)
F1247S. 431YA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 23 (with Sch. 17)
[F1248432ZA Linked assets.U.K.
F1249. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1248S. 432ZA inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 11(2) (with Sch. 8 para. 55(2))
F1249S. 431ZA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 24 (with Sch. 17)
[F1250432A Apportionment of income and gains.U.K.
F1251. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1250Ss. 432A-432E inserted by Finance Act 1990 (c. 29), Sch. 6 para. 4
F1251S. 432A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 25 (with Sch. 17)
[F1252432AA[F1253UK property business or overseas property business]U.K.
F1254. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1252Ss. 432AA, 432AB inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para 39 (with Sch. 5 para. 73)
F1253S. 432AA title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 131(3) (with Sch. 2 Pts. 1, 2)
F1254S. 432AA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 26 (with Sch. 17)
432AB Losses from [F1255UK property business] or overseas property business.U.K.
F1256. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1252Ss. 432AA, 432AB inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para 39 (with Sch. 5 para. 73)
F1255Words in s. 432AB title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 132(4) (with Sch. 2 Pts. 1, 2)
F1256S. 432AB omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 27 (with Sch. 17)
[F1257432B Apportionment of receipts brought into account.U.K.
F1258. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1257Ss. 432A-432E inserted by Finance Act 1990 (c. 29), Sch. 6 para. 4
F1258Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
[F1259432CSection 432B apportionment: non-participating fundsU.K.
F1260. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1259Ss. 432A-432E inserted by Finance Act 1990 (c. 29), Sch. 6 para. 4
F1260Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
[F1261432CAApportionment of asset value increase where line 51 amount decreasesU.K.
F1262. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1261S. 432CA inserted (with effect in accordance with s. 47(2)-(4) of the amending Act) by Finance Act 2010 (c. 13), s. 47(1)
F1262Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
[F1263432CBTransfers of business involving excess assetsU.K.
F1264. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1263S. 432CB inserted (with effect in accordance with s. 9(2) of the amending Act) by Finance (No. 2) Act 2010 (c. 31), s. 9(1)
F1264Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
[F1265432D Section 432B apportionment: value of non-participating funds.U.K.
F1266. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1265Ss. 432A-432E inserted by Finance Act 1990 (c. 29), Sch. 6 para. 4
F1266S. 432D repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 18, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
[F1267432ESection 432B apportionment: participating funds.U.K.
F1268. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1267Ss. 432A-432E inserted by Finance Act 1990 (c. 29), Sch. 6 para. 4
F1268Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
[F1269432F Section 432B apportionment: supplementary provisions.U.K.
F1270. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1269S. 432F inserted (with effect in accordance with Sch. 8 para. 53 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 17(3) (with Sch. 8 para. 55(2))
F1270Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
[F1271432GSection 432B apportionment: business transfers-inU.K.
F1272. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1271S. 432G inserted (1.1.2005 with effect in accordance with art. 1 of the amending S.I.) by The Insurance Companies (Corporation Tax Acts) Order 2004 (S.I. 2004/3266), art. 4
F1272Ss. 432B-432G omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 28 (with Sch. 17)
F1273433 Profits reserved for policy holders and annuitants.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1273S. 433 repealed (14.3.1989) by Finance Act 1989 (c. 26), s. 84(5), Sch. 8 para. 2, Sch. 17 Pt. IV, Note 3 (with s. 84(6))
[F1274Miscellaneous provisions relating to life assurance business]U.K.
Textual Amendments
F1274Cross-heading before s. 434 inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 51(4) (with Sch. 8 para. 55(2))
434 Franked investment income etc.U.K.
F1275. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1275S. 434 omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 29 (with Sch. 17)
[F1276434A Computation of losses and limitation on relief.U.K.
F1277. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1276S. 434A inserted by Finance Act 1989 (c. 26), s. 84(4)-(6), Sch. 8 para. 4
F1277S. 434A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 30 (with Sch. 17)
[F1278434AZAReduced loss relief for additions to non-profit fundsU.K.
F1279. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1278Ss. 434AZA-434AZC inserted (with effect in accordance with Sch. 23 para. 3(2) of the amending Act) by Finance Act 2009 (c. 10), Sch. 23 para. 3(1)
F1279Ss. 434AZA-434AZC omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 31 (with Sch. 17)
434AZBAdditions to non-profit funds: amount of loss reductionU.K.
F1280. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1278Ss. 434AZA-434AZC inserted (with effect in accordance with Sch. 23 para. 3(2) of the amending Act) by Finance Act 2009 (c. 10), Sch. 23 para. 3(1)
F1280Ss. 434AZA-434AZC omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 31 (with Sch. 17)
434AZCSections 434AZA and 434AZB: supplementaryU.K.
F1281. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1278Ss. 434AZA-434AZC inserted (with effect in accordance with Sch. 23 para. 3(2) of the amending Act) by Finance Act 2009 (c. 10), Sch. 23 para. 3(1)
F1281Ss. 434AZA-434AZC omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 31 (with Sch. 17)
[F1282434B Treatment of interest and annuities.U.K.
(1)F1283. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1284. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1282S. 434B inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 21(1) (with Sch. 8 para. 55(2))
F1283S. 434B(1) repealed (with effect in accordance with s. 165(4)(5) of the repealing Act) by Finance Act 1996 (c. 8), s. 165(3), Sch. 41 Pt 5(25), Note (with Sch. 14 para. 24)
F1284S. 434B(2) repealed (with effect in accordance with s. 67(7), Sch. 18 Pt. 6(6) Note of the repealing Act) by Finance Act 1997 (c. 16), s. 67(4), Sch. 18 Pt. 6(6)
[F1285434C Interest on repayment of advance corporation tax.U.K.
F1286. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1285S. 434C inserted (with effect in accordance with Sch. 8 paras. 54, 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 22 (with Sch. 8 para. 55(2))
F1286S. 434C repealed (with effect in accordance with Sch. 3 para. 26(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 26(1), Sch. 27 Pt. 3(2), Note
[F1287434D Capital allowances: management assets.U.K.
F1288. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1287Ss. 434D, 434E inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 23(1) (with Sch. 8 para. 55(2))
F1288S. 434D repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 39, Sch. 4
434E Capital allowances: investment assets.U.K.
F1289. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1287Ss. 434D, 434E inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 23(1) (with Sch. 8 para. 55(2))
F1289S. 434E repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 39, Sch. 4
F1290435 Taxation of gains reserved for policy holders and annuitants.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1290S. 435 repealed (with effect in accordance with s. 84(5)(b) of the repealing Act) by Finance Act 1989 (c. 26), s. 84(4), Sch. 8 para. 5, Sch. 17 Pt. IV, Note 3 (with s. 84(6))
436[F1291Pension business]: separate charge on profits.U.K.
F1292. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1291Words in s. 436 sidenote substituted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 51(5) (with Sch. 8 para. 55(2))
F1292S. 436 repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 24, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
[F1293436AGross roll-up business: separate charge on profitsU.K.
F1294. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1293Ss. 436A, 436B inserted (with effect in accordance with s. 38(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 7 para. 25 (with Sch. 7 Pt. 2)
F1294S. 436A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 32 (with Sch. 17)
436BGains referable to gross roll-up business not to be chargeable gainsU.K.
F1295. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1293Ss. 436A, 436B inserted (with effect in accordance with s. 38(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 7 para. 25 (with Sch. 7 Pt. 2)
F1295S. 436B omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 33 (with Sch. 17)
437 General annuity business.U.K.
F1296. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1296Ss. 437, 437A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 34 (with Sch. 17)
[F1297437A Meaning of “steep-reduction annuity” etc.U.K.
F1298. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1297S. 437A inserted (with effect in accordance with s. 67(8) of the amending Act) by Finance Act 1997 (c. 16), s. 67(3)
F1298Ss. 437, 437A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 34 (with Sch. 17)
438 Pension business: exemption from tax.U.K.
F1299. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1299S. 438 omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 35 (with Sch. 17)
[F1300438A Pension business: payments on account of tax credits and deducted tax.U.K.
F1301. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1300S. 438A inserted (2.10.1992) by Finance Act 1991 (c. 31, SIF 63:1), s. 49(1); S.I. 1992/1746, art.2
F1301S. 438A repealed (with effect in accordance with s. 87(2)(5) of the repealing Act) by Finance Act 2001 (c. 9), s. 87(1), Sch. 33 Pt. 2(12)
[F1302438B Income or gains arising from property investment LLPU.K.
F1303. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1302Ss. 438B, 438C inserted (6.4.2001) by Finance Act 2001 (c. 9), s. 76, Sch. 25 para. 5
F1303S. 438B repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 27, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
438C Determination of policy holders’ share for purposes of s.438BU.K.
F1304. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1302Ss. 438B, 438C inserted (6.4.2001) by Finance Act 2001 (c. 9), s. 76, Sch. 25 para. 5
F1304S. 438C repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 28, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
439 Restricted government securities.U.K.
F1305. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1305S. 439 repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 29, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
[F1306439A Taxation of pure reinsurance business.U.K.
F1307. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1306S. 439A inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 26 (with Sch. 8 para. 55(2))
F1307S. 439A repealed (with effect in accordance with s. 39(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 8 para. 7, Sch. 27 Pt. 2(8), Note (with Sch. 8 Pt. 2)
[F1308439B Life reinsurance business: separate charge on profits.U.K.
F1309. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1308S. 439B inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 27(1) (with Sch. 8 para. 55(2))
F1309S. 439B repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 30, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
440 Transfers of assets etc.U.K.
F1310. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1310S. 440 omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 36 (with Sch. 17)
[F1311440A Securities.U.K.
F1312. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1311Ss. 440, 440A substituted for s. 440 (1.1.1990) by Finance Act 1990 (c. 29), Sch. 6 paras. 8, 11(2) (with Sch. 6 para. 12)
F1312S. 440A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 37 (with Sch. 17)
[F1313440B Modifications where tax charged under [F1314section 35 of CTA 2009].U.K.
F1315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1313S. 440B inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 28(1) (with Sch. 8 para. 55(2))
F1314Words in s. 440B title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 138(5) (with Sch. 2 Pts. 1, 2)
F1315S. 440B omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 38 (with Sch. 17)
[F1316440CModifications for change of tax basisU.K.
F1317. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1316S. 440C inserted (with effect in accordance with s. 39(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 8 para. 9 (with Sch. 8 Pt. 2)
F1317S. 440C omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 39 (with Sch. 17)
[F1318440DModifications in relation to BLAGAB group reinsurersU.K.
F1319. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1318S. 440D inserted (27.12.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Insurance Companies (Taxation of Reinsurance Business) (Corporation Tax Acts) (Amendment) Order 2007 (S.I. 2007/3430), art. 3(2)
F1319S. 440D omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 40 (with Sch. 17)
441 Overseas life assurance business.U.K.
F1320. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1320S. 441 repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 34, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
[F1321441A Section 441: distributions.U.K.
(1)F1322. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1324(3)F1323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F1323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F1323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(7)F1323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(8)F1323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1321Ss. 441, 441A substituted for s. 441 by Finance Act 1990 (c. 29), Sch.7 paras. 3, 10
F1322S. 441A(1) repealed (with effect in accordance with Sch. 3 para. 9(4) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 3 para. 9(2), Sch. 8 Pt. 2(6), Note
F1323S. 441A(2)-(8) repealed (with effect in accordance with Sch. 4 para. 28(2), Sch. 8 Pt. 2(10) Note of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 4 para. 28(1), Sch. 8 Pt. 2(10)
F1324S. 441A(3)-(5) substituted for s. 441A(3)-(6) (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 31 (with Sch. 8 para. 55(2))
[F1325441B Treatment of UK land.U.K.
F1326. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1325S. 441B inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 32 (with Sch. 8 para. 55(2))
F1326S. 441B repealed (13.8.2007 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Insurance Companies (Overseas Life Assurance Business) (Excluded Business) (Amendment) Regulations 2007 (S.I. 2007/2086), regs. 1(1), 6(2)(a)
442 Overseas business of U.K. companies.U.K.
F1327. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1327S. 442 omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 41 (with Sch. 17)
[F1328442A Taxation of investment return where risk reinsured.U.K.
F1329. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1328S. 442A inserted (with effect in accordance with Sch. 8 para. 57(1) of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 34 (with Sch. 8 paras. 55(2), 57(2))
F1329S. 442A omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 42 (with Sch. 17)
443 Life policies carrying rights not in money.U.K.
F1330. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1330S. 443 repealed (19.7.2007) by Finance Act 2007 (c. 11), Sch. 10 para. 16(3)(d), Sch. 27 Pt. 2(10), Note
444 Life policies issued before 5th August 1965.U.K.
F1331. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1331S. 444 repealed (19.7.2007) by Finance Act 2007 (c. 11), Sch. 10 para. 16(3)(e), Sch. 27 Pt. 2(10), Note
[F1332444A Transfers of business.U.K.
F1333. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1332S. 444A inserted (with effect in accordance with Sch. 9 para. 7 of the amending Act) by Finance Act 1990 (c. 29), Sch. 9 para. 4
F1333Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1334444AZATransfers of life assurance business: [F1335gross roll-up business] losses of the transferorU.K.
F1336. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1334Ss. 444AZA, 444AZB inserted (19.2.2008 with effect in accordance with art. 1(5) of the amending S.I.) by The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), art. 9
F1335Words in s. 444AZA title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 142(5) (with Sch. 2 Pts. 1, 2)
F1336Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
444AZBTransfers of life assurance business: [F1337trade] losses of the transferorU.K.
F1338. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1334Ss. 444AZA, 444AZB inserted (19.2.2008 with effect in accordance with art. 1(5) of the amending S.I.) by The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), art. 9
F1337Word in s. 444AZB title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 143(5) (with Sch. 2 Pts. 1, 2)
F1338Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1339444AATransfers of business: deemed periodical returnsU.K.
F1340. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1339S. 444AA inserted (with effect in accordance with Sch. 33 para. 18(2) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 18(1)
F1340Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1341444AB[F1342Transfer schemes: transferor]U.K.
F1343. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1341S. 444AB inserted (with effect in accordance with Sch. 33 para. 19(2) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 19(1)
F1342S. 444AB heading substituted (19.2.2008 with effect in accordance with art. 1(4) of the amending S.I.) by virtue of The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), arts. 1(1), 11(6)
F1343Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17) (subject to amendments to s. 444AB by Financial Services Act 2012 (c. 21), s. 122(3), Sch. 18 para. 58(6); S.I. 2013/423, art. 3, Sch.)
[F1344444ABA[F1345Non long-term fund transferred assets]U.K.
F1346. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1344S. 444ABA inserted (with effect in accordance with Sch. 7 para. 3(2) of the amending Act) by Finance Act 2004 (c. 12), Sch. 7 para. 3(1)
F1345S. 444ABA heading substituted (with effect in accordance with s. 15(11) of the amending Act) by Finance (No. 3) Act 2010 (c. 33), s. 15(9)
F1346Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1347444ABAANon-profit fund transferred assetsU.K.
F1348. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1347S. 444ABAA inserted (with effect in accordance with s. 15(11) of the amending Act) by Finance (No. 3) Act 2010 (c. 33), s. 15(10)
F1348Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1349444ABBRetained assetsU.K.
F1350. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1349Ss. 444AB-444ABC substituted for ss. 444AB, 444ABA (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 4(1); S.I. 2008/379, art. 2
F1350Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1351444ABBATransfers of business: election for transferee to pay tax of transferorU.K.
F1352. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1351S. 444ABBA inserted (19.2.2008 with effect in accordance with art. 1(4) of the amending S.I.) by The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), art. 14
F1352Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1353444ABCTransfer scheme transferring part of business: transferorU.K.
F1354. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1353Ss. 444AB-444ABC substituted for ss. 444AB, 444ABA (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 4(1); S.I. 2008/379, art. 2
F1354S. 444ABC omitted (19.2.2008 with effect in accordance with art. 1(4) of the repealing S.I.) by virtue of The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), arts. 1(1), 15
[F1355444ABDTransferor's period of account including transferU.K.
F1356. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1355S. 444ABD inserted (with effect in accordance with Sch. 9 para. 17(4) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 5
F1356Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1357444AC[F1358Transfer schemes: reduction of income of transferee]U.K.
F1359. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1357Ss. 444AC-444AE inserted (with effect in accordance with Sch. 33 para. 20(3)(4) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 20(1)
F1358S. 444AC heading substituted (19.2.2008 with effect in accordance with art. 1(4) of the amending S.I.) by virtue of The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), arts. 1(1), 17(8)
F1359Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1360444ACZATransfer schemes transferring part of business: reduction in income of transfereeU.K.
F1361. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1357Ss. 444AC-444AE inserted (with effect in accordance with Sch. 33 para. 20(3)(4) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 20(1)
F1360Ss. 444AC, 444ACZA substituted for s. 444AC (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 6(1); S.I. 2008/379, art. 2
F1361S. 444ACZA omitted (19.2.2008 with effect in accordance with art. 1(4) of the repealing S.I.) by virtue of The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), arts. 1(1), 18
[F1362444ACATransfers of business: transferor shares are assets of transferee's long-term insurance fund etcU.K.
F1363. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1357Ss. 444AC-444AE inserted (with effect in accordance with Sch. 33 para. 20(3)(4) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 20(1)
F1362S. 444ACA inserted (with effect in accordance with Sch. 9 para. 8(2) of the amending Act) by Finance (No. 2) Act 2005 (c. 22), Sch. 9 para. 8(1)
F1363S. 444ACA repealed (with effect in accordance with Sch. 10 para. 17(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 10 para. 2(2), Sch. 27 Pt. 2(10), Note
444ADTransfers of business: modification of s.83(2B) FA 1989U.K.
F1364. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1357Ss. 444AC-444AE inserted (with effect in accordance with Sch. 33 para. 20(3)(4) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 20(1)
F1364S. 444AD repealed (with effect in accordance with Sch. 9 para. 17(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 9 para. 7(1), Sch. 27 Pt. 2(9), Note; S.I. 2008/379, art. 2
444AETransfers of business: FAFTSU.K.
F1365. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1357Ss. 444AC-444AE inserted (with effect in accordance with Sch. 33 para. 20(3)(4) of the amending Act) by Finance Act 2003 (c. 14), Sch. 33 para. 20(1)
F1365Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1366444AEATransfer schemes: anti-avoidance ruleU.K.
F1367. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1367Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
444AEB[F1368Life assurance trade profits] advantage: transferorU.K.
F1369. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1368Words in s. 444AEB title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 146(5) (with Sch. 2 Pts. 1, 2)
F1369Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
444AEC[F1370Life assurance trade profits] advantage: transfereeU.K.
F1371. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1370Words in s. 444AEC title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 147(5) (with Sch. 2 Pts. 1, 2)
F1371Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1372444AECAParts of transfer scheme arrangements: anti-avoidance ruleU.K.
F1373. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1372Ss. 444AECA-444AECC inserted (19.2.2008 with effect in accordance with art. 1(4) of the amending S.I.) by The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), art. 22
F1373Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
444AECBParts of transfer scheme arrangements: [F1374life assurance trade profits] advantage transferorU.K.
F1375. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1372Ss. 444AECA-444AECC inserted (19.2.2008 with effect in accordance with art. 1(4) of the amending S.I.) by The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), art. 22
F1374Words in s. 444AECB title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 149(7) (with Sch. 2 Pts. 1, 2)
F1375Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
444AECCParts of transfer scheme arrangements: [F1376life assurance trade profits] advantage transfereeU.K.
F1377. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1372Ss. 444AECA-444AECC inserted (19.2.2008 with effect in accordance with art. 1(4) of the amending S.I.) by The Insurance Business Transfer Schemes (Amendment of the Corporation Tax Acts) Order 2008 (S.I. 2008/381), art. 22
F1376Words in s. 444AECC title substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 150(6) (with Sch. 2 Pts. 1, 2)
F1377Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
444AEDClearance: no avoidance or group advantageU.K.
F1378. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1366Ss. 444AEA-444AED inserted (with effect in accordance with Sch. 9 para. 17(2) of the amending Act) by Finance Act 2007 (c. 11), Sch. 9 para. 8(1); S.I. 2008/379, art. 2
F1378Ss. 444A-444AED omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 43 (with Sch. 17)
[F1379Surpluses of mutual and former mutual businessesU.K.
Textual Amendments
F1379Ss. 444AF-444AL and preceding cross-heading inserted (with effect in accordance with Sch. 11 para. 5(2)-(14) of the amending Act) by Finance Act 2006 (c. 25), Sch. 11 para. 5(1)
444AFDemutualisation surplus: life assurance businessU.K.
F1380. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1380Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
444AGSection 444AF: “demutualisation transfer surplus”U.K.
F1381. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1381Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
444AHModification of section 444AG etc for [F1382gross roll-up] businessesU.K.
F1383. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1382Words in s. 444AH heading substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 153 (with Sch. 2 Pts. 1, 2)
F1383Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
444AISection 444AF: “reduction in company's unappropriated surplus”U.K.
F1384. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1384Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
444AJSections 444AF and 444AK: “relevant receipts reduction”U.K.
F1385. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1385Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
444AK[F1386Mutual surplus: gross roll-up business]U.K.
F1387. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1386S. 444AK heading substituted (with effect in accordance with s. 38(2) of the amending Act) by virtue of Finance Act 2007 (c. 11), Sch. 7 para. 38(5) (with Sch. 7 Pt. 2)
F1387Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
444ALInterpretation of sections 444AF to 444AKU.K.
F1388. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1388Ss. 444AF-444AL omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 44 (with Sch. 17)
[F1389 Provisions applying in relation to overseas life insurance companiesU.K.
F1390444B Modification of Act in relation to overseas life insurance companies.U.K.
F1391. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1390S. 444B and cross heading inserted (27.7.1993) by 1993 c. 34, s. 97(1)
F1391S. 444B repealed (31.12.2006 with effect in accordance with reg. 1 of the repealing S.I.) by The Overseas Life Insurance Companies Regulations 2006 (S.I. 2006/3271), reg. 43(1), Sch. Pt. 1
[F1392 Equalisation reservesU.K.
Textual Amendments
F1392Ss. 444BA-444BD and preceding cross-heading inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 166, Sch. 32 para. 1
444BA Equalisation reserves for general business.U.K.
F1393. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1393Ss. 444BA-444BD repealed (with effect in accordance with s. 26(3)-(9) of the repealing Act) by Finance Act 2012 (c. 14), s. 26(1); S.I. 2015/1999, art. 2
444BB Modification of s. 444BA for mutual or overseas business and for non-resident companies.U.K.
F1394. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1394Ss. 444BA-444BD repealed (with effect in accordance with s. 26(3)-(9) of the repealing Act) by Finance Act 2012 (c. 14), s. 26(1); S.I. 2015/1999, art. 2
444BC Modification of s. 444BA for non-annual accounting etc.U.K.
F1395. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1395Ss. 444BA-444BD repealed (with effect in accordance with s. 26(3)-(9) of the repealing Act) by Finance Act 2012 (c. 14), s. 26(1); S.I. 2015/1999, art. 2
444BD Application of s. 444BA rules to other equalisation reserves.U.K.
F1396. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1396Ss. 444BA-444BD repealed (with effect in accordance with s. 26(3)-(9) of the repealing Act) by Finance Act 2012 (c. 14), s. 26(1); S.I. 2015/1999, art. 2
444C Modification of section 440.U.K.
F1397. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1397Ss. 444C-444E repealed (with effect in accordance with Sch. 8 paras. 55, 57(1) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(5), Notes 1, 2
444D Qualifying distributions, tax credits, etc.U.K.
F1398. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1398Ss. 444C-444E repealed (with effect in accordance with Sch. 8 paras. 55, 57(1) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(5), Notes 1, 2
444E Income from investments attributable to BLAGAB, etc.U.K.
F1399. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1399Ss. 444C-444E repealed (with effect in accordance with Sch. 8 paras. 55, 57(1) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(5), Notes 1, 2
Provisions applying only to overseas life insurance companiesU.K.
F1400445. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1400S. 445 repealed (27.7.1993 with effect as mentioned in s. 103(3)(4) of the amending Act) by 1993 c. 34, ss. 103(2)(a)(3)(4), 213, Sch. 23 Pt. III(9), note
446 Annuity business.U.K.
F1401(1). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1402(2). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1402(3). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1403(4). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1401S. 446(1) repealed (27.7.1993 with effect as mentioned in s. 103(3)(4) of the amending Act) by 1993 c. 34, ss. 103(2)(b)(3)(4), 213, Sch. 23 Pt. III(9), note
F1402S. 446(2)(3) repealed (for accounting periods beginning on or after 1.1.1992) by Finance Act 1991 (c. 31, SIF 63:1), ss. 48, 123, Sch. 7 para. 7(1)(b), Sch. 19 Pt. V, Note 3
F1403S. 446(4) repealed by Finance Act 1990 (c. 29, SIF 63:1), s. 132, Sch. 19 Pt. IV.
447
F1404(1). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1404(2). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1405(3). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1404(4). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1404S. 447(1)(2) and (4) repealed (27.7.1993 with effect as mentioned in s. 103(3)(4) of the amending Act) by 1993 c. 34, ss. 103(2)(c)(3)(4), 213, Sch. 23 Pt. III(9), note
F1405S. 447(3) repealed (for accounting periods beginning on or after 1.1.1992) by Finance Act 1991 (c. 31, SIF 63:1), ss. 48, 123, Sch. 7 paras. 7(3), 18, Sch. 19 Pt. V, Note 3
F1406448. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1406S. 448 repealed (27.7.1993 with effect as mentioned in s. 103(3)(4) of the amending Act) by 1993 c. 34, ss. 103(2)d), 213, Sch. 23 Pt.III (9), note
F1407449. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1407S. 449 repealed (27.7.1993 with effect as mentioned in s. 103(3)(4) of the amending Act) by 1993 c. 34, ss. 103(2)(e),213, Sch. 23 Pt. III (9), note
UnderwritersU.K.
F1408450. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1408Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12) notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, Sch. 23 Pt. III (12), notes 1 and 5
F1409451. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1409Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the repealing Act) by 1993 c. 34, s. 213, Sch. 23 Pt. III (12), notes. 1 and 5
F1410452. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1410SS. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, Sch. 23 Pt. III (12), notes 1 and 5
F1411453. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1411Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, SCh. 23, Pt.III (12), notes 1 and 5)
F1412454. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1412Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, Sch. 23 Pt.III (12), notes 1 and 5
F1413455. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1413Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, Sch. 23 Pt. III (12), notes 1 and 5
F1414456. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1414Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, Sch. 23 Pt.III (12), notes 1 and 5
F1415457. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F1415Ss. 450-457 repealed (27.7.1993 with effect as mentioned in Sch. 23 Pt. III (12), notes 1 and 5 of the amending Act) by 1993 c. 34, s. 213, Sch. 23 Pt. III (12), notes 1 and 5
Capital redemption businessU.K.
458 Capital redemption business.U.K.
F1416. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1416Ss. 458, 458A repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 39, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
[F1417458A Capital redemption business: power to apply life assurance provisions.U.K.
F1418. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1417S. 458A inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 168(3)
F1418Ss. 458, 458A repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 39, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
CHAPTER IIU.K. FRIENDLY SOCIETIES, TRADE UNIONS AND EMPLOYERS’ ASSOCIATIONS
Unregistered friendly societiesU.K.
459 Exemption from tax.U.K.
F1419. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1419S. 459 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 2
Registered friendly societiesU.K.
460 Exemption from tax in respect of life or endowment business.U.K.
F1420. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1420S. 460 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 3
461 Taxation in respect of other business.U.K.
F1421. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1421S. 461 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 4
[F1422461A Taxation in respect of other business: incorporated friendly societies qualifying for exemption.U.K.
F1423. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1422Ss. 461A-461C inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para.7; S.I. 1993/236, art.2
F1423Ss. 461A-461C omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 5
F1424461B Taxation in respect of other business: incorporated friendly societies etc.U.K.
F1425. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1424Ss. 461A-461C inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para.7; S.I. 1993/236, art. 2
F1425Ss. 461A-461C omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 5
F1426461C Taxation in respect of other business: withdrawal of “qualifying” status from incorporated friendly society.U.K.
F1427. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1426Ss. 461A-461C inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para.7; S.I. 1993/236, art. 2
F1427Ss. 461A-461C omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 5
[F1428461DTransfers of other businessU.K.
F1429. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1428S. 461D inserted (with effect in accordance with Sch. 18 para. 3(2) of the amending Act) by Finance Act 2008 (c. 9), Sch. 18 para. 3(1)
F1429S. 461D omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 6
462 Conditions for tax exempt business.U.K.
F1430. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1430S. 462 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 7
[F1431462A Election as to tax exempt business.U.K.
F1432. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1431S. 462A inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 50, Sch. 9 para. 2
F1432S. 462A omitted (21.7.2008) by virtue of Finance Act 2008 (c. 9), Sch. 18 para. 5(1)(b)
463[F1433Long-term] business: application of the Corporation Tax Acts.U.K.
F1434. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1433Words in s. 463 heading substituted (21.7.2008) by Finance Act 2008 (c. 9), Sch. 18 para. 4
F1434S. 463 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 8
464 Maximum benefits payable to members.U.K.
F1435. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1435S. 464 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 9
465 Old societies.U.K.
F1436. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1436S. 465 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 10
[F1437465A Assets of branch of registered friendly society to be treated as assets of society after incorporation.U.K.
F1438. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1437S. 465A inserted (19.12.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para.13, 22; S.I. 1993/236, art.2
F1438S. 465A omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 11
466 Interpretation of Chapter II.U.K.
F1439. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1439S. 466 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 12
Trade unions and employers’ associationsU.K.
467 Exemption for trade unions and employers’ associations.U.K.
F1440. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1440S. 467 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 52, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER IIIU.K. UNIT TRUST SCHEMES, DEALERS IN SECURITIES ETC.
Unit trust schemesU.K.
468 Authorised unit trusts.U.K.
F1441. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1441S. 468 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 53, Sch. 3 Pt. 1 (with Sch. 2)
[F1442468AA Authorised unit trusts: futures and options.U.K.
F1443. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1442S. 468AA inserted by Finance Act 1990 (c. 29), s. 81(1)(5)
F1443S. 468AA repealed (with effect in accordance with s. 83(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 27 para. 6, Sch. 40 Pt. 3(13), Note (with Sch. 28)
[F1444468A Certified unit trusts.U.K.
F1445. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1444Ss. 468A-468C inserted by Finance Act 1989 (c. 26), s. 78
F1445Ss. 468A-468D repealed by Finance Act 1990 (c. 29), s. 52, Sch. 19 Pt. 4, Note 7
[F1446468AOpen-ended investment companiesU.K.
F1447. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1446S. 468A inserted (20.7.2005) by Finance (No. 2) Act 2005 (c. 22), s. 16
F1447S. 468A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 54, Sch. 3 Pt. 1 (with Sch. 2)
F1448468B Certified unit trusts: corporation tax.U.K.
F1449. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1448Ss. 468A-468C inserted by Finance Act 1989 (c. 26), s. 78
F1449Ss. 468A-468D repealed by Finance Act 1990 (c. 29), s. 52, Sch. 19 Pt. 4, Note 7
F1450468C Certified unit trusts: distributions.U.K.
F1451. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1450Ss. 468A-468C inserted by Finance Act 1989 (c. 26), s. 78
F1451Ss. 468A-468D repealed by Finance Act 1990 (c. 29), s. 52, Sch. 19 Pt. 4, Note 7
[F1452468D Funds of funds: distributions.U.K.
F1453. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1452S. 468D inserted by Finance Act 1989 (c. 26), s. 79
F1453Ss. 468A-468D repealed by Finance Act 1990 (c. 29), s. 52, Sch. 19 Pt. 4, Note 7
[F1454468E Authorised unit trusts: corporation tax.U.K.
F1455. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1454Ss. 468E-468G inserted by Finance Act 1990 (c. 29), s. 51
F1455S. 468E repealed (with effect in accordance with Sch. 6 paras. 10(3), 28 of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(1), Note 1
[F1456468EE Corporation tax: cases where lower rate applies.U.K.
F1457. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1456S. 468EE inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 111(2)
F1457S. 468EE repealed (with effect in accordance with Sch. 6 paras. 10(3), 28 of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(1), Note 1
F1458468F Authorised unit trusts: distributions.U.K.
F1459. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1458Ss. 468E-468G inserted by Finance Act 1990 (c. 29), s. 51
F1459S. 468F repealed (with effect in accordance with Sch. 14 para. 7 of the repealing Act) by Finance Act 1994 (c. 9), Sch. 14 para. 4, Sch. 26 Pt. 5(13), Note
F1460468G Dividends paid to investment trusts.U.K.
F1461. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1460Ss. 468E-468G inserted by Finance Act 1990 (c. 29), s. 51
F1461S. 468G repealed (with effect in accordance with Sch. 14 para. 7 of the repealing Act) by Finance Act 1994 (c. 9), Sch. 14 para. 4, Sch. 26 Pt. 5(13), Note
[F1462 Distributions of authorised unit trusts: generalU.K.
Textual Amendments
F1462Ss. 468H-468R and cross-headings inserted (with effect in accordance with Sch. 14 para. 7 of the amending Act) by Finance Act 1994 (c. 9), Sch. 14 para. 2
468H Interpretation.U.K.
F1463. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1463Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
468I Distribution accounts.U.K.
F1464. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1464Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
Dividend and foreign income distributionsU.K.
468J Dividend distributions.U.K.
F1465. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1465Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
468K Foreign income distributions.U.K.
F1466. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1466S. 468K repealed (with effect in accordance with s. 36, Sch. 6 para. 8(9) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 8(4), Sch. 8 Pt. 2(11)
Interest distributionsU.K.
468L Interest distributions.U.K.
F1467. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1467Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
[F1468468M Cases where no obligation to deduct taxU.K.
F1469. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1468S. 468M substituted for ss. 468M, 468N (with effect in accordance with s. 203(14) of the amending Act) by Finance Act 2003 (c. 14), s. 203(3)
F1469Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
468N. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
468O Residence condition [F1470and reputable intermediary condition].U.K.
F1471. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1470Words in s. 468O sidenote inserted (with effect in accordance with s. 203(14) of the amending Act) by Finance Act 2003 (c. 14), s. 203(7)
F1471Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
468P Residence declarations.U.K.
F1472. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1472Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
[F1473468PASection 468O(1A): consequences of reasonable but incorrect beliefU.K.
F1474. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1473Ss. 468PA, 468PB inserted (with effect in accordance with s. 203(14) of the amending Act) by Finance Act 2003 (c. 14), s. 203(9)
F1474Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
468PBRegulations supplementing sections 468M to 468PAU.K.
F1475. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1473Ss. 468PA, 468PB inserted (with effect in accordance with s. 203(14) of the amending Act) by Finance Act 2003 (c. 14), s. 203(9)
F1475Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
Distributions to corporate unit holderU.K.
468Q Dividend distribution to corporate unit holder.U.K.
F1476. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1476Ss. 468H-468Q repealed (in force in accordance with S.I. 2006/982, art. 2) by Finance (No. 2) Act 2005 (c. 22), ss. 17(1)(a), 19(1), Sch. 11 Pt. 2(3), Note 2
468R Foreign income distribution to corporate unit holder.U.K.
F1477. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1477S. 468R repealed (with effect in accordance with s. 36, Sch. 6 para. 8(9) of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 6 para. 8(7), Sch. 8 Pt. 2(11), Note
469 Other unit trusts.U.K.
F1478. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1478S. 469 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 55, Sch. 3 Pt. 1 (with Sch. 2)
[F1479469A Court common investment funds.U.K.
F1480. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1479S. 469A inserted (with effect in accordance with s. 68(3)-(5) of the amending Act) by Finance Act 1999 (c. 16), s. 68(1)
F1480S. 469A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 56, Sch. 3 Pt. 1 (with Sch. 2)
470 Transitional provisions relating to unit trusts.U.K.
(1)F1481. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1482(2). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1481. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1481S. 470(1)(3) repealed (31.7.1998) by Finance Act 1998 (c. 36), Sch. 27 Pt. 3(23)
F1482S. 470(2) ceased to have effect (29.4.1988) by virtue of s. 470(3) below and S.I. 1988/745, art. 2
Dealers in securities, banks and insurance businessesU.K.
471 Exchange of securities in connection with conversion operations, nationalisation etc.U.K.
F1483. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1483S. 471 repealed (with effect in accordance with s. 101(3) of the repealing Act) by Finance Act 1998 (c. 36), s. 101(1), Sch. 27 Pt. 3(23), Note 1
472 Distribution of securities issued in connection with nationalisation etc.U.K.
F1484. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1484S. 472 repealed (with effect in accordance with s. 101(4) of the repealing Act) by Finance Act 1998 (c. 36), s. 101(2), Sch. 27 Pt. 3(23), Note 2
[F1485472ATrading profits etc. from securities: taxation of amounts taken to reservesU.K.
F1486. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1485S. 472A inserted (with effect in accordance with s. 54(2) of the amending Act) by Finance Act 2004 (c. 12), s. 54 (as amended (retrospectively) by Finance Act 2005 (c.7), Sch. 4 para. 50, Sch. 11 Pt. 2(7))
F1486S. 472A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 158, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
473 Conversion etc. of securities held as circulating capital.U.K.
F1487. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1487S. 473 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 159, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
474 Treatment of tax-free income.U.K.
(1)F1488. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1489. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1490(3)F1488. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1488S. 474(1)(3) repealed (with effect in accordance with Sch. 7 para. 32-35, Sch. 41 Pt. 5(2) Note of the repealing Act) by Finance Act 1996 (c. 8). Sch. 7 para. 18, Sch. 41 Pt. 5(2)
F1489S. 474(2) repealed (with effect in accordance with s. 154(9) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 28 para. 2, Sch. 41 Pt. 5(18), Note
F1490S. 474(3) inserted (with effect in accordance with Sch. 8 para. 55 of the amending Act) by Finance Act 1995 (c. 4), Sch. 8 para. 25(2)
475 Tax-free Treasury securities: exclusion of interest on borrowed money.U.K.
F1491. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1491S. 475 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 41, Sch. 10 Pt. 12 (with Sch. 9)
CHAPTER IVU.K. BUILDING SOCIETIES, BANKS, SAVINGS BANKS, INDUSTRIAL AND PROVIDENT SOCIETIES AND OTHERS
476 Building societies: regulations for payment of tax.U.K.
F1492. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1492S. 476 repealed by Finance Act 1990 (c. 29), Sch. 5 para. 2, Sch. 19 Pt. 4, Note 8
477 Investments becoming or ceasing to be relevant building society investments.U.K.
F1493. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1493S. 477 repealed by Finance Act 1990 (c. 29), Sch. 5 para. 3, Sch. 19 Pt. 4, Note 8
[F1495477A Building societies: [F1494loan relationships].U.K.
F1496. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1494Words in s. 477A sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 88(7) (with Sch. 2)
F1495S. 477A inserted (with effect in accordance with Sch. 5 para. 4(2) of the amending Act) by Finance Act 1990 (c. 29), Sch. 5 para. 4(1)
F1496S. 477A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 57, Sch. 3 Pt. 1 (with Sch. 2)
[F1497477B Building societies: incidental costs of issuing qualifying shares.U.K.
F1498. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1498S. 477B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
478 Building societies: time for payment of tax.U.K.
F1499. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1499S. 478 repealed (with effect in accordance with s. 199(2) of the repealing Act) by Finance Act 1994 (c. 9), Sch. 26 Pt. 5(23), Note 4; S.I. 1998/3173, art. 2
479 Interest paid on deposits with banks etc.U.K.
F1500. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1500S. 479 repealed by Finance Act 1990 (c. 29), Sch. 5 para. 5, Sch. 19 Pt. 4, Note 8
480 Deposits becoming or ceasing to be composite rate deposits.U.K.
F1501. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1501S. 480 repealed by Finance Act 1990 (c. 29), Sch. 5 para. 6, Sch. 19 Pt. 4, Note 8
[F1502480A Relevant deposits: deduction of tax from interest payments.U.K.
F1503. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1502Ss. 480A-480C inserted (with effect in accordance with Sch. 5 para. 7(2) of the amending Act) by Finance Act 1990 (c. 29), Sch. 5 para. 7(1)
F1503Ss. 480A-482 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 89, Sch. 3 Pt. 1 (with Sch. 2)
[F1504480B Relevant deposits: exception from section 480A.U.K.
F1505. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1504Ss. 480A-480C inserted (with effect in accordance with Sch. 5 para. 7(2) of the amending Act) by Finance Act 1990 (c. 29), Sch. 5 para. 7(1)
F1505Ss. 480A-482 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 89, Sch. 3 Pt. 1 (with Sch. 2)
[F1506480C Relevant deposits: computation of tax on interest.U.K.
F1507. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1506Ss. 480A-480C inserted (with effect in accordance with Sch. 5 para. 7(2) of the amending Act) by Finance Act 1990 (c. 29), Sch. 5 para. 7(1)
F1507S. 480C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 185, Sch. 3 (with Sch. 2)
481“Deposit-taker”, “deposit” and “relevant deposit”.U.K.
F1508. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1508Ss. 480A-482 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 89, Sch. 3 Pt. 1 (with Sch. 2)
482 Supplementary provisions.U.K.
F1509. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1509Ss. 480A-482 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 89, Sch. 3 Pt. 1 (with Sch. 2)
[F1510482A Audit powers in relation to non-residents.U.K.
F1511. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1510S. 482A inserted by Finance Act 1991 (c. 31, SIF 63:1), s.75
F1511S. 482A repealed (with effect in accordance with s. 145(11), Sch. 40 Pt. 5 Note of the repealing Act) by Finance Act 2000 (c. 17), s. 145(10), Sch. 40 Pt. 5
483 Determination of reduced rate for building societies and composite rate for banks etc.U.K.
F1512(1). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1512(2). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1512(3). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)If the order made under section 26 of the Finance Act 1984 in the year 1987-88 is made in pursuance of subsection (4) of that section, that order shall, notwithstanding that that subsection is not re-enacted by this Act, apply for the purposes of sections 476 and 479 for the year 1988-89.
F1512(5). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1512S. 483(1)-(3)(5) repealed by Finance Act 1990 (c. 29), Sch. 5 para. 12, Sch. 19 Part IV, Note 8
484 Savings banks: exemption from tax.U.K.
F1513. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1513S. 484 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 14 para 29, Sch. 41 Pt. 5(3), Note (with Sch. 15)
485 Savings banks: supplemental.U.K.
F1514. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1514S. 485 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 14 para. 29, Sch. 41 Pt. 5(3), Note (with Sch. 15)
486 Industrial and provident societies and co-operative associations.U.K.
F1515. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1515S. 486 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 58, Sch. 3 Pt. 1 (with Sch. 2)
487 Credit unions.U.K.
F1516. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1516S. 487 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 164, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
488 Co-operative housing associations.U.K.
F1517. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1517S. 488 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 59, Sch. 3 Pt. 1 (with Sch. 2)
489 Self-build societies.U.K.
F1518. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1518S. 489 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 60, Sch. 3 Pt. 1 (with Sch. 2)
490 Companies carrying on a mutual business or not carrying on a business.U.K.
F1519. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1519S. 490 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 61, Sch. 3 Pt. 1 (with Sch. 2)
491 Distribution of assets of body corporate carrying on mutual business.U.K.
F1520. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1520S. 491 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 165, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
CHAPTER VU.K.
Modifications etc. (not altering text)
C36Pt. 12 Ch. 5 modified (27.7.1999) by Finance Act 1999 (c. 16), s. 98
PETROLEUM EXTRACTION ACTIVITIESU.K.
492 Treatment of oil extraction activities etc. for tax purposes.U.K.
F1521. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1521S. 492 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 62, Sch. 3 Pt. 1 (with Sch. 2)
493 Valuation of oil disposed of or appropriated in certain circumstances.U.K.
F1522. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1522S. 493 repealed (the repeal of s. 493(1)-(6) having effect for specified purposes only) (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 63, Sch. 3 Pts. 1, 2 (with Sch. 2); and s. 493(1)-(6) repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 181, Sch. 10 Pt. 6 (with Sch. 9)
494[F1523Loan relationships etc.]U.K.
F1524. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1523S. 494 sidenote substituted (with effect in accordance with s. 38(7)-(13) of the amending Act) by virtue of Finance (No. 2) Act 2005 (c. 22), s. 38(5)
F1524Ss. 494-494A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 64, Sch. 3 Pt. 1 (with Sch. 2)
[F1525494AA Sale and lease-back.U.K.
F1526. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1525S. 494AA inserted (with application in accordance with s. 100(2)(3) of the amending Act) by Finance Act 1999 (c. 16), s. 100(1)
F1526Ss. 494-494A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 64, Sch. 3 Pt. 1 (with Sch. 2)
[F1527494A Computation of amount available for surrender by way of group relief.U.K.
F1528. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1527S. 494A inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 30 (with Sch. 5 para. 73)
F1528Ss. 494-494A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 64, Sch. 3 Pt. 1 (with Sch. 2)
495 Regional development grants.U.K.
F1529. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1529S. 495 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 65, Sch. 3 Pt. 2 (with Sch. 2); and s. 495 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 182, Sch. 10 Pt. 6 (with Sch. 9)
496[F1530Tariff receipts and tax-exempt tariffing receipts]U.K.
F1531. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1530S. 496 sidenote substituted (with effect in accordance with s. 285(7) of the amending Act) by virtue of Finance Act 2004 (c. 12), Sch. 37 para. 11(5)
F1531S. 496 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 66, Sch. 3 Pt. 2 (with Sch. 2); and s. 496 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 183, Sch. 10 Pt. 6 (with Sch. 9)
[F1532496AExploration expenditure supplementU.K.
Schedule 19B to this Act (exploration expenditure supplement) shall have effect.]
Textual Amendments
F1532S. 496A inserted (22.7.2004) by Finance Act 2004 (c. 12), s. 286(2)
[F1533496BRing fence expenditure supplementU.K.
F1534. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1533S. 496B inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(2)
F1534S. 496B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 67, Sch. 3 Pt. 1 (with Sch. 2)
497 Restriction on setting ACT against income from oil extraction activities etc.U.K.
F1535. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1535S. 497 repealed (with effect in accordance with Sch. 3 para. 29(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 29(1), Sch. 27 Pt. 3(2), Note
498 Limited right to carry back surrendered ACT.U.K.
F1536. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1536S. 498 repealed (with effect in accordance with Sch. 3 para. 30(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 30(1), Sch. 27 Pt. 3(2), Note (with Sch. 3 para. 30(3))
499 Surrender of ACT where oil extraction company etc. owned by a consortium.U.K.
F1537. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1537S. 499 repealed (with effect in accordance with Sch. 3 para. 31(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 31(1), Sch. 27 Pt. 3(2), Note
500 Deduction of PRT in computing income for corporation tax purposes.U.K.
F1538. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1538Ss. 500-501B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 68, Sch. 3 Pt. 1 (with Sch. 2)
501 Interest on repayment of PRT.U.K.
F1539. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1539Ss. 500-501B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 68, Sch. 3 Pt. 1 (with Sch. 2)
[F1540501A Supplementary charge in respect of ring fence tradesU.K.
F1541. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1540S. 501A inserted (24.7.2002) by Finance Act 2002 (c. 23), ss. 91, 93
F1541Ss. 500-501B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 68, Sch. 3 Pt. 1 (with Sch. 2)
[F1542501B Assessment, recovery and postponement of supplementary chargeU.K.
F1543. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1542S. 501B inserted (24.7.2002) by Finance Act 2002 (c. 23), ss. 92(1), 93
F1543Ss. 500-501B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 68, Sch. 3 Pt. 1 (with Sch. 2)
502 Interpretation of Chapter V.U.K.
F1544. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1544S. 502 repealed (the repeal of s. 502(1)(2) having effect for specified purposes only) (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 69, Sch. 3 Pts. 1, 2 (with Sch. 2); and s. 502(1)(2) repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 184, Sch. 10 Pt. 6 (with Sch. 9)
[F1545Chapter 5AU.K.Special rules for long funding leases of plant or machinery: corporation tax
Textual Amendments
F1545Pt. 12 Ch. 5A (ss. 502A-502L) inserted (with effect in accordance with Sch. 8 para. 15 of the amending Act) by Finance Act 2006 (c. 25), Sch. 8 para. 11
IntroductoryU.K.
502AScope of Chapter 5AU.K.
F1546. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1546Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
Lessors under long funding finance leasesU.K.
502BLessor under long funding finance lease: rental earningsU.K.
F1547. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1547Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
502CLessor under long funding finance lease: exceptional itemsU.K.
F1548. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1548Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
502DLessor under long funding finance lease making termination paymentU.K.
F1549. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1549Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
Lessors under long funding operating leasesU.K.
502ELessor under long funding operating lease: periodic deductionU.K.
F1550. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1550Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
502FLong funding operating lease: lessor's additional expenditureU.K.
F1551. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1551Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
502GLessor under long funding operating lease: termination of leaseU.K.
F1552. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1552Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
[F1553Lessors under long funding finance or operating leases: avoidance etcU.K.
Textual Amendments
F1553S. 502GA and preceding cross-heading inserted (with effect in accordance with Sch. 20 para. 9(5) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 9(2)
502GACases where ss. 502B to 502G do not apply: plant or machinery held as trading stockU.K.
F1554. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1554Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
[F1555502GBCases where ss. 502B to 502G do not apply: lessor also lessee under non-long funding leaseU.K.
F1556. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1555S. 502GB inserted (with effect in accordance with Sch. 20 para. 9(6) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 9(3)
F1556Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
[F1557502GCCases where ss. 502B to 502G do not apply: other avoidanceU.K.
F1558. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1557S. 502GC inserted (with effect in accordance with Sch. 20 para. 9(7) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 9(4)
F1558Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
[F1559502GDCases where ss 502B to 502G do not apply: filmsU.K.
F1560. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F1559S. 502GD inserted (with effect in accordance with Sch. 33 para. 3 of the amending Act) by Finance Act 2009 (c. 10), Sch. 33 para. 1
F1560Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
Insurance company as lessorU.K.
502HInsurance company as lessorU.K.
F1561. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1561S. 502H omitted (with effect in accordance with Sch. 17 para. 17(12) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 17 para. 17(10)(11)(b)
Lessees under long funding finance leasesU.K.
502ILessee under long funding finance lease: limit on deductionsU.K.
F1562. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1562Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
502JLessee under long funding finance lease: terminationU.K.
F1563. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1563Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
Lessees under long funding operating leasesU.K.
502KLessee under long funding operating leaseU.K.
F1564. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1564Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
Interpretation of ChapterU.K.
502LInterpretation of this ChapterU.K.
F1565. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1565Pt. 12 Ch. 5A (ss. 502A-502L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 70, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER VIU.K. MISCELLANEOUS BUSINESSES AND BODIES
[F1567503 Letting of furnished holiday accommodation treated as a trade for certain [F1566corporation tax] purposes.U.K.
F1568. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1566Words in s. 503 sidenote inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 195(5) (with Sch. 2)
F1567S. 503 substituted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 42 (with Sch. 5 para. 73)
F1568S. 503 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 71, Sch. 3 Pt. 1 (with Sch. 2)
504 Supplementary provisions.U.K.
F1569. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1569S. 504 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 173, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1570504ALetting of furnished holiday accommodation treated as trade for certain income tax purposesU.K.
F1571. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1570S. 504A inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 197 (with Sch. 2)
F1571S. 504A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 93, Sch. 3 Pt. 1 (with Sch. 2)
505[F1572Charitable companies]: general.U.K.
F1573. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1572Words in s. 505 sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 94(10) (with Sch. 2)
F1573S. 505 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 72, Sch. 3 Pt. 1 (with Sch. 2)
506[F1574Charitable and non-charitable expenditure]U.K.
F1575. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1574S. 506(3) heading substituted (with effect in accordance with s. 55(5) of the amending Act) by Finance Act 2006 (c. 25), s. 55(2)(g)
F1575S. 506 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 73, Sch. 3 Pt. 1 (with Sch. 2)
[F1576506ATransactions with substantial donorsU.K.
F1577. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1576Ss. 506A-506C inserted (with effect in accordance with s. 54(2)(3) of the amending Act) by Finance Act 2006 (c. 25), s. 54(1)
F1577S. 506A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 74, Sch. 3 Pt. 1 (with Sch. 2)
506BSection 506A: exceptionsU.K.
F1578. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1576Ss. 506A-506C inserted (with effect in accordance with s. 54(2)(3) of the amending Act) by Finance Act 2006 (c. 25), s. 54(1)
F1578S. 506B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 75, Sch. 3 Pt. 1 (with Sch. 2)
506CSections 506A and 506B: supplementalU.K.
F1579. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1576Ss. 506A-506C inserted (with effect in accordance with s. 54(2)(3) of the amending Act) by Finance Act 2006 (c. 25), s. 54(1)
F1579S. 506C repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 76, Sch. 3 Pt. 1 (with Sch. 2)
507 The National Heritage Memorial Fund, the Historic Buildings and Monuments Commission for England and the British Museum.U.K.
F1580. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1580S. 507 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 77, Sch. 3 Pt. 1 (with Sch. 2)
508 Scientific research organisations.U.K.
F1581. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1581S. 508 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 78, Sch. 3 Pt. 1 (with Sch. 2)
[F1582508A Investment trusts investing in housing.U.K.
F1583. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1582Ss. 508A, 508B inserted (with effect in accordance with Sch. 30 para. 3 of the amending Act) by Finance Act 1996 (c. 8), Sch. 30 para. 1
F1583Ss. 508A, 508B repealed (with effect in accordance with s. 145(2) of the repealing Act) by Finance Act 2006 (c. 25), s. 143(a), Sch. 26 Pt. 4
508B Interpretation of section 508A.U.K.
F1584. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1582Ss. 508A, 508B inserted (with effect in accordance with Sch. 30 para. 3 of the amending Act) by Finance Act 1996 (c. 8), Sch. 30 para. 1
F1584Ss. 508A, 508B repealed (with effect in accordance with s. 145(2) of the repealing Act) by Finance Act 2006 (c. 25), s. 143(a), Sch. 26 Pt. 4
[F1585508AContemplative religious communities: profits exempt from corporation taxU.K.
(1)Subsection (2) applies in a case where members of a qualifying contemplative religious community transfer all their income and assets, or covenant all their income, to the community (“the independent community”) (and for this purpose it is irrelevant whether or not the community is part of an order or religious institution).
(2)As respects each chargeable period of the independent community, and each person who is a qualifying member of the independent community at any time in that period, the independent community shall be treated for the purposes of corporation tax as if an amount of its profits for the chargeable period equal to the relevant amount (see subsections (5) to (7)) were income of the qualifying member.
(3)Subsection (4) applies in a case where—
(a)one or more qualifying contemplative religious communities (“constituent communities”) are part of an order or religious institution (“the parent body”), and
(b)members of the constituent communities transfer all their income and assets, or covenant all their income, to the parent body.
(4)As respects each chargeable period of the parent body, and each person who is a qualifying member of a constituent community at any time in that period, the parent body shall be treated for the purposes of corporation tax as if an amount of its profits for the chargeable period equal to the relevant amount (see subsections (5) to (7)) were income of the qualifying member.
(5)For the purposes of subsections (2) and (4), the relevant amount, in relation to a chargeable period, is the amount of the annual personal allowance for persons [F1586born after 5 April 1948] (see section 35 of ITA 2007) for—
(a)the tax year which begins in the chargeable period, or
(b)if no tax year begins in the chargeable period, the tax year which is current when the chargeable period begins.
(6)But, if the chargeable period is less than 12 months, the relevant amount is—
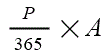
where—
P is the number of days in the chargeable period;
A is the amount determined under subsection (5) in relation to the chargeable period.
(7)If, during the chargeable period, an individual ceases to be a qualifying member of the independent community or a constituent community (otherwise than on death), the relevant amount, in relation to the chargeable period and that qualifying member, is—

where—
Q is the number of days in the chargeable period for which the individual is a qualifying member of the independent community or constituent community;
P is the number of days in the chargeable period;
B is the amount determined under subsection (5), or subsections (5) and (6), in relation to the chargeable period.
(8)So far as the exemption from corporation tax conferred by this section calls for repayment of tax, no repayment shall be made except on a claim made by the independent community or parent body.
(9)In a case where a member of an independent community or constituent community—
(a)has transferred or covenanted income to the community (in the case of an independent community) or the parent body (in the case of a constituent community), and
(b)has income for a tax year which does not exceed 20% of the annual personal allowance for persons [F1586born after 5 April 1948] (see section 35 of ITA 2007) for that tax year,
the member is, for the purposes of this section, to be taken to have transferred or covenanted all his or her income for that tax year to the community or parent body.
(10)For the purposes of this section a contemplative religious community is a “qualifying” contemplative religious community if—
(a)the community is established in the United Kingdom,
(b)the members of the community live and practise their religion in a communal establishment, and
(c)the community is not a charity, but the religion that is professed by the members of the community does not prevent the community from being a charity.
(11)In this section—
“member”, in relation to a religious community, means an individual who—
(a)is living in the community, and
(b)has taken vows or made equivalent commitments (whether probationary or not);
“qualifying member”, in relation to a religious community, means a member of the community who—
(a)has been a member of the community for a period of at least six months, and
(b)has transferred all his or her income and assets, or covenanted all his or her income, to the community (in the case of an independent community) or the parent body (in the case of a constituent community).
Textual Amendments
F1585Ss. 508A, 508B inserted (1.4.2010 with effect in accordance with art. 6(2) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2010 (S.I. 2010/157), arts. 1, 6(1)
F1586Words in s. 508A(5)(9)(b) substituted (with effect in accordance with s. 4(8) of the amending Act) by Finance Act 2012 (c. 14), s. 4(7)
508BContemplative religious communities: gains exempt from corporation taxU.K.
(1)Subsection (2) applies if, as respects a chargeable period—
(a)section 508A(2) applies in relation to an independent community,
(b)the profits of the independent community in the chargeable period are less than the total of the amounts that fall to be treated as income of the qualifying members of the community in accordance with section 508A(2), and
(c)the independent community has chargeable gains in the chargeable period.
(2)As respects the chargeable period and each qualifying member of the independent community, the community shall be treated for the purposes of corporation tax as if the relevant amount of its chargeable gains for that period were income of the qualifying member.
(3)Subsection (4) applies if, as respects a chargeable period—
(a)section 508A(4) applies in relation to a parent body,
(b)the profits of the parent body in the chargeable period are less than the total of the amounts that fall to be treated as income of the qualifying members of the constituent communities in accordance with section 508A(4), and
(c)the parent body has chargeable gains in the chargeable period.
(4)As respects the chargeable period and each qualifying member of a constituent community, the parent body shall be treated for the purposes of corporation tax as if the relevant amount of its chargeable gains for that period were income of the qualifying member.
(5)For the purposes of subsections (2) and (4), the relevant amount, in relation to a qualifying member of the independent community or a constituent community, is the smaller of—
(a)the shortfall in profits, and
(b)the average gain.
(6)The shortfall in profits is the difference between—
(a)the relevant amount determined under section 508A(5) to (7) in relation to the qualifying member, and
(b)the amount that has actually been treated as the income of the qualifying member.
(7)The average gain is—

where—
G is the amount of the chargeable gains which the independent community or parent body has in the chargeable period;
N is the number calculated by adding together the relevant value for each qualifying member of the independent community or constituent communities who, under section 508A(2) or (4), falls to be treated as having income.
(8)For the purposes of calculating “N” in subsection (7)—
(a)the relevant value for a qualifying member is 1;
(b)but, if section 508A(7) applies in relation to the qualifying member, the relevant value for that member is—

where Q and P have the same meanings as in section 508A(7).
(9)So far as the exemption from corporation tax conferred by this section calls for repayment of tax, no repayment shall be made except on a claim made by the independent community or parent body.]
Textual Amendments
509 Reserves of marketing boards and certain other statutory bodies.U.K.
F1587. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1587S. 509 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 176, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
510 Agricultural societies.U.K.
F1588. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1588S. 510 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 79, Sch. 3 Pt. 1 (with Sch. 2)
[F1589510A European economic interest groupings.U.K.
F1590. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1589S. 510A inserted (retrospective to 1.7.1989) by Finance Act 1990 (c. 29), Sch. 11 paras. 1, 5
F1590S. 510A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 80, Sch. 3 Pt. 1 (with Sch. 2)
511 The Electricity Council and Boards, the Northern Ireland Electricity Service and the Gas Council.U.K.
(1)F1591. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1591. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1591. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1592(4). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1592(5). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)F1591. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(7)F1593. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1591S. 511(1)-(3)(6) repealed (9.11.2001) by Electricity Act 1989 (c. 29), s. 113(2), Sch. 18; S.I. 2001/3419, art. 2
F1592S. 511(4)(5) repealed (1.4.1992) by S.I. 1992/231 (N.I. 1), art. 95(4), Sch.14; S.R. 1992/117, art. 3(1)
F1593S. 511(7) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 81, Sch. 3 Pt. 1 (with Sch. 2)
512 Atomic Energy Authority and National Radiological Protection Board.U.K.
F1594. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1594S. 512 repealed (with effect in accordance with s. 46(4)(c)-(e) of the repealing Act) by Finance (No. 2) Act 2005 (c. 22), s. 46(2)(c)(d), Sch. 11 Pt. 2(12), Note (with s. 46(7)); and s. 512(2) repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
513 British Airways Board and National Freight Corporation.U.K.
F1595. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1595S. 513 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 82, Sch. 3 Pt. 1 (with Sch. 2)
514 Funds for reducing the National Debt.U.K.
F1596. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1596S. 514 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 200, Sch. 3 (with Sch. 2)
515 Signatories to Operating Agreement for INMARSAT.U.K.
F1597. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1597S. 515 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
516 Government securities held by non-resident central banks.U.K.
F1598. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1598S. 516 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 103, Sch. 3 Pt. 1 (with Sch. 2)
517 Issue departments of the Reserve Bank of India and the State Bank of Pakistan.U.K.
F1599. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1599S. 517 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 83, Sch. 3 Pt. 1 (with Sch. 2)
518 Harbour reorganisation schemes.U.K.
F1600. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1600S. 518 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 84, Sch. 3 Pt. 1 (with Sch. 2)
519 Local authorities.U.K.
F1601. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1601S. 519 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 85, Sch. 3 Pt. 1 (with Sch. 2)
[F1602519A Health service bodies.U.K.
F1603. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1602S. 519A inserted (17.9.1990) by National Health Service and Community Care Act 1990 (c. 19), ss. 61(1), 67(2); S.I. 1990/1329, art. 2(5)(a), Sch. 2
F1603S. 519A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 86, Sch. 3 Pt. 1 (with Sch. 2)
PART XIIIU.K. MISCELLANEOUS SPECIAL PROVISIONS
CHAPTER IU.K. INTELLECTUAL PROPERTY
Modifications etc. (not altering text)
C37Pt. 13 Ch. 1 modified (8.11.1995) by Atomic Energy Authority Act 1995 (c. 37), Sch. 3 para. 20
Patents and know-howU.K.
520 Allowances for expenditure on purchase of patent rights: post-31st March 1986 expenditure.U.K.
F1604. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1604Ss. 520-523 repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 44, Sch. 4
521 Provisions supplementary to section 520.U.K.
F1605. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1605Ss. 520-523 repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 44, Sch. 4
522 Allowances for expenditure on purchase of patent rights: pre-1st April 1986 expenditure.U.K.
F1606. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1606Ss. 520-523 repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 44, Sch. 4
523 Lapses of patent rights, sales etc.U.K.
F1607. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1607Ss. 520-523 repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 44, Sch. 4
524 Taxation of receipts from sale of patent rights.U.K.
F1608. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1608S. 524 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 179, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
525 Capital sums: F1609. . . winding up or partnership change.U.K.
F1610. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1609Word in s. 525 sidenote omitted (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by virtue of Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 202(5) (with Sch. 2)
F1610S. 525 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 180, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
526 Relief for expenses.U.K.
F1611. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1611S. 526 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 181, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
527 Spreading of royalties over several years.U.K.
(a)a royalty or other sum is paid to a company in respect of the user of a patent,
(b)the user extended over a period of six complete years or more, and
(c)the payment is one from which a sum representing income tax must be deducted under section 903 of ITA 2007,
the company may on the making of a claim require that the corporation tax payable by it by reason of the receipt of that sum shall be reduced so as not to exceed the total amount of corporation tax which would have been payable by it if that royalty or sum had been paid in six equal instalments at yearly intervals, the last of which was paid on the date on which the payment was in fact made.]
(2)Subsection (1) above shall apply in relation to a royalty or other sum where the period of the user is two complete years or more but less than six complete years as it applies to the royalties and sums mentioned in that subsection, but with the substitution for the reference to six equal instalments of a reference to so many equal instalments as there are complete years comprised in that period.
(3)F1613. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F1614. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1612S. 527(1) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 108(2) (with Sch. 2)
F1613S. 527(3) repealed (with effect in accordance with Sch. 14 Pt. 8 Note 5 of the repealing Act) by Finance Act 1988 (c. 39), Sch. 14 Pt. 8
F1614S. 527(4) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 108(3), Sch. 3 Pt. 1 (with Sch. 2)
Marginal Citations
M72Source - 1970 s.384
528 Manner of making allowances and charges.U.K.
F1615. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1615S. 528 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 182, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
529 Patent income to be earned income in certain cases.U.K.
F1616. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1616S. 529 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 206, Sch. 3 (with Sch. 2)
530 Disposal of know-how.U.K.
F1617. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1617S. 530 repealed (with effect in accordance with s. 579 of the repealing Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 47, Sch. 4
531 Provisions supplementary to section 530.U.K.
F1618. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1618S. 531 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 183, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
532 Application of Capital Allowances ActU.K.
F1619. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1619S. 532 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 184, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
533 Interpretation of sections 520 to 532.U.K.
F1620. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1620S. 533 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 185, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Copyright and public lending rightU.K.
534 Relief for copyright payments etc.U.K.
F1621. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1621S. 534 repealed (with effect in accordance with s. 71(3) of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(6)
535 Relief where copyright sold after ten years or more.U.K.
F1622. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1622S. 535 repealed (with effect in accordance with s. 71(3) of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(6)
536 Taxation of royalties where owner abroad.U.K.
F1623. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1623Ss. 536, 537, 537B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 110, Sch. 3 Pt. 1 (with Sch. 2)
537 Public lending right.U.K.
F1624. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1624Ss. 536, 537, 537B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 110, Sch. 3 Pt. 1 (with Sch. 2)
[F1625 DesignsU.K.
Textual Amendments
F1625Ss. 537A, 537B and preceding cross-heading inserted (1.8.1989) by Intellectual Property Act 1988 (c. 48), Sch. 7 para. 36(6); S.I. 1989/816, art. 2
537A Relief for payments in respect of designs.U.K.
F1626. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1626S. 537A repealed (with effect in accordance with s. 71(3) of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(6)
537B Taxation of design royalties where owner abroad.U.K.
F1627. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1627Ss. 536, 537, 537B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 110, Sch. 3 Pt. 1 (with Sch. 2)
Artists’ receiptsU.K.
538 Relief for painters, sculptors and other artists.U.K.
F1628. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1628S. 538 repealed (with effect in accordance with s. 71(3) of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(6)
CHAPTER IIU.K. LIFE POLICIES, LIFE ANNUITIES AND CAPITAL REDEMPTION POLICIES
Modifications etc. (not altering text)
C38Pt. 13 Ch. 2 restricted (with effect in accordance with s. 105(1) of the affecting Act) by Finance Act 1996 (c. 8), Sch. 13 para. 3(2) (with Sch. 13 para. 16)
C39Pt. 13 Ch. 2 applied (with modifications) (6.4.1999) by The Individual Savings Account Regulations 1998 (S.I. 1998/1870), regs. 35(7), 36(3)-(7) (as amended by The Individual Savings Account (Amendment) Regulations 1998 (S.I. 1998/3174), reg. 12)
C40Pt. 13 Ch. 2 applied (with modifications) (6.4.1999 with effect in accordance with reg. 1 of the affecting S.I.) by The Personal Portfolio Bonds (Tax) Regulations 1999 (S.I. 1999/1029), reg. 6(2)-(8) (as amended (6.4.2002) by The Personal Portfolio Bonds (Tax) (Amendment) Regulations 2002 (S.I. 2002/455), regs. 1, 2)
C41Pt. 13 Ch. 2 modified (9.4.2003) by Finance Act 2003 (c. 14), s. 171(1)(3), Sch. 34 para. 3
C42Pt. 13 Ch. 2 modified (9.4.2003) by Finance Act 2003 (c. 14), s. 171(1)(3), Sch. 34 para. 15
C43Pt. 13 Ch. 2 modified (6.4.2005) by The Child Trust Funds Regulations 2004 (S.I. 2004/1450), regs. 1, 2(1), 38(3)-(8); S.I. 2004/3369, art. 2(1)
C44Pt. 13 Ch. 2 modified (20.7.2005) by Finance (No. 2) Act 2005 (c. 22), Sch. 7 para. 14(5)-(7)
C45Pt. 13 Ch. 2 modified (with effect in accordance with Sch. 13 para. 5 of the modifying Act) by Finance Act 2008 (c. 9), Sch. 13 para. 6
539 Introductory.U.K.
F1629. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1629Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1630539ZAApplication of this Chapter etc. to policies and contracts in which persons other than companies are interestedU.K.
F1631. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1630S. 539ZA inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 211 (with Sch. 2)
F1631Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1632539AThe conditions for being an excepted group life policyU.K.
F1633. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1632S. 539A inserted (9.4.2003) by Finance Act 2003 (c. 14), s. 171(1)(3), Sch. 34 para. 2
F1633Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
540 Life policies: chargeable events.U.K.
F1634. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1634Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
541 Life policies: computation of gain.U.K.
F1635. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1635Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
542 Life annuity contracts: chargeable events.U.K.
F1636. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1636Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
543 Life annuity contracts: computation of gain.U.K.
F1637. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1637Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
544 Second and subsequent assignment of life policies and contracts.U.K.
F1638. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1638Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
545 Capital redemption policies.U.K.
F1639. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1639Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
546 Calculation of certain amounts for purposes of sections 540, 542 and 545.U.K.
F1640. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1640Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1641546A Treatment of certain assignments etc involving co-ownershipU.K.
F1642. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1641S. 546A inserted (with effect in accordance with s. 83(2) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 9
F1642Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1643546B Special provision in respect of certain section 546 excessesU.K.
F1644. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1643Ss. 546B-546D inserted (with effect in accordance with s. 83(2) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 10
F1644Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
546C Charging the section 546 excess to tax where section 546B appliesU.K.
F1645. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1643Ss. 546B-546D inserted (with effect in accordance with s. 83(2) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 10
F1645Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
546D Modifications of s.546C for final year ending with terminal chargeable eventU.K.
F1646. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1643Ss. 546B-546D inserted (with effect in accordance with s. 83(2) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 10
F1646Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
547 Method of charging gain to tax.U.K.
F1647. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1647Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1648547A Method of charging gain to tax: multiple interests.U.K.
F1649. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1648S. 547A inserted (with effect in accordance with Sch. 14 para. 7(5) of the amending Act) by Finance Act 1998 (c. 36), Sch. 14 para. 2
F1649Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
548 Deemed surrender of certain loans.U.K.
F1650. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1650Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1651548AEffect of rebated or reinvested commission in certain casesU.K.
F1652. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1651Ss. 548A, 548B inserted (with effect in accordance with s. 29(4) of the amending Act) by Finance Act 2007 (c. 11), s. 29(1)
F1652Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
548BSection 548A: further definitionsU.K.
F1653. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1651Ss. 548A, 548B inserted (with effect in accordance with s. 29(4) of the amending Act) by Finance Act 2007 (c. 11), s. 29(1)
F1653Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
549 Certain deficiencies allowable as deductions.U.K.
F1654. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1654S. 549 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 219, Sch. 3 (with Sch. 2)
550 Relief where gain charged at a higher rate.U.K.
F1655. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1655S. 550 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 220, Sch. 3 (with Sch. 2)
551 Right of individual to recover tax from trustees.U.K.
F1656. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1656S. 551 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 221, Sch. 3 (with Sch. 2)
[F1657551A Right of company to recover tax from trustees.U.K.
F1658. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1657Ss. 551A inserted (with effect in accordance with Sch. 14 para. 7(5) of the amending Act) by Finance Act 1998 (c. 36), Sch. 14 para. 3
F1658Ss. 539-551A omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 3
[F1659552 Information: duty of insurers.U.K.
(1)Where a chargeable event F1660. . . has happened in relation to any policy or contract, the body by or with whom the policy or contract was issued, entered into or effected shall—
(a)unless satisfied that no gain is to be treated as arising by reason of the event, deliver to the appropriate policy holder before the end of the relevant three month period a certificate specifying the information described in subsection (5) below; and
(b)if the condition in paragraph (a) or (b) of subsection (2) below is satisfied, deliver to the inspector before the end of the relevant three month period a certificate specifying the information described in subsection (5) below together with the name and address of the appropriate policy holder.
(2)For the purposes of this section—
(a)the condition in this paragraph is that the event is an assignment for money or money’s worth of the whole of the rights conferred by the policy or contract; or
(b)the condition in this paragraph is that the amount of the gain, or the aggregate amount of the gain and any gains connected with it, exceeds one half of the basic rate limit for the relevant year of assessment.
(3)If, in the case of every certificate which a body delivers under subsection (1)(a) above which relates to a gain attributable to a year of assessment F1661. . . , the body also delivers to the inspector—
(a)before the end of the relevant three month period for the purposes of subsection (1)(b) above,
(b)by a means prescribed by the Board for the purposes of this subsection under section 552ZA(5), and
(c)in a form so prescribed in the case of that means,
a certificate specifying the same information as the certificate under subsection (1)(a) together with the name and address of the appropriate policy holder, the body shall be taken to have complied with the requirements of subsection (1)(b) above in relation to that year of assessment F1662. . . so far as relating to the chargeable events to which the certificates relate.
(4)Where a certificate is not required to be delivered under subsection (1)(b) above in the case of any chargeable event—
(a)the inspector may by notice require the body to deliver to him a copy of any certificate that the body was required to deliver under subsection (1)(a) above which relates to the chargeable event; and
(b)it shall be the duty of the body to deliver such a copy within 30 days of receipt of the notice.
(5)The information to be given to the appropriate policy holder pursuant to subsection (1)(a) above or the inspector pursuant to subsection (1)(b) above is—
(a)any unique identifying designation given to the policy or contract;
(b)the nature of the chargeable event and—
(i)the date on which it happened; and
(ii)if it is a chargeable event by virtue of F1663. . . [F1664section 514(1) of ITTOIA 2005 (chargeable events where transaction-related calculations show gains), the date on which [F1665the insurance year ends];]
(c)if the event is the assignment of all the rights conferred by the policy or contract, such of the following as may be required for computing the amount of the gain to be treated as arising by virtue of F1666. . . [F1667Chapter 9 of Part 4 of ITTOIA 2005]—
(i)F1668. . . [F1669the amount or value of any capital sums of a kind referred to in section 492(1)(b) to (e) of ITTOIA 2005];
(ii)the amounts previously paid under the policy or contract by way of premiums or otherwise by way of consideration for an annuity;
(iii)F1670. . . [F1671the amount of so much of any payment previously made on account of an annuity as is exempt under section 717 of ITTOIA 2005];
(iv)the value of any previously assigned parts of or shares in the rights conferred by the policy or contract;
(v)F1672. . . [F1673the total of the amounts of gains treated as arising on previous chargeable events within section 509(1) or 514(1) of ITTOIA 2005];
(d)except where paragraph (c) above applies, the amount of the gain treated as arising by reason of the event;
[F1674(e)the number of years relevant for computing the annual equivalent of the amount of the gain for the purposes of subsection (1) of section 536 of ITTOIA 2005 (top slicing relieved liability: one chargeable event), apart from subsections (6) and (8) of that section;]
[F1675(f)on the assumption that section 465 of ITTOIA 2005 (person liable: individuals) has effect in relation to the gain —
(i)whether an individual would fall to be treated as having paid income tax at the [F1676basic rate] on the amount of the gain in accordance with section 530 of that Act; and
(ii)if so, except in a case where paragraph (c) above applies, the amount of such tax that would fall to be so treated as paid.]
(6)For the purposes of subsection (1)(a) above, the relevant three month period is whichever of the following periods ends the latest—
(a)the period of three months following the happening of the chargeable event;
(b)if the event is a surrender or assignment which is a chargeable event by virtue of F1677. . . [F1678section 514(1) of ITTOIA 2005 F1679. . . ], the period of three months following the end of [F1680the insurance year] in which the event happens;
(c)if the event is a death or an assignment of the whole of the rights or a surrender or assignment which is a chargeable event by virtue of F1681. . . [F1682section 514(1) of ITTOIA 2005 F1681. . . ], the period of three months beginning with receipt of written notification of the event.
(7)For the purposes of subsection (1)(b) above, the relevant three month period is whichever of the following periods ends the latest—
(a)the period of three months following the end of the year of assessment F1683. . . in which the event happened;
(b)if the event is a surrender or assignment which is a chargeable event by virtue of [F1684section 514(1) of ITTOIA 2005, the period of three months following the end of the insurance year] in which the event happens;
(c)if the event is a death or an assignment, the period of three months beginning with receipt of written notification of the event;
(d)if a certificate under subsection (1)(b) above would not be required in respect of the event apart from the happening of another event, and that other event is one of those mentioned in paragraph (c) above, the period of three months beginning with receipt of written notification of that other event.
(8)For the purposes of this section the cases where a gain is connected with another gain are those cases where—
(a)both gains arise in connection with policies or contracts containing obligations which, immediately before the chargeable event, were obligations of the same body;
(b)the policy holder of those policies or contracts is the same;
(c)both gains are attributable to the same year of assessment F1685. . . ;
(d)the terms of the policies or contracts are the same, apart from any difference in their maturity dates; and
(e)the policies or contracts were issued in respect of insurances made, or were entered into or effected, on the same date.
(9)For the purposes of this section, the year of assessment F1686. . . to which a gain is attributable is—
(a)in the case of a gain treated as arising by virtue of [F1687subsection (1) of section 514 of ITTOIA 2005, the year of assessment which includes the end of the insurance year mentioned in subsection (3) and (4) of that section;] or
(b)in any other case, the year of assessment F1688. . . in which happens the chargeable event by reason of which the gain is treated as arising.
(10)In this section—
“amount”, in relation to any gain, means the amount of the gain apart from F1689. . . [F1690section 528 of ITTOIA 2005];
“appropriate policy holder” means—
(a)in relation to an assignment of part of or a share in the rights conferred by a policy or contract, any person who is both—
(i)the policy holder, or one of the policy holders, immediately before the assignment; and
(ii)the assignor or one of the assignors; and
(b)in relation to any other chargeable event, the person who is the policy holder immediately before the happening of the event;
[F1691“chargeable event” means an event which is a chargeable event within the meaning of F1692. . . Chapter 9 of Part 4 of ITTOIA 2005;]
F1693. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1694“insurance year” has the same meaning as in Chapter 9 of Part 4 of ITTOIA 2005 (see section 499 of that Act);]
“the relevant year of assessment”, in the case of any gain, means—
F1696. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F1696. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(11)F1697. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(12)This section is supplemented by section 552ZA.
[F1698[F1699(13)For the purposes of this section—
(a)section 491(2) of ITTOIA 2005 is taken to have effect as if, in the definition of “PG”, the words from “but” to the end were omitted, and
(b)no account is to be taken of the effect of [F1700section 465B or 541A] of that Act.]]
[F1701(14)For the purposes of this section no account is to be taken of the effect of sections 528 and 528A of ITTOIA 2005.]]
Textual Amendments
F1659Ss. 552, 552ZA substituted for s. 552 (with effect in accordance with s. 83(3) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 18
F1660Words in s. 552(1) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(2), Sch. 3 (with Sch. 2)
F1661Words in s. 552(3) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(2)(a)
F1662Words in s. 552(3) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(2)(b)
F1663Words in s. 552(5)(b)(ii) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(3)(a)(i)
F1664Words in s. 552(5)(b)(ii) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(a) (with Sch. 2)
F1665Words in s. 552(5)(b)(ii) substituted (with effect in accordance with Sch. 14 para. 18 of the amending Act) by Finance Act 2008 (c. 9), Sch. 14 para. 4(3)(a)(ii)
F1666Words in s. 552(5)(c) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(3)(b)(i)
F1667Words in s. 552(5)(c) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(b)(i) (with Sch. 2)
F1668Words in s. 552(5)(c)(i) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(3)(b)(ii)
F1669Words in s. 552(5)(c)(i) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(b)(ii) (with Sch. 2)
F1670Words in s. 552(5)(c)(iii) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(3)(b)(iii)
F1671Words in s. 552(5)(c)(iii) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(b)(iii) (with Sch. 2)
F1672Words in s. 552(5)(c)(v) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(3)(b)(iv)
F1673Words in s. 552(5)(c)(v) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(b)(iv) (with Sch. 2)
F1674S. 552(5)(e) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(c) (with Sch. 2)
F1675S. 552(5)(f) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(3)(d) (with Sch. 2)
F1676Words in s. 552(5)(f)(i) substituted (with effect in accordance with Sch. 1 para. 65 of the amending Act) by Finance Act 2008 (c. 9), Sch. 1 para. 43
F1677Words in s. 552(6)(b) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(4)(a)(i)
F1678Words in s. 552(6)(b) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(4)(a)(i) (with Sch. 2)
F1679Closing bracket in s. 552(6)(b) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(4)(a)(ii)
F1680Words in s. 552(6)(b) substituted (with effect in accordance with Sch. 14 para. 18 of the amending Act) by Finance Act 2008 (c. 9), Sch. 14 para. 4(4)(a)(iii)
F1681Words and closing bracket in s. 552(6)(c) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(4)(b)
F1682Words in s. 552(6)(c) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(4)(b) (with Sch. 2)
F1683Words in s. 552(7)(a) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(5)(a)
F1684Words in s. 552(7)(b) substituted (with effect in accordance with Sch. 14 para. 18 of the amending Act) by Finance Act 2008 (c. 9), Sch. 14 para. 4(5)(b)
F1685Words in s. 552(8)(c) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(6)
F1686Words in s. 552(9) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(7)(a)
F1687Words in s. 552(9)(a) substituted (with effect in accordance with Sch. 14 para. 18 of the amending Act) by Finance Act 2008 (c. 9), Sch. 14 para. 4(7)(b)
F1688Words in s. 552(9)(b) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(7)(c)
F1689S. 552(10): words in definition of "amount" omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(8)(a)
F1690S. 552(10): words in definition of "amount" inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(7)(a) (with Sch. 2)
F1691S. 552(10): definition of "chargeable event" inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 222(7)(b) (with Sch. 2)
F1692S. 552(10): words in definition of "chargeable event" omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(8)(b)
F1693S. 552(10): definition of "financial year" omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(8)(c)
F1694S. 552(10): definition of "insurance year" inserted (with effect in accordance with Sch. 14 para. 18 of the amending Act) by Finance Act 2008 (c. 9), Sch. 14 para. 4(8)(d)
F1695S. 552(10): in definition of "the relevant year of assessment", para. (b) and preceding word omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(8)(e)
F1696S. 552(10): definitions of "section 546 excess" and "year" omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(8)(f)
F1697S. 552(11) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 4(9)
F1698S. 552(13) inserted (with effect in accordance with s. 29(4) of the amending Act) by Finance Act 2007 (c. 11), s. 29(2)
F1699S. 552(13) substituted (with effect in accordance with s. 11(4)-(6) of the amending Act) by Finance Act 2011 (c. 11), s. 11(3)
F1700Words in s. 552(13) substituted (with effect in accordance with Sch. 45 para. 153(3) of the amending Act) by Finance Act 2013 (c. 29), Sch. 45 para. 144
F1701S. 552(14) inserted (with effect in accordance with Sch. 8 para. 7 of the amending Act) by Finance Act 2013 (c. 29), Sch. 8 para. 6
Modifications etc. (not altering text)
C46S. 552(6) modified (9.4.2003) by Finance Act 2003 (c. 14), s. 171(1)(3), Sch. 34 para. 5
[F1702552ZA Information: supplementary provisionsU.K.
(1)This section supplements section 552 and shall be construed as one with it.
(2)Where the obligations under any policy or contract of the body that issued, entered into or effected it (“the original insurer”) are at any time the obligations of another body (“the transferee”) to whom there has been a transfer of the whole or any part of a business previously carried on by the original insurer, section 552 shall have effect in relation to that time, except where the chargeable event—
(a)happened before the transfer, and
(b)in the case of a death or an assignment, is an event of which the notification mentioned in subsection (6) or (7) of that section was given before the transfer,
as if the policy or contract had been issued, entered into or effected by the transferee.
(3)Where, in consequence of F1703. . . [F1704section 514(1) of ITTOIA 2005], paragraph (a) or (b) of section 552(1) requires certificates to be delivered in respect of two or more surrenders, happening in the same year, of part of or a share in the rights conferred by the policy or contract, a single certificate may be delivered under the paragraph in question in respect of all those surrenders (and may treat them as if they together constituted a single surrender) unless between the happening of the first and the happening of the last of them there has been—
(a)an assignment of part of or a share in the rights conferred by the policy or contract; or
(b)an assignment, otherwise than for money or money’s worth, of the whole of the rights conferred by the policy or contract.
(4)Where the appropriate policy holder is two or more persons—
(a)section 552(1)(a) requires a certificate to be delivered to each of them; but
(b)nothing in section 552 or this section requires a body to deliver a certificate under subsection (1)(a) of that section to any person whose address has not been provided to the body (or to another body, at a time when the obligations under the policy or contract were obligations of that other body).
(5)A certificate under section 552(1)(b) or (3)—
(a)shall be in a form prescribed for the purpose by the Board; and
(b)shall be delivered by any means prescribed for the purpose by the Board;
and different forms, or different means of delivery, may be prescribed for different cases or different purposes.
(6)The Board may by regulations make such provision as they think fit for securing that they are able—
(a)to ascertain whether there has been or is likely to be any contravention of the requirements of section 552 or this section; and
(b)to verify any certificate under that section.
(7)Regulations under subsection (6) above may include, in particular, provisions requiring persons to whom premiums under any policy are or have at any time been payable—
(a)to supply information to the Board; and
(b)to make available books, documents and other records for inspection on behalf of the Board.
(8)Regulations under subsection (6) above may—
(a)make different provision for different cases; and
(b)contain such supplementary, incidental, consequential or transitional provision as appears to the Board to be appropriate.]
Textual Amendments
F1702Ss. 552, 552ZA substituted for s. 552 (with effect in accordance with s. 83(3) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 18
F1703Words in s. 552ZA(3) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 5
F1704Words in s. 552ZA(3) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 223 (with Sch. 2)
[F1705552ZBRegulations in relation to qualifying policiesU.K.
(1)The Commissioners for Her Majesty's Revenue and Customs may make regulations—
(a)requiring relevant persons—
(i)to provide prescribed information to persons who apply for the issue of qualifying policies or who are, or may be, required to make statements under paragraph B3(2) of Schedule 15;
(ii)to provide to an officer of Revenue and Customs prescribed information about qualifying policies which have been issued by them or in relation to which they are or have been a relevant transferee;
(b)making such provision (not falling within paragraph (a)) as the Commissioners think fit for securing that an officer of Revenue and Customs is able—
(i)to ascertain whether there has been or is likely to be any contravention of the requirements of the regulations or of paragraph B3(2) of Schedule 15;
(ii)to verify any information provided to an officer of Revenue and Customs as required by the regulations.
(2)The provision that may be made by virtue of subsection (1)(b) includes, in particular, provision requiring relevant persons to make available books, documents and other records for inspection by or on behalf of an officer of Revenue and Customs.
(3)The regulations may—
(a)make different provision for different cases or circumstances, and
(b)contain incidental, supplementary, consequential, transitional, transitory or saving provision.
(4)In this section—
“prescribed” means prescribed by the regulations,
“qualifying policy” includes a policy which would be a qualifying policy apart from—
(a)paragraph A1(2), B1(2), B2(2) or B3(3) of Schedule 15, or
(b)paragraph 17(2)(za) of that Schedule (including as applied by paragraph 18), and
“relevant person” means a person—
(a)who issues, or has issued, qualifying policies, or
(b)who is, or has been, a relevant transferee in relation to qualifying policies.
(5)For the purposes of this section a person (“X”) is at any time a “relevant transferee” in relation to a qualifying policy if the obligations under the policy of its issuer are at that time the obligations of X as a result of there having been a transfer to X of the whole or any part of a business previously carried on by the issuer.]
Textual Amendments
F1705S. 552ZB inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 10
[F1706552A Tax representatives.U.K.
(1)This section has effect for the purpose of securing that, where it applies to an overseas insurer, another person is the overseas insurer’s tax representative.
(2)In this section “overseas insurer” means a person who is not resident in the United Kingdom who carries on a business which consists of or includes the effecting and carrying out of—
(a)policies of life insurance;
(b)contracts for life annuities; or
(c)capital redemption policies.
(3)This section applies to an overseas insurer—
(a)if the condition in subsection (4) below is satisfied on the designated day; or
(b)where that condition is not satisfied on that day, if it has subsequently become satisfied.
(4)The condition mentioned in subsection (3) above is that—
(a)there are in force relevant insurances the obligations under which are obligations of the overseas insurer in question or of an overseas insurer connected with him; and
(b)the total amount or value of the gross premiums paid under those relevant insurances is £1 million or more.
(5)In this section “relevant insurance” means any policy of life insurance, contract for a life annuity or capital redemption policy F1707. . . in the case of which—
(a)the holder is resident in the United Kingdom;
(b)the obligations of the insurer are obligations of a person not resident in the United Kingdom; and
(c)those obligations are not attributable to a branch or agency of that person’s in the United Kingdom.
(6)Before the expiration of the period of three months following the day on which this section first applies to an overseas insurer, the overseas insurer must nominate to the Board a person to be his tax representative.
(7)A person shall not be a tax representative unless—
(a)if he is an individual, he is resident in the United Kingdom and has a fixed place of residence there, or
(b)if he is not an individual, he has a business establishment in the United Kingdom,
and, in either case, he satisfies such other requirements (if any) as are prescribed in regulations made for the purpose by the Board.
(8)A person shall not be an overseas insurer’s tax representative unless—
(a)his nomination by the overseas insurer has been approved by the Board; or
(b)he has been appointed by the Board.
(9)The Board may by regulations make provision supplementing this section; and the provision that may be made by any such regulations includes provision with respect to—
(a)the making of a nomination by an overseas insurer of a person to be his tax representative;
(b)the information which is to be provided in connection with such a nomination;
(c)the form in which such a nomination is to be made;
(d)the powers and duties of the Board in relation to such a nomination;
(e)the procedure for approving, or refusing to approve, such a nomination, and any time limits applicable to doing so;
(f)the termination, by the overseas insurer or the Board, of a person’s appointment as a tax representative;
(g)the appointment by the Board of a person as the tax representative of an overseas insurer (including the circumstances in which such an appointment may be made);
(h)the nomination by the overseas insurer, or the appointment by the Board, of a person to be the tax representative of an overseas insurer in place of a person ceasing to be his tax representative;
(j)circumstances in which an overseas insurer to whom this section applies may, with the Board’s agreement, be released (subject to any conditions imposed by the Board) from the requirement that there must be a tax representative;
(k)appeals to the [F1708tribunal] against decisions of the Board under this section or regulations under it.
(10)The provision that may be made by regulations under subsection (9) above also includes provision for or in connection with the making of other arrangements between the Board and an overseas insurer for the purpose of securing the discharge by or on behalf of the overseas insurer of the relevant duties, within the meaning of section 552B.
(11)[F1709Section 1122 of CTA 2010] (connected persons) applies for the purposes of this section.
(12)In this section—
[F1710“capital redemption policy” means a capital redemption policy in relation to which F1711. . . Chapter 9 of Part 4 of ITTOIA 2005 [F1712has] effect;]
[F1713“contract for a life annuity” means a contract for a life annuity in relation to which F1711. . . Chapter 9 of Part 4 of ITTOIA 2005 [F1712has] effect;]
“the designated day” means such day as the Board may specify for the purpose in regulations;
[F1714“policy of life insurance” means a policy of life insurance in relation to which F1711. . . Chapter 9 of Part 4 of ITTOIA 2005 [F1712has] effect;]
“tax representative” means a tax representative under this section.
Subordinate Legislation Made
P1S. 552A(12) power exercised: 6.4.1999 appointed by S.I. 1999/881, reg. 3
Textual Amendments
F1706Ss. 552A, 552B inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 87
F1707Words in s. 552A(5) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 224(2), Sch. 3 (with Sch. 2)
F1708Word in s. 552A(9)(k) substituted (1.4.2009) by The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 148
F1709Words in s. 552A(11) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 87 (with Sch. 2)
F1710S. 552A(12): definition of "capital redemption policy" inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 224(3) (with Sch. 2)
F1711Words in s. 552A(12) omitted (with effect in accordance with Sch. 14 para. 18 of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 6(a)
F1712Words in s. 552A(12) substituted (with effect in accordance with Sch. 14 para. 18 of the amending Act) by Finance Act 2008 (c. 9), Sch. 14 para. 6(b)
F1713S. 552A(12): definition of "contract for a life annuity" inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 224(3) (with Sch. 2)
F1714S. 552A(12): definition of "policy of life insurance" inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 224(3) (with Sch. 2)
Modifications etc. (not altering text)
C47S. 522A restricted (6.4.1999) by The Overseas Insurers (Tax Representatives) Regulations 1999 (S.I. 1999/881), reg. 11(2)
552B Duties of overseas insurers’ tax representatives.U.K.
(1)It shall be the duty of an overseas insurer’s tax representative to secure (where appropriate by acting on the overseas insurer’s behalf) that the relevant duties are discharged by or on behalf of the overseas insurer.
[F1715(2)For the purposes of this section “the relevant duties” are—
(a)the duties imposed by section 552,
(b)the duties imposed by section 552ZA(2), (4) or (5), F1716. . .
(c)any duties imposed by regulations made under subsection (6) of section 552ZA by virtue of subsection (7) of that section, [F1717and
(d)any duties imposed by regulations under section 552ZB,]
so far as relating to relevant insurances under which the overseas insurer in question has any obligations.]
(3)An overseas insurer’s tax representative shall be personally liable—
(a)in respect of any failure to secure the discharge of the relevant duties, and
(b)in respect of anything done for purposes connected with acting on the overseas insurer’s behalf,
as if the relevant duties were imposed jointly and severally on the tax representative and the overseas insurer.
(4)In the application of this section in relation to any particular tax representative, it is immaterial whether any particular relevant duty arose before or after his appointment.
(5)This section has effect in relation to relevant duties relating to chargeable events happening on or after the day by which section 552A(6) requires the nomination of the overseas insurer’s first tax representative to be made.
[F1718(5A)In subsection (5) “chargeable event” has the same meaning as in section 552 (see subsection (10) of that section).]
(6)Expressions used in this section and in section 552A have the same meaning in this section as they have in that section.]
Textual Amendments
F1706Ss. 552A, 552B inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 87
F1715S. 552B(2) substituted (with effect in accordance with s. 83(3) of the amending Act) by Finance Act 2001 (c. 9), Sch. 28 para. 19
F1716Word in s. 552B(2) omitted (17.7.2013) by virtue of Finance Act 2013 (c. 29), Sch. 9 para. 11(a)
F1717S. 552B(2)(d) and preceding word inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 11(b)
F1718S. 552B(5A) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 225 (with Sch. 2)
553 Non-resident policies and off-shore capital redemption policies.U.K.
F1719. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1719Ss. 553-553C omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 7
[F1720553A Overseas life assurance business: life policies.U.K.
F1721. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1720S. 553A inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 88(1)
F1721Ss. 553-553C omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 7
[F1722553B Overseas life assurance business: capital redemption policies.U.K.
F1723. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1722S. 553B inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 88(2)
F1723Ss. 553-553C omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 7
[F1724553C Personal portfolio bonds.U.K.
F1725. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1724S. 553C inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 89
F1725Ss. 553-553C omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 7
554 Borrowings on life policies to be treated as income in certain cases.U.K.
F1726. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1726S. 554 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 229, Sch. 3 (with Sch. 2)
CHAPTER IIIU.K. ENTERTAINERS AND SPORTSMEN
555 Payment of tax.U.K.
F1727. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1727S. 555 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 113, Sch. 3 Pt. 1 (with Sch. 2)
556 Activity treated as trade etc. and attribution of income.U.K.
F1728. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1728S. 556 omitted (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by virtue of Corporation Tax Act 2009 (c. 4), Sch. 1 para. 186 (with Sch. 2 Pts. 1, 2)
557 Charge on [F1729profits].U.K.
F1730. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1729Word in s. 557 sidenote substituted (31.7.1998) by Finance Act 1998 (c. 36), s. 46(3)(a), Sch. 7 para. 1
F1730S. 557 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 231, Sch. 3 (with Sch. 2)
558 Supplementary provisions.U.K.
(1)F1731. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1731. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1731. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F1731. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F1732. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)F1732. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1731S. 558(1)-(4) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 115, Sch. 3 Pt. 1 (with Sch. 2)
F1732S. 558(5)(6) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 187, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
CHAPTER IVU.K. SUB-CONTRACTORS IN THE CONSTRUCTION INDUSTRY
559 Deductions on account of tax etc. from payments to certain sub-contractors.U.K.
F1733. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1733Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
[F1734559A Treatment of sums deducted under s.559U.K.
F1735. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1734S. 559A inserted (with effect in accordance with s. 40(4) of the amending Act) by Finance Act 2002 (c. 23), s. 40(1)
F1735Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
560 Persons who are sub-contractors or contractors for purposes of Chapter IV.U.K.
F1736. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1736Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
561 Exceptions from section 559.U.K.
F1737. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1737Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
562 Conditions to be satisfied by individuals.U.K.
F1738. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1738Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
563 Conditions to be satisfied by partners who are individuals.U.K.
F1739. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1739S. 563 repealed (with effect in accordance with Sch. 27 para. 8(1), Sch. 29 Pt. 8(21) Note 3 of the repealing Act) by Finance Act 1995 (c. 4), Sch. 27 para. 5, Sch. 29 Pt. 8(21); S.I. 1998/2620, art. 3
564 Conditions to be satisfied by firms.U.K.
F1740. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1740Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
565 Conditions to be satisfied by companies.U.K.
F1741. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1741Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
566 General powers to make regulations under Chapter IV.U.K.
F1742. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1742Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
567 Meaning of “construction operations”.U.K.
F1743. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1743Pt. 13 Ch. 4 (ss. 559-567) repealed (with effect in accordance with s. 77 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 12 para. 9(2), Sch. 42 Pt. 2(7), Note; S.I. 2006/3240, art. 2
CHAPTER VU.K. SCHEMES FOR RATIONALIZING INDUSTRY
568 Deductions from profits of contributions paid under certified schemes.U.K.
M73(1)Notwithstanding anything contained in F1744. . . [F1745section 33 of ITTOIA 2005][F1746or section 53 of CTA 2009 (no deduction for capital expenditure)] but subject to the following provisions of this Chapter, where a person pays, wholly and exclusively for the purposes of a trade in respect of which he is chargeable [F1747under Part 2 of ITTOIA 2005 or Part 3 of CTA 2009,] a contribution in furtherance of a scheme which is for the time being certified by the Secretary of State under this section, the contribution shall, in so far as it is paid in furtherance of the primary object of the scheme, be allowed to be deducted as an expense in computing the [F1748profits] of that trade.
(2)The Secretary of State shall certify a scheme under this section if he is satisfied—
(a)that the primary object of the scheme is the elimination of redundant works or machinery or plant from use in an industry in the United Kingdom; and
(b)that the scheme is in the national interest and in the interests of that industry as a whole; and
(c)that such number of persons engaged in that industry as are substantially representative of the industry are liable to pay contributions in furtherance of the primary object of the scheme by agreement between them and the body of persons carrying out the scheme.
References in this subsection to an industry in the United Kingdom shall include references to the business carried on by owners of ships or of a particular class of ships, wherever that business is carried on, and, in relation to that business, references in this subsection to works or machinery or plant shall include references to ships.
(3)The Secretary of State shall cancel any certificate granted under this section if he ceases to be satisfied as to any of the matters referred to in subsection (2) above.
(4)The Secretary of State may at any time require the body of persons carrying out a scheme certified under this section to produce any books or documents of whatever nature relating to the scheme and, if the requirement is not complied with, he may cancel the certificate.
(5)In this section and in section 569 “contribution”, in relation to a scheme, does not include a sum paid by a person by way of loan or subscription of share capital, or in consideration of the transfer of assets to him, or by way of a penalty for contravening or failing to comply with the scheme.
Textual Amendments
F1744Words in s. 568(1) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 188(a), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F1745Words in s. 568(1) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 232(a) (with Sch. 2)
F1746Words in s. 568(1) inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 188(b) (with Sch. 2 Pts. 1, 2)
F1747Words in s. 568(1) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 188(c) (with Sch. 2 Pts. 1, 2)
F1748Words in s. 568(1) substituted (31.7.1998) by Finance Act 1998 (c. 36), s. 46(3)(a), Sch. 7 para. 1
Marginal Citations
M73Source-1970 s.406
569 Repayment of contributions.U.K.
M74(1)In the event of the repayment, whether directly or by way of distribution of assets on a winding up or otherwise, of a contribution or any part of a contribution which has been allowed to be deducted under section 568, the deduction of the contribution, or so much of it as has been repaid, shall be deemed to be an unauthorised deduction in respect of which an assessment shall be made, and, notwithstanding the provisions of the Tax Acts requiring assessments to be made within six years after the end of the chargeable period to which they relate, any such assessment and any consequential assessment may be made at any time within three years after the end of the chargeable period in which the repayment was made.
(2)For the purposes of this section, a sum received by any person by way of repayment of contributions shall be deemed to be by way of repayment of the last contribution paid by him, and, if the sum exceeds the amount of that contribution, by way of repayment of the penultimate contribution so paid, and so on.
Marginal Citations
M74Source-1970 s.407; 1971 Sch.6 45
570 Payments under certified schemes which are not repayments of contributions.U.K.
M75(1)Subject to the provisions of this section, where, under any scheme which is for the time being certified or has at any time been certified by the Secretary of State under section 568, any payment (not being a payment made by way of repayment of contributions) is made to a person carrying on a trade to which the scheme relates, that payment shall be treated for the purposes of the Tax Acts as a trading receipt of the trade, and shall accordingly be taken into account in computing the [F1749profits] of the trade for those purposes.
(2)Where F1750. . . the payments which have been made under such a scheme in respect of a trade (not being payments made by way of repayment of contributions) have been made wholly or partly in respect of damage in respect of which no relief may be given under the Tax Acts, [F1751and a claim is made to that effect,] then, subject to and in accordance with the provisions of [F1752Schedule 21]—
(a)relief shall be given in respect of those payments by reducing the amounts which are to be treated as trading receipts of the trade under subsection (1) above; but
(b)where such relief is given, section 568 shall, in relation to contributions subsequently paid under the scheme in respect of the trade, have effect subject to the modifications specified in Part III of that Schedule,
[F1753and paragraph 6 of that Schedule applies for the purposes of this subsection as it applies for the purposes of that Schedule.]
(3)The provisions of this section and Schedule 21 shall apply in relation to any payment made to a person who has ceased to carry on a trade to which any such scheme as is mentioned in subsection (1) above relates as they apply in relation to payments made to a person carrying on such a trade, subject to the modification that so much of that payment as falls to be treated as a trading receipt by virtue of those provisions shall be deemed for the purposes of those provisions to have been made to him on the last day on which he was engaged in carrying on the trade.
(4)In determining for the purposes of this section and of Schedule 21—
(a)whether any trade has ceased to be carried on; or
(b)whether any contribution is paid in respect of a trade in respect of which a payment has been made; or
(c)whether any payment is made in respect of a trade in respect of which a contribution has been paid,
no regard shall be had to any event which, by virtue of [F1754section 18 of ITTOIA 2005 or section 41 of CTA 2009 (company starting or ceasing to be within charge to corporation tax) is to be treated as effecting a cessation of trading.]
Textual Amendments
F1749Words in s. 570(1) substituted (31.7.1998) by Finance Act 1998 (c. 36), s. 46(3)(a), Sch. 7 para. 1
F1750Words in s. 570(2) repealed (with effect in accordance with s. 134(2) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 20 para. 31(a), Sch. 41 Pt. 5(10), Note
F1751Words in s. 570(2) inserted (with effect in accordance with s. 134(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 20 para. 31(b)
F1752Words in s. 570(2) substituted (with effect in accordance with s. 134(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 20 para. 31(c)
F1753Words in s. 570(2) added (with effect in accordance with s. 134(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 20 para. 31(d)
F1754Words in s. 570(4) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 189 (with Sch. 2 Pts. 1, 2)
Marginal Citations
M75Source-1970 s.408
571 Cancellation of certificates.U.K.
M76(1)Where any certificate granted with respect to a scheme under section 568 is cancelled by the Secretary of State, and any deductible contributions paid in furtherance of the scheme have not been repaid at the expiration of one year from the cancellation, the body of persons carrying out the scheme shall, for the chargeable period in which that year expires, be charged to tax F1755. . . upon the aggregate amount of the deductible contributions which have not been repaid at that time.
[F1756(1A)An amount charged to income tax under subsection (1) above is treated for income tax purposes as an amount of income.]
[F1757(1B)So far as relating to corporation tax, the charge to tax under subsection (1) has effect as an application of the charge to corporation tax on income.]
(2)The charge to tax under subsection (1) above shall not be made if the total amount of any contributions, other than deductible contributions, which have been paid under the scheme and have not been repaid before that time is greater than the available resources of the scheme, and shall not in any case be made upon an amount greater than the excess, if any, of those resources over that total amount.
(3)In subsection (2) above “the available resources”, in relation to any scheme, means a sum representing the total funds held for the purposes of the scheme at the expiration of one year from the cancellation of the certificate plus a sum representing any funds held for the purposes of the scheme which, during that year, have been applied otherwise than in accordance with the provisions of the scheme as in force when the certificate was granted.
(4)Where the body of persons carrying out a scheme are charged to tax by virtue of subsection (1) above, and, after the expiration of one year from the cancellation of the certificate, any deductible contribution paid in furtherance of the scheme is repaid, the amount upon which the charge is made shall on the making of a claim be reduced by the amount repaid, and all such repayments of tax shall be made as are necessary to give effect to the provisions of this subsection.
(5)In this section “contribution” includes a part of a contribution, and “deductible contribution” means a contribution allowed to be deducted under section 568, any reduction under Part III of Schedule 21 being left out of account.
(6)For the purposes of this section, a sum received by any person by way of repayment of contributions shall be deemed to be by way of repayment of the last contribution paid by him, and, if the sum exceeds the amount of that contribution, by way of repayment of the penultimate contribution so paid, and so on.
Textual Amendments
F1755Words in s. 571(1) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 190(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F1756S. 571(1A) inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 116 (with Sch. 2)
F1757S. 571(1B) inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 190(3) (with Sch. 2 Pts. 1, 2)
Marginal Citations
M76Source-1970 s.409
572 Application to statutory redundancy schemes.U.K.
M77(1)Sections 569 to 571 and Schedule 21 shall, subject to the adaptations specified in subsection (2) below, apply in relation to a statutory redundancy scheme as they apply in relation to a scheme certified under section 568.
(2)The adaptations referred to above are as follows, that is to say—
(a)for any reference to a contribution allowed to be deducted under section 568 there shall be substituted a reference to a contribution allowed to be deducted under any provision of the Tax Acts other than that section;
(b)any provision that section 568 shall, in relation to contributions, have effect subject to modifications, shall be construed as a provision that so much of any provision of the Tax Acts other than that section as authorises the deduction of contributions shall, in relation to the contributions in question, have effect subject to the modifications in question;
(c)for any reference to the cancellation of a certificate with respect to a scheme there shall be substituted a reference to the scheme ceasing to have effect; and
(d)for any reference to the provisions of the scheme as in force when the certificate was granted there shall be substituted a reference to the provisions of the scheme as in force when the contributions were first paid thereunder.
(3)In this section “statutory redundancy scheme” means a scheme for the elimination or reduction of redundant works, machinery or plant, or for other similar purposes, to which effect is given by or under any Act, whether passed before or after this Act.
Marginal Citations
M77Source-1970 s.410
[F1758Chapter 5AU.K.Share loss relief
Textual Amendments
F1758Pt. 13 Ch. 5A created (6.4.2007 with effect in accordance with s. 1034(1) of the affecting Act) by virtue of Income Tax Act 2007 (c. 3), Sch. 1 para. 117(3) (with Sch. 2)
Relief for losses on unquoted shares in trading companiesU.K.
573 Relief for companies.U.K.
F1759. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1759Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
Modifications etc. (not altering text)
C48S. 573 transposed from Pt. 13 Ch. 6 to Pt. 13 Ch. 5A (6.4.2007 with effect in accordance with s. 1034(1) of the affecting Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 117(3) (with Sch. 2)
575 Exclusion of relief under section 573 F1760. . . in certain cases.U.K.
F1761. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1760Words in s. 575 sidenote repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 119(2), Sch. 3 Pt. 1 (with Sch. 2)
F1761Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
Modifications etc. (not altering text)
C49S. 575 transposed from Pt. 13 Ch. 6 to Pt. 13 Ch. 5A (6.4.2007 with effect in accordance with s. 1034(1) of the affecting Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 119(7) (with Sch. 2)
576 Provisions supplementary to [F1762sections 573 and 575].U.K.
F1763. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1762Words in s. 576 sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 120(2) (with Sch. 2)
F1763Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
Modifications etc. (not altering text)
C50S. 576 transposed from Pt. 13 Ch. 6 to Pt. 13 Ch. 5A (6.4.2007 with effect in accordance with s. 1034(1) of the affecting Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 120(7) (with Sch. 2)
[F1764576AQualifying trading companiesU.K.
F1765. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1764S. 576A inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 121 (with Sch. 2)
F1765Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1766Qualifying trading companies: the requirementsU.K.
Textual Amendments
F1766S. 576B and preceding cross-heading inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 122 (with Sch. 2)
576BThe trading requirementU.K.
F1767. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1767Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1768576CCeasing to meet the trading requirement because of administration or receivershipU.K.
F1769. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1768S. 576C inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 123 (with Sch. 2)
F1769Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1770576DThe control and independence requirementU.K.
F1771. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1770S. 576D inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 124 (with Sch. 2)
F1771Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1772576EThe qualifying subsidiaries requirementU.K.
F1773. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1772S. 576E inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 125 (with Sch. 2)
F1773Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1774576FThe property managing subsidiaries requirementU.K.
F1775. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1774S. 576F inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 126 (with Sch. 2)
F1775Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1776576GThe gross assets requirementU.K.
F1777. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1776S. 576G inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 127 (with Sch. 2)
F1777Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1778576HThe unquoted status requirementU.K.
F1779. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1778S. 576H inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 128 (with Sch. 2)
F1779Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1780576IPower to amend requirements by Treasury orderU.K.
F1781. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F1780S. 576I inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 129 (with Sch. 2)
F1781Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1782Qualifying trading companies: supplementary provisionsU.K.
Textual Amendments
F1782S. 576J and preceding cross-heading inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 130 (with Sch. 2)
576JRelief after an exchange of shares for shares in another companyU.K.
F1783. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1783Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1784576KSubstitution of new shares for old sharesU.K.
F1785. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F1784S. 576K inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 131 (with Sch. 2)
F1785Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
[F1786SupplementalU.K.
Textual Amendments
F1786S. 576L and preceding cross-heading inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 132 (with Sch. 2)
576LInterpretation of ChapterU.K.
F1787. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F1787Pt. 13 Ch. 5A (ss. 573, 575-576L) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 88, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER VIU.K. OTHER PROVISIONS
Modifications etc. (not altering text)
C51Pt 13 Ch. 6: ss. 573, 575 and 576 transposed to Pt. 13 Ch. 5A (6.4.2007 with effect in accordance with s. 1034(1) of the affecting Act) by Income Tax Act 2007 (c. 3), Sch. 1 paras. 117(3), 119(7), 120(7) (with Sch. 2)
Relief for losses on unquoted shares in trading companiesU.K.
574 Relief for individuals.U.K.
F1788. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1788S. 574 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 118, Sch. 3 Pt. 1 (with Sch. 2)
MiscellaneousU.K.
577 Business entertaining expenses.U.K.
F1789. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1789S. 577 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 191, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1790577A Expenditure involving crime.U.K.
F1791. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1790S. 577A inserted (with application in accordance with s. 123(2) of the amending Act) by Finance Act 1993 (c. 34), s. 123(1)(2)
F1791S. 577A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 192, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
578 Housing grants.U.K.
F1792. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1792S. 578 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 193, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1793578A Expenditure on car hireU.K.
F1794. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1793Ss. 578A, 578B inserted (with effect in accordance with s. 579 of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 52 (with Sch. 3 para. 113)
F1794Ss. 578A, 578B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 194, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
578B Expenditure on car hire: supplementaryU.K.
F1795. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1793Ss. 578A, 578B inserted (with effect in accordance with s. 579 of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 52 (with Sch. 3 para. 113)
F1795Ss. 578A, 578B repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 194, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
579 Statutory redundancy payments.U.K.
F1796. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1796Ss. 579, 580 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 195, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
580 Provisions supplementary to section 579.U.K.
F1797. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1797Ss. 579, 580 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 195, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1798580A Relief from tax on annual payments under certain insurance policies.U.K.
F1799. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1798Ss. 580A, 580B inserted (with effect in accordance with s. 143(2)-(5) of the amending Act) by Finance Act 1996 (c. 8), s. 143(1)
F1799Ss. 580A-580C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 240, Sch. 3 (with Sch. 2)
580B Meaning of “self-contained” for the purposes of s.580A.U.K.
F1800. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1798Ss. 580A, 580B inserted (with effect in accordance with s. 143(2)-(5) of the amending Act) by Finance Act 1996 (c. 8), s. 143(1)
F1800Ss. 580A-580C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 240, Sch. 3 (with Sch. 2)
[F1801580CRelief from tax on annual payments under immediate needs annuitiesU.K.
F1802. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1801S. 580C inserted (with effect in accordance with s. 147(6) of the amending Act) by Finance Act 2004 (c. 12), s. 147(3)
F1802Ss. 580A-580C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 240, Sch. 3 (with Sch. 2)
581 Borrowing in foreign currency by local authorities and statutory corporations.U.K.
F1803. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1803S. 581 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 241, Sch. 3 (with Sch. 2)
[F1804581AInterest on foreign currency securities etc.U.K.
F1805. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1804S. 581A inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 242 (with Sch. 2)
F1805S. 581A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 133, Sch. 3 Pt. 1 (with Sch. 2)
582 Funding bonds issued in respect of interest on certain debts.U.K.
F1806. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1806S. 582 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 196, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1807582A Designated international organisations: miscellaneous exemptions.U.K.
F1808. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1807S. 582A inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 118(1)
F1808S. 582A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 135, Sch. 3 Pt. 1 (with Sch. 2)
583 Inter-American Development Bank.U.K.
F1809. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1809S. 583 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 244, Sch. 3 (with Sch. 2)
584 Relief for unremittable overseas incomeU.K.
F1810. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1810S. 584 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 197, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
585 Relief from tax on delayed remittances.U.K.
F1811. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1811S. 585 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 246, Sch. 3 (with Sch. 2)
586 Disallowance of deductions for war risk premiums.U.K.
F1812. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1812Ss. 586, 587 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 198, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
587 Disallowance of certain payments in respect of war injuries to employees.U.K.
F1813. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1813Ss. 586, 587 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 198, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F1814587A New issues of securities: extra return.U.K.
F1815. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1814S. 587A inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 54, Sch. 12 para. 1 (with application as referred to in Sch. 12 para. 5 of that Act)
F1815S. 587A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 136, Sch. 3 Pt. 1 (with Sch. 2)
[F1816587B[F1817Gifts of shares, securities and real property to charities etc]U.K.
F1818. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1816S. 587B inserted (with effect in accordance with s. 43(3) of the amending Act) by Finance Act 2000 (c. 17), s. 43(1)
F1817S. 587B sidenote substituted (with effect in accordance with s. 97(6) of the amending Act) by Finance Act 2002 (c. 23), s. 97(4)
F1818S. 587B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 89, Sch. 3 Pt. 1 (with Sch. 2)
[F1819587BAQualifying interests in land held jointlyU.K.
F1820. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1819S. 587BA inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 138 (with Sch. 2)
F1820S. 587BA repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 90, Sch. 3 Pt. 1 (with Sch. 2)
[F1821587C Supplementary provision for gifts of real propertyU.K.
F1822. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1821S. 587C inserted (with effect in accordance with s. 97(6) of the amending Act) by Finance Act 2002 (c. 23), s. 97(5)
F1822S. 587C repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 91, Sch. 3 Pt. 1 (with Sch. 2)
588 Training courses for employees.U.K.
F1823. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1823S. 588 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 200, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
589 Qualifying courses of training etc.U.K.
F1824. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1824S. 589 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 68, Sch. 8 Pt. 1 (with Sch. 7)
[F1825589A Counselling services for employees.U.K.
F1826. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1825Ss. 589A, 589B inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 108
F1826S. 589A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 201, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F1827589B Qualifying counselling services etc.U.K.
(1)F1828. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1828. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1828. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1829(4)F1828. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4A)F1828. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(5)F1830. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1827Ss. 589A, 589B inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 108
F1828S. 589B(1)-(4A) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 70(2), Sch. 8 Pt. 1 (with Sch. 7)
F1829S. 589B(4)(4A) substituted for s. 589B(4) (with effect in accordance with s. 57(4) of the amending Act) by Finance Act 2001 (c. 9), Sch. 12 Pt. 2 para. 13
F1830S. 589B(5) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 202, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
PART XIVU.K. PENSION SCHEMES, SOCIAL SECURITY BENEFITS, LIFE ANNUITIES ETC.
CHAPTER IU.K. RETIREMENT BENEFIT SCHEMES
Modifications etc. (not altering text)
C52Pt. 14 Ch. 1 (ss. 590-612) modified (31.3.1995) by Judicial Pensions and Retirement Act 1993 (c. 8), ss. 18, 19(4), 31(2); S.I. 1995/631, art. 2
Approval of schemesU.K.
590 Conditions for approval of retirement benefit schemes.U.K.
F1831. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1831Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1832590A Section 590: supplementary provisions.U.K.
F1833. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1832Ss. 590A-590C inserted by Finance Act 1989 (c. 26), s. 75, Sch. 6 paras. 4, 18(4)
F1833Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1834590B Section 590: further supplementary provisions.U.K.
F1835. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1834Ss. 590A-590C inserted by Finance Act 1989 (c. 26), s. 75, Sch. 6 paras. 4, 18(4)
F1835Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1836590C Earnings cap.U.K.
F1837. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1836Ss. 590A-590C inserted by Finance Act 1989 (c. 26), s. 75, Sch. 6 paras. 4, 18(4)
F1837Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
591 Discretionary approval.U.K.
F1838. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1838Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1839591A Effect on approved schemes of regulations under section 591.U.K.
F1840. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1839S. 591A inserted by Finance Act 1991 (c. 31), s.35
F1840Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1841591B Cessation of approval: general provisions.U.K.
F1842. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1841S. 591B inserted (retrospectively) by Finance Act 1991 (c. 31), s. 36(1)(3)
F1842Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1843591C Cessation of approval: tax on certain schemes.U.K.
F1844. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1843Ss. 591C, 591D inserted (with effect in accordance with s. 61(3) of the amending Act) by Finance Act 1995 (c. 4), s. 61(1)
F1844Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
591D Section 591C: supplementary.U.K.
F1845. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1843Ss. 591C, 591D inserted (with effect in accordance with s. 61(3) of the amending Act) by Finance Act 1995 (c. 4), s. 61(1)
F1845Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
Tax reliefsU.K.
592 Exempt approved schemes.U.K.
F1846. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1846Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
593 Relief by way of deductions from contributions.U.K.
F1847. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1847Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
594 Exempt statutory schemes.U.K.
F1848. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1848Ss. 590-594 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
Charge to tax in certain casesU.K.
595 Charge to tax in respect of certain sums paid by employer etc.U.K.
F1849. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1849Ss. 595, 596 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 74, Sch. 8 Pt. 1 (with Sch. 7)
596 Exceptions from section 595.U.K.
F1850. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1850Ss. 595, 596 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 74, Sch. 8 Pt. 1 (with Sch. 7)
[F1851596A Charge to tax: benefits under non-approved schemes.U.K.
F1852. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1851Ss. 596A, 596B inserted (with effect in accordance with Sch. 6 para. 18(7) of the amending Act) by Finance Act 1989 (c. 26), Sch. 6 para. 9
F1852Ss. 596A-596C repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 75, Sch. 8 Pt. 1 (with Sch. 7)
[F1853596B Section 596A: supplementary provisions.U.K.
F1854. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1853Ss. 596A, 596B inserted (with effect in accordance with Sch. 6 para. 18(7) of the amending Act) by Finance Act 1989 (c. 26), Sch. 6 para. 9
F1854Ss. 596A-596C repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 75, Sch. 8 Pt. 1 (with Sch. 7)
[F1855596C Notional interest treated as paid if amount charged in respect of beneficial loan.U.K.
F1856. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1855S. 596C inserted (with effect in accordance with s. 93(4) of the amending Act) by Finance Act 1998 (c. 36), s. 93(3)
F1856Ss. 596A-596C repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 75, Sch. 8 Pt. 1 (with Sch. 7)
597 Charge to tax: pensions.U.K.
F1857. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1857S. 597 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 76, Sch. 8 Pt. 1 (with Sch. 7)
598 Charge to tax: repayment of employee’s contributions.U.K.
F1858. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1858Ss. 598-599A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36) (with savings in S.I. 2006/5072, arts. 1(1), 38)
599 Charge to tax: commutation of entire pension in special circumstances.U.K.
F1859. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1859Ss. 598-599A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36) (with savings in S.I. 2006/5072, arts. 1(1), 38)
[F1860599A Charge to tax: payments out of surplus funds.U.K.
F1861. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1860S. 599A inserted (with effect in accordance with Sch. 6 para. 18(9) of the amending Act) by Finance Act 1989 (c. 26), Sch. 6 para. 12
F1861Ss. 598-599A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36) (with savings in S.I. 2006/5072, arts. 1(1), 38)
600 Charge to tax: unauthorised payments to or for employees.U.K.
F1862. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1862S. 600 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 78, Sch. 8 Pt. 1 (with Sch. 7)
601 Charge to tax: payments to employers.U.K.
F1863. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1863Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
602 Regulations relating to pension fund surpluses.U.K.
F1864. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1864Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
603 Reduction of surpluses.U.K.
F1865. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1865Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
Supplementary provisionsU.K.
604 Application for approval of a scheme.U.K.
F1866. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1866Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
605 Information.U.K.
F1867. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1867Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1868605A False statements etc.U.K.
F1869. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1868S. 605A inserted (with application in accordance with s. 106(2) of the amending Act) by Finance Act 1994 (c. 9), s. 106(1)
F1869Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
606 Default of administrator etc.U.K.
F1870. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1870Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1871606A Recourse to scheme members.U.K.
F1872. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1871S. 606A inserted (with effect in accordance with Sch. 15 para. 6(2) of the amending Act) by Finance Act 1998 (c. 36), Sch. 15 para. 6(1)
F1872Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
607 Pilots’ benefit fund.U.K.
F1873. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1873Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
608 Superannuation funds approved before 6th April 1980.U.K.
F1874. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1874Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
609 Schemes approved before 23rd July 1987.U.K.
F1875. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1875Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
610 Amendments of schemes.U.K.
F1876. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1876Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
611 Definition of “retirement benefits scheme”.U.K.
F1877. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1877Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1878611A Definition of relevant statutory scheme.U.K.
F1879. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1878S. 611A inserted (14.3.1989) by Finance Act 1989 (c. 26), Sch. 6 paras. 15, 18(1)
F1879Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1880611AA Definition of the administrator.U.K.
F1881. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1880S. 611AA inserted (with application in accordance with s. 103(3) of the amending Act) by Finance Act 1994 (c. 4), s. 103(1)
F1881Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
611A Definition of relevant statutory scheme.U.K.
F1879. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1878S. 611A inserted (14.3.1989) by Finance Act 1989 (c. 26), Sch. 6 paras. 15, 18(1)
F1879Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
612 Other interpretative provisions, and regulations for purposes of this Chapter.U.K.
F1882. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1882Ss. 601-612 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
CHAPTER IIU.K. OTHER PENSION FUNDS AND SOCIAL SECURITY BENEFITS AND CONTRIBUTIONS
613 Parliamentary pension funds.U.K.
[F1883(1)M78The salary of a Member of the House of Commons shall, for all the purposes of the Income Tax Acts, be treated as reduced by the [F1884amounts deducted in pursuance of section 4 of the House of Commons Members' Fund Act 2016]; but a Member shall not by reason of any such deduction be entitled to relief under any other provision of the Income Tax Acts.]
(2)F1885. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F1886. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)M79The F1887. . . trustees of—
(a)the House of Commons Members’ Fund [F1888specified in section 1 of the 2016 Act];
(b)F1889. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1890(bb)F1889. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(c)F1889. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(d)F1889. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
shall be entitled to exemption from income tax in respect of all income derived from [F1891that Fund] or any investment of [F1891that Fund].
A claim under this subsection shall be made to the Board.
Textual Amendments
F1883S. 613(1) (which was repealed by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 83, Sch. 8 Pt. 1) restored (retrospectively) by Finance Act 2005 (c. 7), Sch. 10 para. 63
F1884Words in s. 613(1) substituted (12.8.2016) by House of Commons Members' Fund Act 2016 (c. 18), ss. 8(2)(a), 10
F1885S. 613(2) omitted (12.8.2016) by virtue of House of Commons Members' Fund Act 2016 (c. 18), ss. 8(2)(b), 10
F1886S. 613(3) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 83, Sch. 8 Pt. 1 (with Sch. 7)
F1887Word in s. 613(4) repealed (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 26(a), Sch. 42 Pt. 3, Note (with Sch. 36)
F1888Words in s. 613(4)(a) substituted (12.8.2016) by House of Commons Members' Fund Act 2016 (c. 18), ss. 8(2)(c), 10
F1889S. 613(4)(b)-(d) repealed (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 26(a), Sch. 42 Pt. 3, Note (with Sch. 36)
F1890S. 613(4)(bb) inserted (with effect in accordance with s. 52(2) of the amending Act) by Finance Act 1999 (c. 16), Sch. 5 para. 4
F1891Words in s. 613(4) substituted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 26(b) (with Sch. 36)
Marginal Citations
M78Source-1970 s.211(1), (4)
M79Source-1970 s.211(2) 1981 s.50(1); PPA 1987 Sch.3 2(1)
614 Exemptions and reliefs in respect of income from investments etc. of certain pension schemes.U.K.
(1)F1892. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)M80Any interest or dividends received by the person in whom is vested any of the Family Pension Funds mentioned in section 273 of the M81Government of India Act 1935, and having effect as a scheme made under section 2 of the M82Overseas Pensions Act 1973, on sums forming part of that fund shall be exempt from income tax.
[F1893(2A)The reference in subsection (2) above to interest on sums forming part of a fund include references to any amount which is treated as income by virtue of [F1894Chapter 8 of Part 4 of ITTOIA 2005 (profits from deeply] discounted securities) and derives from any investment forming part of that fund.]
(3)M83Income derived from investments or deposits of any fund referred to in [F1895section 648, 649, 650 or 651 of ITEPA 2003] shall not be charged to income tax, and any income tax deducted from any such income shall be repaid by the Board to the persons entitled to receive the income.
(4)M84In respect of income derived from investments or deposits of the Overseas Service Pensions Fund established pursuant to section 7(1) of the M85Overseas Aid Act 1966, the Board shall give by way of repayment such relief from income tax as is necessary to secure that the income is exempt to the like extent (if any) as if it were income of a person [F1896F1897... and not resident] in the United Kingdom.
(5)M86In respect of dividends and other income derived from investments, deposits or other property of a superannuation fund to which section 615(3) applies the Board shall give by way of repayment such relief from income tax as is necessary to secure that the income is exempt to the like extent (if any) as if it were income of a person [F1898F1899... not resident] in the United Kingdom.
(6)M87A claim under this section shall be made to the Board.
Textual Amendments
F1892S. 614(1) repealed (3.5.1994) by Finance Act 1994 (c. 9), Sch. 26 Pt. 5(22)
F1893S. 614(2A) inserted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 34 (with Sch. 15)
F1894Words in s. 614(2A) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 261 (with Sch. 2)
F1895Words in s. 614(3) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 84 (with Sch. 7)
F1896Words in s. 614(4) substituted (with effect in accordance with Sch. 46 para. 72 of the amending Act) by Finance Act 2013 (c. 29), Sch. 46 para. 28(a)
F1897Words in s. 614(4) omitted (for the tax year 2025-26 and subsequent tax years) by virtue of Finance Act 2025 (c. 8), s. 40(4), Sch. 9 para. 25
F1898Words in s. 614(5) substituted (with effect in accordance with Sch. 46 para. 72 of the amending Act) by Finance Act 2013 (c. 29), Sch. 46 para. 28(b)
F1899Words in . 614(5) omitted (for the tax year 2025-26 and subsequent tax years) by virtue of Finance Act 2025 (c. 8), s. 40(4), Sch. 9 para. 25
Marginal Citations
M80Source-1970 s.213(1)
M83Source-1970 s.214(2), 216(2); 1973 s.53(1)
M84Source-1970 s.217(2), (4)
M86Source-1970 s.218(1)
M87Source-1970 s.212(3), 213(1), 214(3), 216(2), 217(2), 218(1); 1987 Sch.15 2(13)
615 Exemption from tax in respect of certain pensions.U.K.
(1)F1900. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F1900. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)M88Where an annuity is paid from a superannuation fund to which this subsection applies to a person who is not resident in the United Kingdom, income tax shall not be deducted from any payment of the annuity or accounted for under [F1901Chapter 6 of Part 15 of ITA 2007 (deduction from annual payments and patent royalties)] by the trustees or other persons having the control of the fund.
(4)F1900. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F1900. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)M89Subsection (3) above applies to any superannuation fund which—
(a)is bona fide established under irrevocable trusts in connection with some trade or undertaking carried on wholly or partly outside the United Kingdom;
(b)has for its sole purpose [F1902(subject to any enactment or Northern Ireland legislation requiring or allowing provision for the value of any rights to be transferred between schemes or between members of the same scheme)] the provision of superannuation benefits in respect of persons’ employment in the trade or undertaking wholly outside the United Kingdom; F1903. . .
(c)is recognised by the employer and employed persons in the trade or undertaking; [F1904and]
[F1905(d)meets the benefit accrual condition (see subsection (6A));]
and for the purposes of this subsection duties performed in the United Kingdom the performance of which is merely incidental to the performance of other duties outside the United Kingdom shall be treated as performed outside the United Kingdom .
[F1906(6A)The benefit accrual condition is—
(a)that, in the case of any money purchase arrangement relating to a member of the fund that is not a cash balance arrangement, no contributions are made under the arrangement on or after 6 April 2017;
(b)that, in the case of any cash balance arrangement relating to a member of the fund, there is no increase on or after 6 April 2017 in the value of any person's rights under the arrangement;
(c)that, in the case of any defined benefits arrangement relating to a member of the fund, there is no increase on or after 6 April 2017 in the value of any person's rights under the arrangement; and
(d)that, in the case of any arrangement relating to a member of the fund that is neither a money purchase arrangement nor a defined benefits arrangement—
(i)no contributions are made under the arrangement on or after 6 April 2017, and
(ii)there is no increase on or after 6 April 2017 in the value of any person's rights under the arrangement.
(6B)For the purposes of subsection (6A)(b)—
(a)whether there is an increase in the value of a person's rights is to be determined by reference to whether there is an increase in the amount that would, on the valuation assumptions, be available for the provision of benefits under the arrangement to or in respect of the person (and, if there is, the amount of the increase), but
(b)in the case of rights that accrued to a person before 6 April 2017, ignore increases in the value of the rights if in no tax year do they exceed the relevant percentage.
(6C)For the purposes of subsection (6A)(c)—
(a)whether there is an increase in the value of a person's rights is to be determined by reference to whether there is an increase in the benefits amount as defined by paragraph 14(7) of Schedule 18 to the Finance Act 2011, but
(b)in the case of rights that accrued to a person before 6 April 2017, ignore increases in the value of the rights if in no tax year do they exceed the relevant percentage.
(6D)For the purposes of subsection (6A)(d)(ii), regulations made by the Commissioners for Her Majesty's Revenue and Customs may make provision—
(a)for determining whether there is an increase in the value of a person's rights,
(b)for determining the amount of any increase, and
(c)for ignoring the whole or part of any increase;
and regulations under this subsection may make provision having effect in relation to times before the regulations are made.
(6E)In this section, “relevant percentage”, in relation to a tax year, means—
(a)where, on 20 March 2017, the rules of the fund include provision for the value of the rights of a person to increase during the tax year at an annual rate specified in those rules, that rate, or
(b)in any other case, the percentage by which the consumer prices index for September in the previous tax year is higher than it was for the September in the tax year before that (or, if greater, 0%).
(6F)The Commissioners for Her Majesty's Revenue and Customs may by regulations make provision—
(a)so as to change, or modify the effect of, the benefit accrual condition;
(b)as to the matters to be taken into account in determining whether the benefit accrual condition is met;
(c)for a superannuation fund to be treated to any extent as meeting or not meeting the benefit accrual condition.
(6G)Provision under subsection (6D) or (6F) may be made by amending this section.]
(7)[F1907M90For the purposes of this section—
“arrangement”, in relation to a member of a superannuation fund, means an arrangement relating to the member under the fund;
a money purchase arrangement relating to a member of a superannuation fund is a “cash balance arrangement” at any time if, at that time, all the benefits that may be provided to or in respect of the member under the arrangement are cash balance benefits;
an arrangement relating to a member of a superannuation fund is a “defined benefits arrangement” at any time if, at that time, all the benefits that may be provided to or in respect of the member under the arrangement are defined benefits;
an arrangement relating to a member of a superannuation fund is a “money purchase arrangement” at any time if, at that time, all the benefits that may be provided to or in respect of the member under the arrangement are money purchase benefits;
“cash balance benefits”, “defined benefits” and “money purchase benefits” have the meaning given by section 152 of the Finance Act 2004, but for this purpose reading references in that section to a pension scheme as references to a superannuation fund;
“member”, in relation to a superannuation fund, has the meaning given by section 151 of the Finance Act 2004, but for this purpose reading references in that section to a pension scheme as references to a superannuation fund;]
“pension” includes a gratuity or any sum payable on or in respect of death or, in the case of a pension falling within subsection (2)(g) above, ill-health, and a return of contributions with or without interest thereon or any other addition thereto;
“overseas territory” means any territory or country outside the United Kingdom;
“the Pensions (Increase) Acts” means the M91Pensions (Increase) Act 1971 and any Act passed after that Act for purposes corresponding to the purposes of that Act;
“United Kingdom trust territory” means a territory administered by the government of the United Kingdom under the trusteeship system of the United Nations;
[F1908“the valuation assumptions” has the meaning given by section 277 of the Finance Act 2004.]
(8)F1900. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F1909(9)For the purposes of this section, a person shall be taken to be employed in the public service of an overseas territory at any time when—
(a)he is employed in any capacity under the government of that territory, or under any municipal or other local authority in it,
(b)he is employed, in circumstances not falling within paragraph (a) above, by a body corporate established for any public purpose in that territory by an enactment of a legislature empowered to make laws for that territory, or
(c)he is the holder of a public office in that territory in circumstances not falling within either paragraph (a) or (b).
(10)For the purposes of subsection (9), references to the government of an overseas territory include references to a government constituted for two or more overseas territories, and to any authority established for the purpose of providing or administering services which are common to, or relate to matters of common interest to, two or more such territories.]
[F1910(11)Where the conditions in subsection (6)(a) to (c) are met in the case of a superannuation fund (“the actual fund”)—
(a)any disqualifying contributions made under an arrangement relating to a member of the actual fund are treated for the purposes of the Income Tax Acts as instead made under an arrangement relating to the member under a separate superannuation fund (“the shadow fund” for the actual fund),
(b)any disqualifying increase in the value of a person's rights under an arrangement relating to a member of the actual fund is treated for the purposes of the Income Tax Acts as instead being an increase under an arrangement relating to the member under the shadow fund for the actual fund, and
(c)any reference in this or any other Act (including the reference in subsection (3) and any reference enacted after the coming into force of this subsection) to a fund, or superannuation fund, to which subsection (3) applies does not include so much of the actual fund as—
(i)represents any contribution treated as made under, or any increase in the value of any rights treated as an increase under, the shadow fund of the actual fund or the shadow fund of any other superannuation fund, or
(ii)arises, or (directly or indirectly) derives, from anything within sub-paragraph (i) or this sub-paragraph.
(12)For the purposes of subsection (11) a contribution, or an increase in the value of any rights, is “disqualifying” if it would (ignoring that subsection) cause the benefit accrual condition not to be met in the case of the actual fund.
(13)For the purposes of the provisions of this section relating to the benefit accrual condition, where there is a recognised transfer—
(a)any transfer of sums or assets to the recipient fund by the recognised transfer is to be categorised as not being “a contribution” to the recipient fund, and
(b)any increase in the value of rights under the recipient fund that occurs at the time of the recognised transfer is to be treated as not being an increase in that value if the increase is solely a result of the transfer effected by the recognised transfer.
(14)For the purposes of subsection (13), where there is a transfer such that sums or assets held for the purposes of, or representing accrued rights under, an arrangement relating to a member of a superannuation fund (“the transferor fund”) are transferred so as to become held for the purposes of, or to represent rights under, an arrangement relating to that person as a member of another superannuation fund, the transfer is a “recognised transfer” if—
(a)the conditions in subsection (6)(a) to (c) are met in the case of each of the funds, and
(b)none of the sums and assets transferred—
(i)represents any contribution treated as made under, or any increase in the value of any rights treated as an increase under, the shadow fund of the transferor fund or the shadow fund of any other superannuation fund, or
(ii)arises, or (directly or indirectly) derives, from anything within sub-paragraph (i) or this sub-paragraph.]
Textual Amendments
F1900S. 615(1)(2)(4)(5)(8) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 85, Sch. 8 Pt. 1 (with Sch. 7)
F1901Words in s. 615(3) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 140 (with Sch. 2)
F1902Words in s. 615(6)(b) inserted (27.7.1999) by Finance Act 1999 (c. 16), Sch. 10 para. 11
F1903Word in s. 615(6)(b) omitted (6.4.2017) by virtue of Finance Act 2017 (c. 10), Sch. 3 para. 3(2)(a)(6)
F1904Word in s. 615(6)(c) inserted (6.4.2017) by Finance Act 2017 (c. 10), Sch. 3 para. 3(2)(b)(6)
F1905S. 615(6)(d) inserted (6.4.2017) by Finance Act 2017 (c. 10), Sch. 3 para. 3(2)(c)(6)
F1906S. 615(6A)-(6G) inserted (6.4.2017) by Finance Act 2017 (c. 10), Sch. 3 para. 3(3)(6)
F1907Words in s. 615(7) substituted (6.4.2017) by Finance Act 2017 (c. 10), Sch. 3 para. 3(4)(a)(6)
F1908Words in s. 615(7) inserted (6.4.2017) by Finance Act 2017 (c. 10), Sch. 3 para. 3(4)(b)(6)
F1909S. 615(9)(10) inserted (17.6.2002) by International Development Act 2002 (c. 1), s. 20(2), Sch. 3 para. 9(3) (with Sch. 5); S.I. 2002/1408, art. 2
F1910S. 615(11)-(14) inserted (6.4.2017) by Finance Act 2017 (c. 10), Sch. 3 para. 3(5)(6)
Marginal Citations
M88Source-1970 s.218(3)
M89Source-1970 s.218(4)
M90Source-1970 s.214(5), 215(3), 216(4), 217(4)
616 Other overseas pensions.U.K.
F1911. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1911S. 616 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 86, Sch. 8 Pt. 1 (with Sch. 7)
617 Social security benefits and contributions.U.K.
F1912. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1912S. 617 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 203, Sch. 3 Pt. 1 (with Sch. 2 Pts 1, 2)
[F1913617A Tax credits under Part 1 of Tax Credits Act 2002U.K.
F1914. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1913S. 617A inserted (prosp.) by Tax Credits Act 2002 (c. 21), s. 61, Sch. 3 para. 14 (the insertion being brought into force at 6.4.2003 by S.I. 2003/962, art. 2(3)(d)(iii))
F1914S. 617A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 88, Sch. 8 Pt. 1 (with Sch. 7)
CHAPTER IIIU.K. RETIREMENT ANNUITIES
618 Termination of relief under this Chapter, and transitional provisions.U.K.
F1915. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1915Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
619 Exemption from tax in respect of qualifying premiums.U.K.
F1916. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1916Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
620 Qualifying premiums.U.K.
F1917. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1917Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
621 Other approved contracts.U.K.
F1918. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1918Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
622 Substituted retirement annuity contracts.U.K.
F1919. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1919Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
623 Relevant earnings.U.K.
F1920. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1920Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
624 Sponsored superannuation schemes and controlling directors.U.K.
F1921. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1921Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
625 Carry-forward of unused relief under section 619.U.K.
F1922. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1922Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
626 Modification of section 619 in relation to persons over 50.U.K.
F1923. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1923Ss. 618-626 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
F1924627 Lloyd’s underwriters.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1924S. 627 repealed (with effect as mentioned in s. 228(4) of the repealing Act) by Finance Act 1994 (c. 9), s. 228(2)(a), Sch. 26 Pt. 5(25), Note 1
628 Partnership retirement annuities.U.K.
F1925. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1925S. 628 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
629 Annuity premiums of Ministers and other officers.U.K.
M92(1)For the purposes of this Chapter so much of any salary which—
(a)is payable to the holder of a qualifying office who is also a Member of the House of Commons, and
(b)is payable for a period in respect of which the holder is not a participant in relation to that office in arrangements contained in the Parliamentary pension scheme but is a participant in relation to his membership of the House of Commons in any such arrangements, or for any part of such a period,
as is equal to the difference between a Member’s pensionable salary and the salary which (in accordance with any such resolution as is mentioned in subsection (3)(a) below) is payable to him as a Member holding that qualifying office shall be treated as remuneration from the office of Member and not from the qualifying office.
(2)In this section—
“Member’s pensionable salary” means a Member’s ordinary salary under any resolution of the House of Commons which, being framed otherwise than as an expression of opinion, is for the time being in force relating to the remuneration of Members or, if the resolution provides for a Member’s ordinary salary thereunder to be treated for pension purposes as being at a higher rate, a notional yearly salary at that higher rate;
“qualifying office” means an office mentioned in section 2(2)(b), (c) or (d) of the Parliamentary and other M93Pensions Act 1987;
“the Parliamentary pension scheme” has the same meaning as in that Act;
and without prejudice to the power conferred by virtue of paragraph 13 of Schedule 1 to that Act, regulations under section 2 of that Act may make provision specifying the circumstances in which a person is to be regarded for the purposes of this section as being or not being a participant in relation to his Membership of the House of Commons, or in relation to any office, in arrangements contained in the Parliamentary pension scheme.
(3)In subsection (2) above “a Member’s ordinary salary”, in relation to any resolution of the House of Commons, means—
(a)if the resolution provides for salary to be paid to Members at different rates according to whether or not they are holders of particular offices, or are in receipt of salaries or pensions as the holders or former holders of particular offices, a Member’s yearly salary at the higher or highest rate; and
(b)in any other case, a Member’s yearly salary at the rate specified in or determined under the resolution.
Modifications etc. (not altering text)
C53S. 629 applied (with modifications) (with effect in accordance with s. 52(2) of the affecting Act) by Finance Act 1999 (c. 16), Sch. 5 para. 6
Marginal Citations
M92Source-1970 s.229
CHAPTER IVU.K. PERSONAL PENSION SCHEMES
Modifications etc. (not altering text)
C54Pt. 14 Ch. 5 excluded (1.5.1995) by Finance Act 1995 (c. 4), s. 60(5)
PreliminaryU.K.
630 Interpretation.U.K.
F1926. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1926Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
631 Approval of schemes.U.K.
F1927. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1927Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1928631A Conversion of certain approved retirement benefits schemes.U.K.
F1929. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1928S. 631A inserted (28.7.2000) by Finance Act 2000 (c. 17), Sch. 13 para. 7 (with Sch. 13 Pt. 2)
F1929Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
Restrictions on approvalU.K.
632 Establishment of schemes.U.K.
F1930. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1930Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1931632A Eligibility to make contributions.U.K.
F1932. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1931Ss. 632A, 632B inserted (6.4.2001) by Finance Act 2000 (c. 17), Sch. 13 para. 8 (with Sch. 13 Pt. 2)
F1932Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
632B Eligibility to make contributions: concurrent membership.U.K.
F1933. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1931Ss. 632A, 632B inserted (6.4.2001) by Finance Act 2000 (c. 17), Sch. 13 para. 8 (with Sch. 13 Pt. 2)
F1933Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
633 Scope of benefits.U.K.
F1934. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1934Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
634 Annuity to member.U.K.
F1935. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1935Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1936634A Income withdrawals by member.U.K.
F1937. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1936S. 634A inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 11 para. 4
F1937Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
635 Lump sum to member.U.K.
F1938. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1938Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
636 Annuity after death of member.U.K.
F1939. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1939Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1940636A Income withdrawals after death of member.U.K.
F1941. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1940S. 636A inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 11 para. 7
F1941Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
637 Death benefit.U.K.
F1942. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1942Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1943637A Return of contributions on or after death of member.U.K.
F1944. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1943Ss. 637, 637A substituted for s. 637 (1.5.1995) by Finance Act 1995 (c. 4), Sch. 11 para. 8
F1944Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
638 Other restrictions on approval.U.K.
F1945. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1945Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1946638ZA Personal pension arrangements with more than one pension date etc.U.K.
F1947. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1946S. 638ZA inserted (6.4.2001) by Finance Act 2000 (c. 17), Sch. 13 para. 14 (with Sch 13 Pt. 2)
F1947Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1948638A Power to prescribe restrictions on approval.U.K.
F1949. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1948S. 638A inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 94(1)
F1949Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
Tax reliefsU.K.
639 Member’s contributions.U.K.
F1950. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1950Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
640 Maximum amount of deductions.U.K.
F1951. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1951Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1952640A Earnings cap.U.K.
F1953. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1952S. 640A inserted (with effect in accordance with Sch. 7 para. 4(2) of the amending Act) by Finance Act 1989 (c. 26), Sch. 7 para. 4(1)
F1953Ss. 630-640A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
641 Carry-back of contributions.U.K.
F1954. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1954S. 641 repealed (with effect in accordance with Sch. 13 para. 17 of the repealing Act) by Finance Act 2000 (c. 17), Sch. 40 Pt, 2(4), Note 3 (with Sch. 13 Pt. 2)
[F1955641A Election for contributions to be treated as paid in previous year.U.K.
F1956. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1955S. 641A inserted (with effect in accordance with Sch. 13 para. 18(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 13 para. 18(1) (with Sch. 13 Pt. 2)
F1956S. 641A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
642 Carry-forward of relief.U.K.
F1957. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1957S. 642 repealed (with effect in accordance with Sch. 13 para. 19 of the repealing Act) by Finance Act 2000 (c. 17), Sch. 40 Pt, 2(4), Note 4 (with Sch. 13 Pt. 2)
643 Employer’s contributions and personal pension income etc.U.K.
F1958. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1958Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
644 Meaning of “relevant earnings”.U.K.
F1959. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1959Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
645 Earnings from pensionable employment.U.K.
F1960. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1960Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
646 Meaning of “net relevant earnings”.U.K.
F1961. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1961Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1962646A Earnings from associated employments.U.K.
F1963. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1962S. 646A inserted (with effect in accordance with Sch. 7 para. 8(2) of the amending Act) by Finance Act 1989 (c. 26), Sch. 7 para. 8(1)
F1963Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1964646B Presumption of same level of relevant earnings etc for 5 years.U.K.
F1965. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1964Ss. 646B, 646C inserted (with effect in accordance with Sch. 13 para. 22(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 13 para. 22(1) (with Sch. 13 Pt. 2)
F1965Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
646C Provisions supplementary to section 646B.U.K.
F1966. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1964Ss. 646B, 646C inserted (with effect in accordance with Sch. 13 para. 22(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 13 para. 22(1) (with Sch. 13 Pt. 2)
F1966Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1967646D Higher level contributions after cessation of actual relevant earnings: modification of section 646B.U.K.
F1968. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1967S. 646D inserted (with effect in accordance with Sch. 13 para. 23(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 13 para. 23(1) (with Sch. 13 Pt. 2)
F1968Ss. 643-646D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
Charge to taxU.K.
647 Unauthorised payments.U.K.
F1969. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1969Ss. 647-648A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 96, Sch. 8 Pt. 1 (with Sch. 7)
648 Contributions under unapproved arrangements.U.K.
F1970. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1970Ss. 647-648A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 96, Sch. 8 Pt. 1 (with Sch. 7)
U.K.
[F1971F1972. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1971S. 648A and preceding cross-heading inserted (with application in accordance with s. 109(2) of the amending Act) by Finance Act 1994 (c. 9), s. 109(1)
F1972Cross-heading preceding s. 648A omitted (1.5.1995) by virtue of Finance Act 1995 (c. 4), Sch. 11 para. 12
648A Annuities: charge under Schedule E.U.K.
F1973. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1971S. 648A and preceding cross-heading inserted (with application in accordance with s. 109(2) of the amending Act) by Finance Act 1994 (c. 9), s. 109(1)
F1973Ss. 647-648A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 96, Sch. 8 Pt. 1 (with Sch. 7)
[F1974648B Return of contributions after pension date.U.K.
F1975. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F1971S. 648A and preceding cross-heading inserted (with application in accordance with s. 109(2) of the amending Act) by Finance Act 1994 (c. 9), s. 109(1)
F1974S. 648B inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 11 para. 12
F1975Ss. 648B-651A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
MiscellaneousU.K.
649 Minimum contributions under Social Security Act 1986.U.K.
F1976. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1976Ss. 648B-651A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
650 Withdrawal of approval.U.K.
F1977. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1977Ss. 648B-651A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1978650A Charge on withdrawal of approval from arrangements.U.K.
F1979. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1978S. 650A inserted (with effect in accordance with s. 95(4) of the amending Act) by Finance Act 1998 (c. 36), s. 95(1)
F1979Ss. 648B-651A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
651 Appeals.U.K.
F1980. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1980Ss. 648B-651A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1981651A Information powers.U.K.
F1982. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1981S. 651A inserted (31.7.1998) by Finance Act 1998 (c. 36), s. 96(1)
F1982Ss. 648B-651A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
652 Information about payments.U.K.
F1983. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1983S. 652 repealed (1.10.2000) by Finance Act 1998 (c. 36), s. 96(4), Sch. 27 Pt. 3(21), Note; S.I. 2000/2319, art. 2
653 Information: penalties.U.K.
F1984. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1984Ss. 653-655 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1985653A Notices to be given to scheme administrator.U.K.
F1986. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1985S. 653A inserted (with effect in accordance with s. 97(2) of the amending Act) by Finance Act 1998 (c. 36), s. 97(1)
F1986Ss. 653-655 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
654 Remuneration of Ministers and other officers.U.K.
F1987. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1987Ss. 653-655 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
655 Transitional provisions.U.K.
F1988. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1988Ss. 653-655 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
CHAPTER VU.K. PURCHASED LIFE ANNUITIES
656 Purchased life annuities other than retirement annuities.U.K.
F1989. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1989Ss. 656-658 omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 8
657 Purchased life annuities to which section 656 applies.U.K.
F1990. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1990Ss. 656-658 omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 8
658 Supplementary.U.K.
F1991. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1991Ss. 656-658 omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 8
CHAPTER VIU.K. MISCELLANEOUS
[F1992658A Charges and assessments on administrators.U.K.
F1993. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1992S. 658A inserted (retrospectively) by Finance Act 1998 (c. 36), s. 98(1)
F1993S. 658A repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
F1994659 Financial futures and traded options.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1994S. 659 repealed (with effect in accordance with s. 81(7)(8) of the repealing Act) by Finance Act 1990 (c. 29), s. 81(4), Sch. 19 Pt. 4, Note 9
[F1995659A Futures and options.U.K.
(1)For the purposes of sections F1996. . . 613(4), 614(3) and (4) F1996. . . —
(a)“investments” (or “investment”) includes futures contracts and options contracts, and
(b)income derived from transactions relating to such contracts shall be regarded as income derived from (or income from) such contracts.
F1996. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)For the purposes of subsection (1) above a contract is not prevented from being a futures contract or an options contract by the fact that any party is or may be entitled to receive or liable to make, or entitled to receive and liable to make, only a payment of a sum (as opposed to a transfer of assets other than money) in full settlement of all obligations.]
Textual Amendments
F1995S. 659A inserted (with effect in accordance with s. 81(5) of the amending Act) by Finance Act 1990 (c. 29), s. 81(2)
F1996Words in s. 659A(1) repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F1997659B Definition of insurance company.U.K.
F1998. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F1997Ss. 659B, 659C inserted (with effect in accordance with s. 60 of the amending Act) by Finance Act 1995 (c. 4), s. 59(5)
F1998Ss. 659B-659D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
659C Effect of appointment or arrangements under section 659B.U.K.
F1999. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F1997Ss. 659B, 659C inserted (with effect in accordance with s. 60 of the amending Act) by Finance Act 1995 (c. 4), s. 59(5)
F1999Ss. 659B-659D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F2000659D Interpretation of provisions about pension sharing.U.K.
F2001. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2000S. 659D inserted (27.7.1999) by Finance Act 1999 (c. 16), Sch. 10 para. 17
F2001Ss. 659B-659D repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
[F2002659E Treatment of income from property investment LLPsU.K.
(1)The exemptions specified below do not apply to income derived from investments, deposits or other property held as a member of a property investment LLP [F2003(see section 1004 of ITA 2007)].
(2)The exemptions are those provided by—
F2004. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F2004. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
section 613(4) (Parliamentary pension funds),
section 614(3) (certain colonial, &c. pension funds),
section 614(4) (the Overseas Service Pension Fund),
section 614(5) (other pension funds for overseas employees),
F2004. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F2004. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)The income to which subsection (1) above applies includes relevant stock lending fees, in relation to any investments, to which any of the provisions listed in subsection (2) above would apply by virtue of section 129B.
(4)Section 659A (treatment of futures and options) applies for the purposes of subsection (1) above.]
Textual Amendments
F2002S. 659E inserted (6.4.2001) by Finance Act 2001 (c. 9), s. 76(2), Sch. 25 para. 2
F2003Words in s. 659E(1) inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 143 (with Sch. 2)
F2004S. 659E(2): entries repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
PART XVU.K. SETTLEMENTS
Modifications etc. (not altering text)
C55Pt. 15 modified (with effect in accordance with s. 105(1) of the modifying Act) by Finance Act 1996 (c. 8), Sch. 13 para. 6(1) (with Sch. 13 para. 16, Sch. 15)
[F2005Chapter IAU.K. Liability of settlor
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
Modifications etc. (not altering text)
C56Pt. 15 Ch. 1A excluded (with effect in accordance with s. 44(6) of the affecting Act) by Finance Act 2000 (c. 17), s. 44(1)
C57Pt. 15 Ch. 1A modified (with effect in accordance with s. 45(3) of the modifying Act) by Finance Act 2000 (c. 17), s. 45(1)
Main provisionsU.K.
660A Income arising under settlement where settlor retains an interest.U.K.
F2006. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2006Ss. 660A, 660B repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 271, Sch. 3 (with Sch. 2)
660B Payments to unmarried minor children of settlor.U.K.
F2007. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2007Ss. 660A, 660B repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 271, Sch. 3 (with Sch. 2)
660C Nature of charge on settlor.U.K.
(1)F2008. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F2009(1A)F2008. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(2)F2008. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F2010. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F2011(4)F2012. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2008S. 660C(1)-(2) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 272(2), Sch. 3 (with Sch. 2)
F2009S. 660C(1A) inserted (with effect in accordance with Sch. 4 para. 14(4) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 4 para. 14(3)
F2010S. 660C(3) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 144, Sch. 3 Pt. 1 (with Sch. 2)
F2011S. 660C(4) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 272(4) (with Sch. 2)
F2012S. 660C(4) repealed (with effect in accordance with Sch. 5 para. 2(2)(3) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 5 para. 2(1), Sch. 27 Pt. 2(3), Note
660D Adjustments between settlor and trustees, &c.U.K.
F2013. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2013Ss. 660D-660G repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 273, Sch. 3 (with Sch. 2)
Supplementary provisionsU.K.
660E Application to settlements by two or more settlors.U.K.
F2014. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2014Ss. 660D-660G repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 273, Sch. 3 (with Sch. 2)
660F Power to obtain information.U.K.
F2015. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2015Ss. 660D-660G repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 273, Sch. 3 (with Sch. 2)
660G Meaning of “settlement” and related expressions.U.K.
F2016. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2016Ss. 660D-660G repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 273, Sch. 3 (with Sch. 2)
CHAPTER IU.K. DISPOSITIONS FOR SHORT PERIODS
F2005660 Dispositions for period which cannot exceed six years.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005661 Adjustments between disponor and trustees.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005662 Application of Chapter I to dispositions by two or more disponors.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
CHAPTER IIU.K. SETTLEMENTS ON CHILDREN
F2005663 The general rule.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005664 Accumulation settlements.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005665 Meaning of “irrevocable”.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005666 Interest paid by trustees.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005667 Adjustments between disponor and trustees.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005668 Application of Chapter II to settlements by two or more settlors.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005669 Power to obtain information under Chapter II.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005670 Interpretation of Chapter II.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
[F2017CHAPTER 1BU.K. PROVISIONS AS TO CAPITAL SUMS PAID TO SETTLOR]
Textual Amendments
F2017Pt. 15 Ch. 1B heading inserted (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 8
F2005671 Revocable settlements allowing release of obligation.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005672 Revocable settlements allowing reversion of property.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005673 Settlements where settlor retains an interest.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005674 Settlements: discretionary power for benefit of settlor etc.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005674A[F2018 Other settlements where settlor retains interest in settled property.]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F20181989 s.109(1).
F2005675 Provisions supplementary to sections 671 to 674.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
F2005676 Disallowance of deduction from total income of certain sums paid by settlor.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2005Pt. 15 Ch. 1A inserted (in place of ss. 660-676, 683-685) (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 1
677 Sums paid to settlor otherwise than as income.U.K.
F2019. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2019S. 677 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 274, Sch. 3 (with Sch. 2)
678 Capital sums paid by body connected with settlement.U.K.
F2020. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2020S. 678 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 275, Sch. 3 (with Sch. 2)
679 Application of Chapter III to settlements by two or more settlors.U.K.
F2021. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2021Ss. 679-681 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
680 Power to obtain information for purposes of Chapter III.U.K.
F2022. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2022Ss. 679-681 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
681 Interpretation of Chapter III.U.K.
F2023. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2023Ss. 679-681 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
682 Ascertainment of undistributed income.U.K.
F2024. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2024Ss. 682, 682A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 276, Sch. 3 (with Sch. 2)
[F2025682A Supplementary provisions.U.K.
F2026. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2025S. 682A inserted (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 11
F2026Ss. 682, 682A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 276, Sch. 3 (with Sch. 2)
[F2027CHAPTER 1CU.K. LIABILITY OF TRUSTEES]
Textual Amendments
F2027Pt. 15 Ch. 1C heading substituted for heading before s. 686 (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 12
Modifications etc. (not altering text)
C58Pt. 15 Ch. 1C modified (6.4.2005 with effect in accordance with s. 883(1) of the modifying Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), s. 457(1)(3) (with Sch. 2)
F2028. . . U.K.
Textual Amendments
F2028Ss. 683-685 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
683 Settlements made after 6th April 1965.U.K.
F2029. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2029Ss. 683-685 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
684 Settlements made before 7th April 1965 but after 9th April 1946.U.K.
F2030. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2030Ss. 683-685 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
685 Provisions supplementary to sections 683 and 684.U.K.
F2031. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2031Ss. 683-685 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
F2032. . . U.K.
Textual Amendments
F2032Cross-heading before s. 686 replaced by Pt. 15 Ch. 1C heading (with effect in accordance with s. 74(2) of the amending Act) by Finance Act 1995 (c. 4), Sch. 17 para. 12
[F2033685AMeaning of “settled property”U.K.
F2034. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2034Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
685BMeaning of “settlor”U.K.
F2035. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2035Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
685CTransfer between settlements: identification of settlorU.K.
F2036. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2036Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
685DVariation of will or intestacy, etc: identification of settlorU.K.
F2037. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2037Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
685ETrustees of settlementsU.K.
F2038. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2038Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
685FApplication of section 739 and 740U.K.
F2039. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2039Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
685GSub-fundsU.K.
F2040. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2033Ss. 685A-685G inserted (coming into force and with effect in accordance with Sch. 13 para. 1(2)-(6) of the amending Act) by Finance Act 2006 (c. 25), Sch. 13 para. 1(1)
F2040Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
686[F2041Accumulation and discretionary trusts: special rates of tax.]U.K.
F2042. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2041S. 686 sidenote substituted (with effect in accordance with s. 32(11) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 32(8)
F2042Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
[F2043686A Receipts to be treated as income to which section 686 appliesU.K.
F2044. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2043S. 686A inserted (with effect in accordance with s. 32(11) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 32(9)
F2044Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2) (subject to an amendment to s. 686A(2)(a) by Finance Act 2007 (c. 11), s. 55(1)(3))
[F2045686BShare incentive plans: distributions in respect of unappropriated sharesU.K.
F2046. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2045Ss. 686B, 686C inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 100 (with Sch. 2 para. 87, Sch. 7)
F2046Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
686CInterpretation of section 686BU.K.
F2047. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2045Ss. 686B, 686C inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 100 (with Sch. 2 para. 87, Sch. 7)
F2047Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
[F2048686DSpecial trust rates not to apply to first slice of trust incomeU.K.
F2049. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2048S. 686D inserted (with effect in accordance with s. 14(5) of the amending Act) by Finance Act 2005 (c. 7), s. 14(1)
F2049Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
[F2050686EApplication of section 686D where settlor has made more than one settlementU.K.
F2051. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2050S. 686E inserted (6.4.2006) by Finance Act 2006 (c. 25), Sch. 13 para. 4(2)(3)
F2051Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
687 Payments under discretionary trusts.U.K.
F2052. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2052Ss. 685A-687 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
[F2053687A[F2054Discretionary payments by trustees to companies].U.K.
F2055. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2053S. 687A inserted (with effect in accordance with s. 27(2) of the amending Act) by Finance (No. 2) Act 1997 (c. 58), s. 27(1)
F2054Words in s. 687A sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 146(5) (with Sch. 2)
F2055S. 687A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 92, Sch. 3 Pt. 1 (with Sch. 2)
688 Schemes for employees and directors to acquire shares.U.K.
F2056. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2056S. 688 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 279, Sch. 3 (with Sch. 2)
689 Recovery from trustees of discretionary trusts of higher rate tax due from beneficiaries.U.K.
F2057. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2057S. 689 repealed (with effect in accordance with s. 74(2), Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 17 para. 15, Sch. 29 Pt. 8(8)
[F2058Chapter IDU.K. Trust management expenses
Textual Amendments
F2058Pt. 15 Ch. 1D (ss. 689A, 689B) inserted (with effect in accordance with Sch. 6 para. 28 of the amending Act) by Finance Act 1996 (c. 8), Sch. 6 para. 16
689A Disregard of expenses where beneficiary non-resident.U.K.
F2059. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2059S. 689A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 147, Sch. 3 Pt. 1 (with Sch. 2)
689B Order in which expenses to be set against income.U.K.
F2060. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2060S. 689B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 93, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER VU.K. MAINTENANCE FUNDS FOR HISTORIC BUILDINGS
690 Schedule 4 directions.U.K.
F2061. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2061Ss. 690-694 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 149, Sch. 3 Pt. 1 (with Sch. 2)
691 Certain income not to be income of settlor etc.U.K.
F2062. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2062Ss. 690-694 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 149, Sch. 3 Pt. 1 (with Sch. 2)
692 Reimbursement of settlor.U.K.
F2063. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2063Ss. 690-694 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 149, Sch. 3 Pt. 1 (with Sch. 2)
693 Severance of settled property for certain purposes.U.K.
F2064. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2064Ss. 690-694 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 149, Sch. 3 Pt. 1 (with Sch. 2)
694[F2065Trustees chargeable to income tax in certain cases at higher rate reduced by rate applicable to trusts]U.K.
F2066. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2065S. 694 sidenote substituted (22.7.2004) by Finance Act 2004 (c. 12), Sch. 4 para. 2
F2066Ss. 690-694 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 149, Sch. 3 Pt. 1 (with Sch. 2)
PART XVIU.K. ESTATES OF DECEASED PERSONS IN COURSE OF ADMINISTRATION
695 Limited interests in residue.U.K.
F2067. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2067S. 695 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 204, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
696 Absolute interests in residue.U.K.
F2068. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2068S. 696 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 205, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
697 Supplementary provisions as to absolute interests in residue.U.K.
F2069. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2069S. 697 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 206, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
698 Special provisions as to certain interests in residue.U.K.
F2070. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2070S. 698 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 207, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F2072698A Taxation of income of beneficiaries at lower rate or at rates applicable to [F2071distribution] income.U.K.
F2073. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2071Word in s. 698A sidenote substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 288(5) (with Sch. 2)
F2072S. 698A inserted (27.7.1993 with effect for the year 1993-1994 and subsequent years of assessment) by 1993 c. 34, s. 79, Sch. 6 paras. 11(2), 25(1)
F2073S. 698A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 150, Sch. 3 Pt. 1 (with Sch. 2)
699 Relief from higher rate tax for inheritance tax on accrued income.U.K.
F2074. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2074S. 699 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 289, Sch. 3 (with Sch. 2)
[F2075699A Untaxed sums comprised in the income of the estate.U.K.
F2076. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2075S. 699A inserted (with effect in accordance with s. 76(6) of the amending Act) by Finance Act 1995 (c. 4), s. 76(4)
F2076S. 699A repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 208, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
700 Adjustments and information.U.K.
F2077. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2077S. 700 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 45, Sch. 10 Pt. 12 (with Sch. 9)
701 Interpretation.U.K.
F2078. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2078S. 701 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 210, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
702 Application to Scotland.U.K.
F2079. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2079S. 702 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 211, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
PART XVIIU.K. TAX AVOIDANCE
[F2080CHAPTER IU.K.CANCELLATION OF [F2081CORPORATION TAX] ADVANTAGES FROM CERTAIN TRANSACTIONS IN SECURITIES]
Textual Amendments
F2080Pt. 17 Ch. 1 (ss. 703-709) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 94, Sch. 3 Pt. 1 (with Sch. 2)
F2081Words in Pt. 17 Ch. 1 heading substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 153 (with Sch. 2)
703 Cancellation of [F2082corporation tax] advantage.U.K.
F2083. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2082Words in s. 703 sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 154(10) (with Sch. 2)
F2083Pt. 17 Ch. 1 (ss. 703-709) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 94, Sch. 3 Pt. 1 (with Sch. 2)
704 The prescribed circumstances.U.K.
F2084. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2084Pt. 17 Ch. 1 (ss. 703-709) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 94, Sch. 3 Pt. 1 (with Sch. 2)
705 Appeals against Board’s notices under section 703.U.K.
F2085. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2085Pt. 17 Ch. 1 (ss. 703-709) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 94, Sch. 3 Pt. 1 (with Sch. 2)
[F2086705A Statement of case by tribunal for opinion of High Court.U.K.
F2087. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2086Ss. 705A, 705B inserted (1.1.1994) by The General and Special Commissioners (Amendment of Enactments) Regulations 1994 (S.I. 1994/1813), reg. 1(1), Sch. 1 para. 24
F2087Ss. 705A, 705B, 706 omitted (1.4.2009) by virtue of The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 152
705B Proceedings in Northern Ireland.U.K.
F2088. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2086Ss. 705A, 705B inserted (1.1.1994) by The General and Special Commissioners (Amendment of Enactments) Regulations 1994 (S.I. 1994/1813), reg. 1(1), Sch. 1 para. 24
F2088Ss. 705A, 705B, 706 omitted (1.4.2009) by virtue of The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 152
706 The tribunal.U.K.
F2089. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2089Ss. 705A, 705B, 706 omitted (1.4.2009) by virtue of The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 152
707 Procedure for clearance in advance.U.K.
F2090. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2090Pt. 17 Ch. 1 (ss. 703-709) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 94, Sch. 3 Pt. 1 (with Sch. 2)
708 Power to obtain information.U.K.
F2091. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2091S. 708 omitted (13.8.2009) by virtue of The Finance Act 2009, Schedule 47 (Consequential Amendments) Order 2009 (S.I. 2009/2035), art. 1, Sch. para. 19
709 Meaning of [F2092“corporation tax advantage”] and other expressions.U.K.
F2093. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2092Words in s. 709 sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 161(5) (with Sch. 2)
F2093Pt. 17 Ch. 1 (ss. 703-709) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 94, Sch. 3 Pt. 1 (with Sch. 2)
CHAPTER IIU.K. TRANSFERS OF SECURITIES
Transfers with or without accrued interest: introductoryU.K.
710 Meaning of “securities”, “transfer” etc. for purposes of sections 711 to 728.U.K.
F2094. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2094Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
711 Meaning of “interest”, “transfers with or without accrued interest” etc.U.K.
F2095. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2095Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
712 Meaning of “settlement day” for purposes of sections 711 to 728.U.K.
F2096. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2096Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
Transfers with or without accrued interest: charge to tax and reliefsU.K.
713 Deemed sums and reliefs.U.K.
F2097. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2097Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
714 Treatment of deemed sums and reliefs.U.K.
F2098. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2098Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
715 Exceptions from sections 713 and 714U.K.
F2099. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2099Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
716 Transfer of unrealised interest.U.K.
F2100. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2100Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
717 Variable interest rate.U.K.
F2101. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2101Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
718 Interest in default.U.K.
F2102. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2102Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
719 Unrealised interest in defaultU.K.
F2103. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2103Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
Transfers with or without accrued interest: supplementalU.K.
720 Nominees, trustees etc.U.K.
F2104. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2104Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
721 Death.U.K.
F2105. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2105Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
722 Trading stock.U.K.
F2106. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2106Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
[F2107722A Gilt strips: deemed transfer.U.K.
F2108. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2107S. 722A inserted (29.4.1996) by Finance Act 1996 (c. 8), Sch. 40 para. 6
F2108Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
723 Foreign securities: delayed remittancesU.K.
F2109. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2109Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
724 Insurance companies.U.K.
F2110. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2110S. 724 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(3), Note
F2111725. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F2111S. 725 repealed (27.7.1993 with effect for the year 1992-93 and subsequent years of assessment) by 1993 c. 34, s. 213, Sch. 23 Pt. III(12) Note 5
F2112726. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
Textual Amendments
F2112S. 726 repealed (for the year 1991-92 and subsequent years of assessment) by Finance Act 1991 (c. 31, SIF 63:1), s. 123, Sch. 19 Pt. V, Note 6
[F2113726A New issues of securities.U.K.
F2114. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2113S. 726A inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 54, Sch. 12 paras. 2, 5
F2114Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
727 Stock lending.U.K.
F2115. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2115Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
[F2116727A Exception for sale and repurchase of securities.U.K.
F2117. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2116S. 727A inserted (with effect in accordance with s. 79(3) of the amending Act) by Finance Act 1995 (c. 4), s. 79(1) (with s. 79(4))
F2117Ss. 710-727A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 162, Sch. 3 Pt. 1 (with Sch. 2)
728 Information.U.K.
F2118. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2118S. 728 omitted (13.8.2009) by virtue of The Finance Act 2009, Schedule 47 (Consequential Amendments) Order 2009 (S.I. 2009/2035), art. 1, Sch. para. 20
Other transfers of securitiesU.K.
729 Sale and repurchase of securities.U.K.
F2119. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2119S. 729 repealed (with effect in accordance with s. 159(1)(10) of the repealing Act) by Finance Act 1996 (c. 8), s. 159(1), Sch. 41 Pt. 5(21), Note; S.I. 1996/2646, art. 2
730[F2120Transfers of rights to receive distributions in respect of shares]U.K.
F2121. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2120S. 730 heading substituted (with effect in accordance with Sch. 7 para. 2(13) of the amending Act) by virtue of Finance (No. 2) Act 2005 (c. 22), Sch. 7 para. 2(12)
F2121S. 730 omitted (with effect in accordance with Sch. 25 para. 10 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 25 para. 9(1)(a)
[F2122730A Treatment of price differential on sale and repurchase of securities.U.K.
F2123. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2122Ss. 730A, 730B inserted (with effect in accordance with s. 80(5) of the amending Act) by Finance Act 1995 (c. 4), s. 80(1)
F2123Ss. 730A, 730B repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 4, Sch. 27 Pt. 2(14), Note
730B Interpretation of section 730A.U.K.
F2124. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2122Ss. 730A, 730B inserted (with effect in accordance with s. 80(5) of the amending Act) by Finance Act 1995 (c. 4), s. 80(1)
F2124Ss. 730A, 730B repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 4, Sch. 27 Pt. 2(14), Note
[F2125730BBExchange gains and losses on sale and repurchase of securitiesU.K.
F2126. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2125S. 730BB inserted (with effect in accordance with Sch. 38 para. 21(2) of the amending Act) by Finance Act 2003 (c. 14), Sch. 38 para. 12
F2126S. 730BB repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 5, Sch. 27 Pt. 2(14), Note
[F2127730C Exchanges of gilts: traders etc.U.K.
F2128. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2127S. 730C inserted (29.4.1996) by Finance Act 1996 (c. 8), Sch. 40 para. 7
F2128S. 730C repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 301, Sch. 3 (with Sch. 2)
Purchase and sale of securitiesU.K.
731 Application and interpretation of sections 732 to 734.U.K.
F2129. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2129Ss. 731-735 omitted (with effect in accordance with s. 66(6) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(1)(c) (subject to modification to s. 731 by Corporation Tax Act 2009 (c. 4), Sch. 2 para. 144)
732 Dealers in securities.U.K.
F2130. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2130Ss. 731-735 omitted (with effect in accordance with s. 66(6) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(1)(c)
733 Persons entitled to exemptions.U.K.
F2131. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2131Ss. 731-735 omitted (with effect in accordance with s. 66(6) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(1)(c)
734 Persons other than dealers in securities.U.K.
F2132. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2132Ss. 731-735 omitted (with effect in accordance with s. 66(6) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(1)(c)
735 Meaning of “appropriate amount in respect of” interest.U.K.
F2133. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2133Ss. 731-735 omitted (with effect in accordance with s. 66(6) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(1)(c)
Miscellaneous provisions relating to securitiesU.K.
736 Company dealing in securities: distribution materially reducing value of holding.U.K.
F2134. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2134S. 736 omitted (with effect in accordance with s. 66(7) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(1)(d)
[F2135736A Manufactured dividends and interest.U.K.
F2136. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2135S. 736A inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 58(1) (with effect as mentioned in s. 58(3) in relation to payments made on or after such day as may be specified: 26.2.1992 specified for certain purposes by S.I. 1992/173, reg. 2(a); 30.6.1992 specified for certain purposes by S.I. 1992/1346, regs.2, 3, 4; 21.4.1993 specified for certain purposes by S.I. 1993/933, regs.2, 3(a), 4(1))
F2136S. 736A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 95, Sch. 3 Pt. 1 (with Sch. 2)
[F2137736B Deemed manufactured payments in the case of stock lending arrangements.U.K.
F2138. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2137S. 736B inserted (with effect in accordance with Sch. 10 para. 7(1) of the amending Act) by Finance Act 1997 (c. 16), Sch. 10 para. 3; S.I. 1997/991, art. 2
F2138S. 736B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 96, Sch. 3 Pt. 1 (with Sch. 2)
[F2139736CDeemed interest: cash collateral under stock lending arrangementsU.K.
F2140. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2139S. 736C inserted (with effect in accordance with Sch. 6 para. 3(2)-(4) of the amending Act) by Finance Act 2006 (c. 25), Sch. 6 para. 3(1)
F2140S. 736C omitted (22.4.2009) by virtue of Finance Act 2009 (c. 10), Sch. 24 paras. 8(a)(i), 12 (with Sch. 24 paras. 13-16)
[F2141736DQuasi-stock lending arrangements and quasi-cash collateralU.K.
F2142. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2141S. 736D inserted (with effect in accordance with Sch. 6 para. 4(4) of the amending Act) by Finance Act 2006 (c. 25), Sch. 6 para. 4(3)
F2142S. 736D omitted (22.4.2009) by virtue of Finance Act 2009 (c. 10), Sch. 24 paras. 8(a)(ii), 12 (with Sch. 24 paras. 13-16)
737 Manufactured dividends: treatment of tax deducted.U.K.
F2143. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2143S. 737 repealed (with effect in accordance with Sch. 10 para. 16(1), Sch. 18 Pt. 6(10) Notes 3, 6 of the repealing Act) by Finance Act 1997 (c. 16), Sch. 10 para. 8, Sch. 18 Pt. 6(10) (with Sch. 10 para. 16(3)); S.I. 1997/991, art. 2
[F2144737A Sale and repurchase of securities: deemed manufactured payments.U.K.
F2145. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2144Ss. 737A-737C inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 122
F2145Ss. 737A-737C repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 7, Sch. 27 Pt. 2(14), Note
737B Interpretation of section 737A.U.K.
F2146. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2144Ss. 737A-737C inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 122
F2146Ss. 737A-737C repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 7, Sch. 27 Pt. 2(14), Note
737C Deemed manufactured payments: further provisions.U.K.
F2147. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2144Ss. 737A-737C inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 122
F2147Ss. 737A-737C repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 7, Sch. 27 Pt. 2(14), Note
SupplementalU.K.
[F2148737D Power to provide for manufactured payments to be eligible for relief.U.K.
F2149. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2148Ss. 737D, 737E inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 83(1)
F2149S. 737D omitted (21.7.2008) by virtue of Finance Act 2008 (c. 9), Sch. 17 para. 35(1)
737E[F2150Power to modify sections F2151. . . 730A, 730BB and 737A to 737C]U.K.
F2152. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2148Ss. 737D, 737E inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 83(1)
F2150S. 737E sidenote substituted (with effect in accordance with Sch. 38 para. 21(2) of the amending Act) by virtue of Finance Act 2003 (c. 14), Sch. 38 para. 13(4)
F2151Words in s. 737E sidenote repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 176(4), Sch. 3 Pt. 1 (with Sch. 2)
F2152S. 737E repealed (with effect in accordance with S.I. 2007/2483, art. 3) by Finance Act 2007 (c. 11), s. 47(4), Sch. 14 para. 8, Sch. 27 Pt. 2(14), Note
738 Power to amend sections 732, 735 and 737.U.K.
F2153. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2153S. 738 omitted (with effect in accordance with s. 66(6)-(8) of the repealing Act) by virtue of Finance Act 2008 (c. 9), s. 66(4)(a)
CHAPTER IIIU.K. TRANSFER OF ASSETS ABROAD
739 Prevention of avoidance of income tax.U.K.
F2154. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2154Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
740 Liability of non-transferors.U.K.
F2155. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2155Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
741[F2156Exemption from sections 739 and 740 (transactions before 5th December 2005)]U.K.
F2157. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2156S. 741 sidenote substituted (5.12.2005) by virtue of Finance Act 2006 (c. 25), Sch. 7 para. 2(4)(5)
F2157Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
[F2158741AExemption from sections 739 and 740 (transactions on or after 5th December 2005)U.K.
F2159. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2158S. 741A inserted (5.12.2005) by Finance Act 2006 (c. 25), Sch. 7 para. 3
F2159Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
[F2160741BApplication of sections 741 and 741AU.K.
F2161. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2160Ss. 741B, 741C inserted (5.12.2005) by Finance Act 2006 (c. 25), Sch. 7 para. 4
F2161Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
741CCases where there are both old transactions and new transactionsU.K.
F2162. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2160Ss. 741B, 741C inserted (5.12.2005) by Finance Act 2006 (c. 25), Sch. 7 para. 4
F2162Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
[F2163741DSection 739: just and reasonable apportionment in certain casesU.K.
F2164. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2163S. 741D inserted (5.12.2005) by Finance Act 2006 (c. 25), Sch. 7 para. 5
F2164Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
742[F2165Interpretation of this Chapter]U.K.
F2166. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2165S. 742 sidenote substituted (5.12.2005) by virtue of Finance Act 2006 (c. 25), Sch. 7 para. 6(5)(6)
F2166Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
743 Supplemental provisions.U.K.
F2167. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2167Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
744 No duplication of charge.U.K.
F2168. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2168Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
745 Power to obtain information.U.K.
F2169. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2169Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
746 Persons resident in the Republic of Ireland.U.K.
F2170. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2170Ss. 739-746 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 177, Sch. 3 Pt. 1 (with Sch. 2)
[F2171CHAPTER IVU.K. CONTROLLED FOREIGN COMPANIES]
Textual Amendments
F2171Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
747 Imputation of chargeable profits and creditable tax of controlled foreign companiesU.K.
F2172. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2172Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2173747A Special rule for computing chargeable profits.U.K.
F2174. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2173S. 747A inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 25 para. 2
F2174S. 747A repealed (with effect in accordance with Sch. 4 para. 24(2) of the repealing Act) by Finance Act 2005 (c. 7), Sch. 4 para. 24(1), Sch. 11 Pt. 2(6), Note
748[F2175Cases where section 747(3) does not apply.]U.K.
F2176. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2175S. 748 sidenote substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 3(9); S.I. 1998/3173, art. 2
F2176Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2177748ZAExclusion of small profits exemptionsU.K.
F2178. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2177S. 748ZA inserted (with effect in accordance with Sch. 12 para. 14(2) of the amending Act) by Finance Act 2011 (c. 11), Sch. 12 para. 5
F2178Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2179748ATerritorial exclusions from exemption under section 748U.K.
F2180. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2179S. 748A inserted (with effect in accordance with s. 89(3) of the amending Act) by Finance Act 2002 (c. 23), s. 89(2)
F2180Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2181749 Residence.U.K.
F2182. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2181Ss. 749-749B substituted for s. 749 (with effect in accordance with Sch.17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 4; S.I. 1998/3173, art. 2
F2182Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2183749A Elections and designations under section 749: supplementary provisions.U.K.
F2184. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2183Ss. 749-749B substituted for s. 749 (with effect in accordance with Sch.17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 4; S.I. 1998/3173, art. 2
F2184Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
749B Interests in companies.U.K.
F2185. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2183Ss. 749-749B substituted for s. 749 (with effect in accordance with Sch.17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 4; S.I. 1998/3173, art. 2
F2185Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
750 Territories with a lower level of taxation.U.K.
F2186. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2186Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2187750A Deemed lower level of taxation: designer rate tax provisions.U.K.
F2188. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2187S. 750A inserted (with effect in accordance with Sch. 31 para. 9(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 3
F2188Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
751 Accounting periods and creditable taxU.K.
F2189. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2189Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2190751AReduction in chargeable profits for certain activities of EEA business establishmentsU.K.
F2191. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2190Ss. 751A, 751B inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 5
F2191Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2192751AAReduction in chargeable profits for certain financing incomeU.K.
F2193. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2190Ss. 751A, 751B inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 5
F2192S. 751AA inserted (with effect in accordance with Sch. 16 para. 25 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 23
F2193Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2194751ABReduction in chargeable profits: failure to qualify for exemptionsU.K.
F2195. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2190Ss. 751A, 751B inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 5
F2194S. 751AB inserted (with effect in accordance with Sch. 12 para. 14(2) of the amending Act) by Finance Act 2011 (c. 11), Sch. 12 para. 2
F2195Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2196751ACReduction in chargeable profits following an exempt periodU.K.
F2197. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2190Ss. 751A, 751B inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 5
F2196S. 751AC inserted (with effect in accordance with Sch. 12 para. 14(2) of the amending Act) by Finance Act 2011 (c. 11), Sch. 12 para. 7
F2197Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
751B[F2198Sections 751A [F2199to 751AC]]: supplementaryU.K.
F2200. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2190Ss. 751A, 751B inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 5
F2198Words in s. 751B heading substituted (with effect in accordance with Sch. 16 para. 25 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 24(2)
F2199Words in s. 751B heading substituted (with effect in accordance with Sch. 12 para. 14(2) of the amending Act) by Finance Act 2011 (c. 11), Sch. 12 para. 12(6)
F2200Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2201752 Apportionment of chargeable profits and creditable taxU.K.
F2202. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2201Ss. 752-752C substituted for s. 752 (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 7; S.I. 1998/3173, art. 2
F2202Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2203752A Relevant interests.U.K.
F2204. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2203Ss. 752-752C substituted for s. 752 (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 7; S.I. 1998/3173, art. 2
F2204Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
752B Section 752(3): the percentage of shares which a relevant interest represents.U.K.
F2205. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2203Ss. 752-752C substituted for s. 752 (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 7; S.I. 1998/3173, art. 2
F2205Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
752C Interpretation of apportionment provisions.U.K.
F2206. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2203Ss. 752-752C substituted for s. 752 (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 7; S.I. 1998/3173, art. 2
F2206Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
753 Notices and appeals.U.K.
F2207. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2207S. 753 repealed (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 8, Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
754 Assessment, recovery and postponement of tax.U.K.
F2208. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2208Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2209754A Returns where it is not established whether acceptable distribution policy applies.U.K.
F2210. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2209S. 754A inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 10; S.I. 1998/3173, art. 2
F2210S. 754A omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(2) (with Sch. 16 paras. 7, 8)
[F2211754B Determinations requiring the sanction of the Board.U.K.
F2212. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2211S. 754B inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 11; S.I. 1998/3173, art. 2
F2212Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
755 Information relating to controlled foreign companiesU.K.
F2213. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2213S. 755 repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 12, Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
[F2214755A Treatment of chargeable profits and creditable tax apportioned to company carrying on life assurance business.U.K.
F2215. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2214S. 755A inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 13; S.I. 1998/3173, art. 2
F2215Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2216755B Amendment of return where general insurance business of foreign company accounted for on non-annual basis.U.K.
F2217. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2216S. 755B inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 14; S.I. 1998/3173, art. 2
F2217Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2218755C Application of Chapter where general insurance business of foreign company accounted for on non-annual basis.U.K.
F2219. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2218S. 755C inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 15; S.I. 1998/3173, art. 2
F2219Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2220755D“Control" and the two “40 per cent" tests.U.K.
F2221. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2220S. 755D inserted (with effect in accordance with Sch. 31 para. 9(3) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 4(1)
F2221Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
756 Interpretation and construction of Chapter IV.U.K.
F2222. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2222Pt. 17 Ch. 4 (ss. 747-756) omitted (with effect in accordance with Sch. 20 paras. 49, 50 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 20 para. 14
[F2223CHAPTER VU.K. OFFSHORE FUNDS]
Textual Amendments
F2223Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
[F2224Meaning of offshore fundU.K.
Textual Amendments
F2224Ss. 756A-756C and preceding cross-headings inserted (with effect in accordance with s. 145(2) of the amending Act) by Finance Act 2004 (c. 12), Sch. 26 para. 3 (with Sch. 26 para. 17)
756AGeneral definition of offshore fundU.K.
F2225. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2225Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
Treatment of umbrella fundsU.K.
756BTreatment of umbrella fundsU.K.
F2226. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2226Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
Treatment of funds comprising more than one class of interestU.K.
756CTreatment of funds comprising more than one class of interestU.K.
F2227. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2227Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
Material interests in non-qualifying offshore fundsU.K.
757 Disposal of material interests in non-qualifying offshore fundsU.K.
F2228. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2228Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
758 Offshore funds operating equalisation arrangementsU.K.
F2229. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2229Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
759 Material interests in offshore fundsU.K.
F2230. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2230Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
760 Non-qualifying offshore fundsU.K.
F2231. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2231Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
Charge to tax of offshore income gainsU.K.
761 Charge to income tax or corporation tax of offshore income gain.U.K.
F2232. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2232Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
762 Offshore income gains accruing to persons resident or domiciled abroad.U.K.
F2233. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2233Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
[F2234762ZAOffshore income gains: application of transfer of assets abroad provisionsU.K.
F2235. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2234Ss. 762ZA, 762ZB inserted (with effect in accordance with Sch. 7 para. 98 of the amending Act) by Finance Act 2008 (c. 9), Sch. 7 para. 94
F2235Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
762ZBIncome treated as arising under section 761(1): remittance basisU.K.
F2236. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2234Ss. 762ZA, 762ZB inserted (with effect in accordance with Sch. 7 para. 98 of the amending Act) by Finance Act 2008 (c. 9), Sch. 7 para. 94
F2236Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
[F2237762AExchange of interests of different classesU.K.
F2238. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2237S. 762A inserted (with effect in accordance with s. 145(2) of the amending Act) by Finance Act 2004 (c. 12), Sch. 26 para. 15(1) (with Sch. 26 para. 17)
F2238Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
763 Deduction of offshore income gain in determining capital gain.U.K.
F2239. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2239Pt. 17 Ch. 5 (ss. 756A-763) repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with Sch. 1)
764 Offshore income gains of trustees.U.K.
F2240. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2240S. 764 repealed (6.4.2006) by Finance Act 2006 (c. 25), Sch. 13 paras. 23, 27(1), Sch. 26 Pt. 3(15), Note
CHAPTER VIU.K. MISCELLANEOUS
Migration etc. of companyU.K.
765 Migration etc. of companies.U.K.
F2241. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2241S. 765 omitted (with effect in accordance with Sch. 17 para. 13 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 17 para. 1(a)
[F2242765A Movements of capital between residents of member States.U.K.
F2243. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2242S. 765A inserted (with effect in accordance with s. 68(4) of the amending Act) by Finance Act 1990 (c. 29), s. 68(2)
F2243S. 765A omitted (with effect in accordance with Sch. 17 para. 13 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 17 para. 1(b)
766 Offences under section 765.U.K.
F2244. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2244S. 766 omitted (with effect in accordance with Sch. 17 para. 13 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 17 para. 1(c)
767 Interpretation and commencement of sections 765 and 766.U.K.
F2245. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2245S. 767 omitted (with effect in accordance with Sch. 17 para. 13 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 17 para. 1(d)
Change in ownership of companyU.K.
[F2246767A Change in company ownership: corporation tax.U.K.
F2247. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2246Ss. 767A, 767B inserted (with effect in accordance with s. 135(6) of the amending Act) by Finance Act 1994 (c. 9), s. 135(1)
F2247Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
[F2248767AA Change in company ownership: postponed corporation tax.U.K.
F2249. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2246Ss. 767A, 767B inserted (with effect in accordance with s. 135(6) of the amending Act) by Finance Act 1994 (c. 9), s. 135(1)
F2248S. 767AA inserted (with effect in accordance with s. 114(2) of the amending Act) by Finance Act 1998 (c. 36), s. 114(1)
F2249Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
767B Change of company ownership: supplementary.U.K.
F2250. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2246Ss. 767A, 767B inserted (with effect in accordance with s. 135(6) of the amending Act) by Finance Act 1994 (c. 9), s. 135(1)
F2250Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
[F2251767C Change in company ownership: information.U.K.
F2252. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2251S. 767C inserted (with effect in accordance with s. 115(3) of the amending Act) by Finance Act 1998 (c. 36), s. 115(1)
F2252S. 767C omitted (1.4.2009) by virtue of Finance Act 2008 (c. 9), s. 113(2), Sch. 36 para. 81 (with Sch. 36 para. 38); S.I. 2009/404, art. 2 (with art. 6)
768 Change in ownership of company: disallowance of trading losses.U.K.
F2253. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2253Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2) (subject to the omission of s. 768(9), so far as it continues to have effect, by virtue of Finance Act 2011 (c. 11), Sch. 23 paras. 55(d), 65)
[F2254768A Change in ownership: disallowance of carry back of trading losses.U.K.
F2255. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2255Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
[F2256768B[F2257Change in ownership of company with investment business: deductions generally]U.K.
F2258. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2256Ss. 768B, 768C inserted (with application in accordance with Sch. 26 para. 5 of the amending Act) by Finance Act 1995 (c. 4), Sch. 26 para. 2
F2257S. 768B sidenote substituted (with effect in accordance with ss. 42-44 of the amending Act) by virtue of Finance Act 2004 (c. 12), Sch. 6 para. 3(7)
F2258Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
768C Deductions: asset transferred within group.U.K.
F2259. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2256Ss. 768B, 768C inserted (with application in accordance with Sch. 26 para. 5 of the amending Act) by Finance Act 1995 (c. 4), Sch. 26 para. 2
F2259Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
[F2260768D Change in ownership of company carrying on property business.U.K.
F2261. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2260S. 768D inserted (with effect in accordance with s. 38(2)(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 5 para. 31 (with Sch. 5 para. 73)
F2261Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
[F2262768E Change in ownership of company with unused non-trading loss on intangible fixed assetsU.K.
F2263. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2262S. 768E inserted (24.7.2002) by Finance Act 2002 (c. 23), Sch. 30 para. 4(3)
F2263Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
769 Rules for ascertaining change in ownership of company.U.K.
F2264. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2264Ss. 767A-769 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 102, Sch. 3 Pt. 1 (with Sch. 2)
Transactions between associated personsU.K.
[F2265770A Provision not at arm’s length.U.K.
F2266. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2265S. 770A substituted for ss. 770-773 (with effect in accordance with s. 108(5) of the amending Act) by Finance Act 1998 (c. 36), s. 108(1); S.I. 1998/3173, art. 2
F2266S. 770A repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 110, Sch. 10 Pt. 2 (with Sch. 9)
F2265770 Sales etc. at an undervalue or overvalue.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2265S. 770A substituted for ss. 770-773 (with effect in accordance with s. 108(5) of the amending Act) by Finance Act 1998 (c. 36), s. 108(1); S.I. 1998/3173, art. 2
F2265771Transactions by petroleum companies.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2265S. 770A substituted for ss. 770-773 (with effect in accordance with s. 108(5) of the amending Act) by Finance Act 1998 (c. 36), s. 108(1); S.I. 1998/3173, art. 2
F2265772 Information for purposes of section 770, and appeals.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2265S. 770A substituted for ss. 770-773 (with effect in accordance with s. 108(5) of the amending Act) by Finance Act 1998 (c. 36), s. 108(1); S.I. 1998/3173, art. 2
F2265773 Interpretation of sections 770 and 771.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2265S. 770A substituted for ss. 770-773 (with effect in accordance with s. 108(5) of the amending Act) by Finance Act 1998 (c. 36), s. 108(1); S.I. 1998/3173, art. 2
774 Transactions between dealing company and associated company.U.K.
F2267. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2267S. 774 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
[F2268Factoring of income receipts etcU.K.
Textual Amendments
F2268Ss. 774A-774G and preceding cross-heading inserted (with effect in accordance with Sch. 6 para. 6(2)-(7) of the amending Act) by Finance Act 2006 (c. 25), Sch. 6 para. 6(1)
774AMeaning of “structured finance arrangement” for purposes of s.774BU.K.
F2269. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2269Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
774BDisregard of intended effects of arrangement involving disposals of assetsU.K.
F2270. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2270Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
774CMeaning of “structured finance arrangement” for purposes of s.774DU.K.
F2271. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2271Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
774DDisregard of intended effects of arrangement involving change in relation to a partnershipU.K.
F2272. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2272Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
774ESections 774B and 774D: exceptionsU.K.
F2273. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2273Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
774FSections 774B and 774D: power to provide further exceptionsU.K.
F2274. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2274Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
774GSections 774A to 774D: minor definitions etcU.K.
F2275. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2275Ss. 774A-774G repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 104, Sch. 3 Pt. 2 (with Sch. 2); and ss. 774A-774G repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 265, Sch. 10 Pt. 10 (with Sch. 9)
Other provisionsU.K.
775 Sale by individual of income derived from his personal activities.U.K.
F2276. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2276S. 775 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 182, Sch. 3 Pt. 1 (with Sch. 2)
[F2277775ATransfers of rights to receive annual paymentsU.K.
F2278. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2277S. 775A inserted (with effect in accordance with Sch. 7 para. 4(2) of the amending Act) by Finance (No. 2) Act 2005 (c. 22), Sch. 7 para. 4(1)
F2278S. 775A omitted (with effect in accordance with Sch. 25 para. 10 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 25 para. 9(1)(b)
776 Transactions in land: taxation of capital gains.U.K.
F2279. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2279Ss. 776-778 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 105, Sch. 3 Pt. 1 (with Sch. 2)
777 Provisions supplementary to [F2280section 776].U.K.
F2281. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2280Words in s. 777 sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 185(13) (with Sch. 2)
F2281Ss. 776-778 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 105, Sch. 3 Pt. 1 (with Sch. 2)
778 Power to obtain information.U.K.
F2282. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2282Ss. 776-778 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 105, Sch. 3 Pt. 1 (with Sch. 2)
779 Sale and leaseback: limitation on tax reliefs.U.K.
F2283. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2283Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
780 Sale and leaseback: taxation of consideration received.U.K.
F2284. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2284Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
781 Assets leased to traders and others.U.K.
F2285. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2285Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
782 Leased assets: special cases.U.K.
F2286. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2286Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
783 Leased assets: supplemental.U.K.
F2287. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2287Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
784 Leased assets subject to hire-purchase agreements.U.K.
F2288. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2288Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
785 Meaning of “asset”, “capital sum” and “lease” for purposes of sections 781 to 784.U.K.
F2289. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2289Ss. 779-785 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 106, Sch. 3 Pt. 2 (with Sch. 2); and ss. 779-785 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 242, Sch. 10 Pt. 9 (with Sch. 9)
[F2290785ZARestrictions on use of losses: leasing partnershipsU.K.
F2291. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2290Ss. 785ZA, 785ZB inserted (with effect in accordance with s. 83(4)-(6) of the amending Act) by Finance Act 2006 (c. 25), s. 83(2)
F2291S. 785ZA repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 107, Sch. 3 Pt. 1 (with Sch. 2)
785ZBSection 785ZA: definitionsU.K.
F2292. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2290Ss. 785ZA, 785ZB inserted (with effect in accordance with s. 83(4)-(6) of the amending Act) by Finance Act 2006 (c. 25), s. 83(2)
F2292S. 785ZB repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 108, Sch. 3 Pt. 1 (with Sch. 2)
[F2293785ARent factoring of leases of plant or machineryU.K.
F2294. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2293S. 785A inserted (with effect in accordance with s. 135(2) of the amending Act) by Finance Act 2004 (c. 12), s. 135(1)
F2294S. 785A omitted (with effect in accordance with Sch. 25 para. 10 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 25 para. 9(1)(c)
[F2295785BPlant and machinery leases: capital receipts to be treated as incomeU.K.
F2296. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2295Ss. 785B-785E inserted (with effect in accordance with Sch. 20 para. 1(2) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 1(1) (with transitional modifications in Sch. 20 para. 1(3))
F2296S. 785B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 109, Sch. 3 Pt. 1 (with Sch. 2)
785CSection 785B: interpretationU.K.
F2297. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2295Ss. 785B-785E inserted (with effect in accordance with Sch. 20 para. 1(2) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 1(1) (with transitional modifications in Sch. 20 para. 1(3))
F2297S. 785C repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 110, Sch. 3 Pt. 1 (with Sch. 2)
785DSection 785B: lease of plant and machinery and other propertyU.K.
F2298. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2295Ss. 785B-785E inserted (with effect in accordance with Sch. 20 para. 1(2) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 1(1) (with transitional modifications in Sch. 20 para. 1(3))
F2298S. 785D repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 111, Sch. 3 Pt. 1 (with Sch. 2)
785ESection 785B: expectation that relevant capital payment will not be paidU.K.
F2299. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2295Ss. 785B-785E inserted (with effect in accordance with Sch. 20 para. 1(2) of the amending Act) by Finance Act 2008 (c. 9), Sch. 20 para. 1(1) (with transitional modifications in Sch. 20 para. 1(3))
F2299S. 785E repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 112, Sch. 3 Pt. 1 (with Sch. 2)
786 Transactions associated with loans or credit.U.K.
F2300. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2300S. 786 repealed for specified purposes (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 113, Sch. 3 Pt. 2 (with Sch. 2); and s. 786 repealed for remaining purposes (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 266, Sch. 10 Pt. 10 (with Sch. 9)
787 Restriction of relief for payments of interest.U.K.
F2301. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2301S. 787 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 7 para. 49, Sch. 10 Pt. 12 (with Sch. 9)
PART XVIIIU.K. DOUBLE TAXATION RELIEF
Modifications etc. (not altering text)
C59Pt. 18 modified (3.5.1994) by Finance Act 1994 (c. 9), Sch. 20 para. 10 (as amended by Finance Act 1995 (c. 4), s. 122(4)(5)) (with Sch. 20 para. 12(2)(a))
C60Pt. 18 applied (with effect in accordance with Sch. 29 Pt. 14 of the affecting Act) by Finance Act 2002 (c. 23), Sch. 29 para. 87
C61Pt. 18 modified (22.7.2004) by Finance Act 2004 (c. 12), s. 107(5)
C62Pt. 18 applied by Finance Act 1996 (c. 8), Sch. 9 para. 12E(5) (as inserted (29.11.2007 with effect in accordance with regs. 1(2), 3(1) of the amending S.I. (as amended by S.I. 2008/1579, reg. 4(1))) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 1 para. 16)
C63Pt. 18 applied by Finance Act 2002 (c. 23), Sch. 26 para. 30E(5) (as inserted (29.11.2007 with effect in accordance with regs. 1(2), 3(1) of the amending S.I. (as amended by S.I. 2008/1579, reg. 4(1))) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 1 para. 19)
C64Pt. 18 applied by Finance Act 1996 (c. 8), Sch. 9 para. 12C(3) (as substituted (29.11.2007 with effect in accordance with regs. 1(2), 3(2) of the amending S.I.) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 2 para. 8)
C65Pt. 18 applied by Finance Act 2002 (c. 23), Sch. 26 para. 30C(3) (as substituted (29.11.2007 with effect in accordance with regs. 1(2), 3(2) of the amending S.I.) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 2 para. 10)
C66Pt. 18 applied by Finance Act 2002 (c. 23), Sch. 29 para. 87A(3) (as substituted (29.11.2007 with effect in accordance with regs. 1(2), 3(2) of the amending S.I.) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 2 para. 12)
C67Pt. 18 applied by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 140H(3), 140I(3), 140J(3) (as inserted (29.11.2007 with effect in accordance with regs. 1(2), 3(3) of the amending S.I. (as amended by S.I. 2008/1579, reg. 4(2))) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 3 para. 1)
C68Pt. 18 applied by Finance Act 1996 (c. 8), Sch. 9 paras. 12H(3), 12I(3) (as inserted (29.11.2007 with effect in accordance with regs. 1(2), 3(3) of the amending S.I. (as amended by S.I. 2008/1579, reg. 4(2))) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 3 para. 2)
C69Pt. 18 applied by Finance Act 2002 (c. 23), Sch. 26 paras. 30G(3), 30H(3) (as inserted (29.11.2007 with effect in accordance with regs. 1(2), 3(3) of the amending S.I. (as amended by S.I. 2008/1579, reg. 4(2))) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 3 para. 4)
C70Pt. 18 applied by Finance Act 2002 (c. 23), Sch. 29 paras. 85B(3), 85C(3) (as inserted (29.11.2007 with effect in accordance with regs. 1(2), 3(3) of the amending S.I. (as amended by S.I. 2008/1579, reg. 4(2))) by The Corporation Tax (Implementation of the Mergers Directive) Regulations 2007 (S.I. 2007/3186), Sch. 3 para. 5)
C71Pt. 18: power to amend conferred (1.4.2009 with effect in accordance with s. 1329(1) of the affecting Act) by Corporation Tax Act 2009 (c. 4), s. 533(2)(3) (with Sch. 2 Pts. 1, 2)
C72Pt. 18 modified (with effect in accordance with s. 56(3) of the modifying Act) by Finance Act 2009 (c. 10), s. 56(1)
F2302CHAPTER IU.K. THE PRINCIPAL RELIEFS
Textual Amendments
F2302Pt. 18 Chs. 1, 2 modified (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 277(1), 289 (with ss. 60, 101(1), 171, 201(3))
788 Relief by agreement with other [F2303territories].U.K.
F2304. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2303Word in s. 788 sidenote substituted (with effect in accordance with s. 88(3) of the amending Act) by Finance Act 2002 (c. 23), s. 88(2)(b)
F2304S. 788 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 13, Sch. 10 Pt. 1 (with Sch. 9)
789 Arrangements made under old law.U.K.
F2305. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2305S. 789 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 14, Sch. 10 Pt. 1 (with Sch. 9)
790 Unilateral relief.U.K.
F2306. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2306S. 790 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 15, Sch. 10 Pt. 1 (with Sch. 9)
791 Power to make regulations for carrying out section 788.U.K.
F2307. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2307S. 791 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 16, Sch. 10 Pt. 1 (with Sch. 9)
CHAPTER IIU.K. RULES GOVERNING RELIEF BY WAY OF CREDIT
Modifications etc. (not altering text)
C73Pt. 18 Chs. 1, 2 modified (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 277(1), 289 (with ss. 60, 101(1), 171, 201(3))
GeneralU.K.
792 Interpretation of credit code.U.K.
F2308. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2308Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
793 Reduction of United Kingdom taxes by amount of credit due.U.K.
F2309. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2309Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2310793A No double relief etc.U.K.
F2311. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2310S. 793A inserted (with effect in accordance with Sch. 30 para. 5(2)(3) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 5(1)
F2311Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
794 Requirement as to residence.U.K.
F2312. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2312Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
795 Computation of income subject to foreign tax.U.K.
F2313. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2313Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2314795A Limits on credit: minimisation of the foreign tax.U.K.
F2315. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2314S. 795A inserted (with effect in accordance with Sch. 30 para. 6(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 6(1)
F2315Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
796 Limits on credit: income tax.U.K.
F2316. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2316Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
797 Limits on credit: corporation tax.U.K.
F2317. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2317Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2318797A Foreign tax on [F2319items giving rise to] a non-trading credit [F2320: loan relationships].U.K.
F2321. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2318S. 797A inserted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 43 (with Sch. 15)
F2319Word in s. 797A sidenote substituted (with effect in accordance with Sch. 30 para. 7(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 7(3)
F2320Words in s. 797A sidenote added (24.7.2002) by Finance Act 2002 (c. 23), Sch. 30 para. 5(3)
F2321Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2322797B Foreign tax on items giving rise to a non-trading credit: intangible fixed assetsU.K.
F2323. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2322S. 797B inserted (24.7.2002) by Finance Act 2002 (c. 23), Sch. 30 para. 5(4)
F2323Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
798Section 796: trade incomeU.K.
F2324. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2324Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2325798A Section 797: trade incomeU.K.
F2326. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2325S. 798A inserted (with effect in accordance with s. 103(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 104
F2326Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2327798B Section 798A: special casesU.K.
F2328. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2327S. 798B inserted (with effect in accordance with s. 103(2)(3) of the amending Act) by Finance Act 1998 (c. 36), s. 105
F2328Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
[F2329798CDisallowed credit: use as deductionU.K.
F2330. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2329Ss. 798-798C substituted for ss. 798-798B (with effect in accordance with s. 86(3)-(5) of the amending Act) by Finance Act 2005 (c. 7), s. 86(1)
F2330Ss. 792-798C repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 17, Sch. 10 Pt. 1 (with Sch. 9)
Tax underlying dividendsU.K.
799 Computation of underlying tax.U.K.
F2331. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2331S. 799 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 18, Sch. 10 Pt. 1 (with Sch. 9)
800 Dividends paid between related companies but not covered by arrangements.U.K.
F2332. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2332S. 800 repealed (with effect in accordance with Sch. 30 para. 10(2) of the repealing Act) by Finance Act 2000 (c. 17), Sch. 30 para. 10(1), Sch. 40 Pt. 2(13), Note
801 Dividends paid between related companies: relief for U.K. and third country taxes.U.K.
F2333. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2333Ss. 801-801B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 18, Sch. 10 Pt. 1 (with Sch. 9)
[F2334801A Restriction of relief for underlying tax.U.K.
F2335. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2334S. 801A inserted (with effect in accordance with s. 90(2) of the amending Act) by Finance Act 1997 (c. 16), s. 90(1)
F2335Ss. 801-801B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 18, Sch. 10 Pt. 1 (with Sch. 9)
[F2336801B Dividends paid out of transferred profits.U.K.
F2337. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2336S. 801B inserted (with effect in accordance with Sch. 30 para. 12(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 12(1)
F2337Ss. 801-801B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 18, Sch. 10 Pt. 1 (with Sch. 9)
[F2338801C Separate streaming of dividend so far as representing an ADP dividend of a CFC.U.K.
F2339. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2338S. 801C inserted (with effect in accordance with Sch. 30 para. 13(2)(3) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 13(1)
F2339S. 801C omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(4) (with Sch. 16 paras. 7, 8)
802 U.K. insurance companies trading overseas.U.K.
F2340. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2340S. 802 repealed (with effect in accordance with Sch. 30 para. 14(2) of the repealing Act) by Finance Act 2000 (c. 17), Sch. 30 para. 14(1), Sch. 40 Pt. 2(13), Note
803 Underlying tax reflecting interest on loans.U.K.
F2341. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2341Ss. 803-804E repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
[F2342803A Foreign taxation of group as a single entity.U.K.
F2343. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2342S. 803A inserted (with effect in accordance with Sch. 30 para. 15(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 15(1)
F2343Ss. 803-804E repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
Miscellaneous rulesU.K.
804 Relief against income tax in respect of income arising in years of commencement.U.K.
F2344. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2344Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
[F2345804ZASchemes and arrangements designed to increase reliefU.K.
F2346. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2345Ss. 804ZA-804ZC inserted (with effect in accordance with s. 87(3)-(5) of the amending Act) by Finance Act 2005 (c. 7), s. 87(1)
F2346Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
804ZBEffect of notice under section 804ZAU.K.
F2347. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2345Ss. 804ZA-804ZC inserted (with effect in accordance with s. 87(3)-(5) of the amending Act) by Finance Act 2005 (c. 7), s. 87(1)
F2347Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
804ZCNotices under section 804ZA: further provisionU.K.
F2348. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2345Ss. 804ZA-804ZC inserted (with effect in accordance with s. 87(3)-(5) of the amending Act) by Finance Act 2005 (c. 7), s. 87(1)
F2348Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
[F2350804A[F2349Life assurance companies with overseas branches etc: restriction of credit.]U.K.
F2351. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2349S. 804A sidenote substituted (with effect in accordance with Sch. 30 para. 16(6) of the amending Act) by virtue of Finance Act 2000 (c. 17), Sch. 30 para. 16(5)
F2350S. 804A inserted (with effect in accordance with Sch. 7 para. 10 of the amending Act) by Finance Act 1990 (c. 29), Sch. 7 para. 5
F2351Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
[F2352804B Insurance companies carrying on more than one category of business: restriction of credit.U.K.
F2353. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2352S. 804B inserted (with effect in accordance with Sch. 30 para. 17(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 17(1)
F2353Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
[F2354804C Insurance companies: allocation of expenses etc in computations under [F2355section 35 of CTA 2009].U.K.
F2356. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2354Ss. 804C-804E inserted (with effect in accordance with Sch. 30 para. 18(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 18(1)
F2355Words in s. 804C heading substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 251(3) (with Sch. 2 Pts. 1, 2)
F2356Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
804D Interpretation of section 804C in relation to life assurance business etc.U.K.
F2357. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2354Ss. 804C-804E inserted (with effect in accordance with Sch. 30 para. 18(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 18(1)
F2357Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
804E Interpretation of section 804C in relation to other insurance business.U.K.
F2358. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2354Ss. 804C-804E inserted (with effect in accordance with Sch. 30 para. 18(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 18(1)
F2358Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
[F2359804F Interpretation of sections 804A to 804E.U.K.
F2360. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2359S. 804F inserted (with effect in accordance with Sch. 30 para. 19(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 19(1)
F2360S. 804F repealed (with effect in accordance with Sch. 10 para. 17(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 10 para. 14(2)(e), Sch. 27 Pt. 2(10), Note
[F2361804GReduction in credit: payment by reference to foreign taxU.K.
F2362. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2361S. 804G inserted (with effect in accordance with s. 59(13) of the amending Act) by Finance Act 2009 (c. 10), s. 59(2)
F2362Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
805 Elections against credit.U.K.
F2363. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2363Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9)
806 Time limit for claims etc.U.K.
F2364. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2364Ss. 803-804E, 804G-806 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 19, Sch. 10 Pt. 1 (with Sch. 9) (subject to amendment to s. 806 by Finance Act 2008 (c. 9), s. 118(2), Sch. 39 para. 24; S.I. 2009/403, arts. 2(2), 10)
[F2365 Foreign dividends: onshore pooling and utilisation of eligible unrelieved foreign taxU.K.
Textual Amendments
F2365Ss. 806A-806H, 806J and cross-heading inserted (with effect in accordance with Sch. 30 para. 21(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 21(1)
806A Eligible unrelieved foreign tax on dividends: introductory.U.K.
F2366. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2366Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806A by: Corporation Tax Act 2010 (c. 4), s. 1184(1), Sch. 1 para. 114 (with Sch. 2); Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 8 para. 20 (with Sch. 9))
806B The amounts that are eligible unrelieved foreign tax.U.K.
F2367. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2367Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806B by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 8 para. 21 (with Sch. 9))
806C Onshore pooling.U.K.
F2368. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2368Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806C by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 8 para. 22 (with Sch. 9))
806D Utilisation of eligible unrelieved foreign tax.U.K.
F2369. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2369Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806D by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 8 para. 23 (with Sch. 9))
806E Rules for carry back of relievable tax under section 806D.U.K.
F2370. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2370Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9
806F Credit to be given for underlying tax before other foreign tax etc.U.K.
F2371. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2371Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806F by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 8 para. 24 (with Sch. 9))
806G Claims for the purposes of section 806D(4) or (5).U.K.
F2372. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2372Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806G by Finance Act 2008 (c. 9), s. 118(2), Sch. 39 para. 25; S.I. 2009/403, arts. 2(2), 10)
806H Surrender of relievable tax by one company in a group to another.U.K.
F2373. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2373Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9
806J Interpretation of foreign dividend provisions of this Chapter.U.K.
F2374. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2374Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9 (subject to amendment to s. 806J by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 8 para. 25 (with Sch. 9))
[F2375 Application of foreign dividend provisions to branches or agencies in the UK of persons resident elsewhereU.K.
Textual Amendments
F2375S. 806K and cross-heading inserted (with effect in accordance with Sch. 30 para. 22(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 22(1)
806K Application of foreign dividend provisions to branches or agencies in the UK of persons resident elsewhere.U.K.
F2376. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2376Ss. 806A-806K omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 9
[F2377 Unrelieved foreign tax: profits of overseas branch or agencyU.K.
Textual Amendments
F2377Ss. 806L, 806M and cross-heading inserted (with effect in accordance with Sch. 30 para. 23(2)(3) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 23(1)
806L Carry forward or carry back of unrelieved foreign tax.U.K.
F2378. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2378Ss. 806L, 806M repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 26, Sch. 10 Pt. 1
806M Provisions supplemental to section 806L.U.K.
F2379. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2379Ss. 806L, 806M repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 26, Sch. 10 Pt. 1 (subject to amendment to s. 806M by Finance Act 2008 (c. 9), s. 118(2), Sch. 39 para. 26; S.I. 2009/403, arts. 2(2), 10)
CHAPTER IIIU.K. MISCELLANEOUS PROVISIONS
807 Sale of securities with or without accrued interest.U.K.
F2380. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2380Ss. 807, 807A repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 27, Sch. 10 Pt. 1 (with Sch. 9)
[F2381807A Disposals and acquisitions of company loan relationships with or without interest.U.K.
F2382. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2381S. 807A inserted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 46 (with Sch. 15)
F2382Ss. 807, 807A repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 27, Sch. 10 Pt. 1 (with Sch. 9)
[F2383European cross-border transfers of businessU.K.
Textual Amendments
F2383S. 807B and preceding cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 257 (with Sch. 2 Pts. 1, 2)
807BIntroduction to section 807CU.K.
F2384. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2384Ss. 807B-807G repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 28, Sch. 10 Pt. 1 (with Sch. 9)
[F2385807CTax treated as chargeable in respect of transfer of loan relationship, derivative contract or intangible fixed assetsU.K.
F2386. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F2385S. 807C inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 258 (with Sch. 2 Pts. 1, 2)
F2386Ss. 807B-807G repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 28, Sch. 10 Pt. 1 (with Sch. 9)
[F2387European cross-border mergersU.K.
Textual Amendments
F2387S. 807D and preceding cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 259 (with Sch. 2 Pts. 1, 2)
807DIntroduction to section 807EU.K.
F2388. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2388Ss. 807B-807G repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 28, Sch. 10 Pt. 1 (with Sch. 9)
[F2389807ETax treated as chargeable in respect of transfer of loan relationship, derivative contract or intangible fixed assetsU.K.
F2390. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F2389S. 807E inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 260 (with Sch. 2 Pts. 1, 2)
F2390Ss. 807B-807G repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 28, Sch. 10 Pt. 1 (with Sch. 9)
[F2391Transparent entities involved in cross-border transfers and mergersU.K.
Textual Amendments
F2391S. 807F and preceding cross-heading inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 261 (with Sch. 2 Pts. 1, 2)
807FIntroduction to section 807GU.K.
F2392. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2392Ss. 807B-807G repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 28, Sch. 10 Pt. 1 (with Sch. 9)
[F2393807GTax treated as chargeable in respect of relevant transactionsU.K.
F2394. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]]
Textual Amendments
F2393S. 807G inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 262 (with Sch. 2 Pts. 1, 2)
F2394Ss. 807B-807G repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 28, Sch. 10 Pt. 1 (with Sch. 9)
808 Restriction on deduction of interest or dividends from trading income.U.K.
F2395. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2395S. 808 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 115, Sch. 3 Pt. 1 (with Sch. 2)
[F2396808A Interest: special relationship.U.K.
F2397. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2396S. 808A inserted (16.7.1992 with application in relation to interest paid after 14.5.1992) by Finance (No. 2) Act 1992 (c. 48), s.52
F2397Ss. 808A-809 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 29, Sch. 10 Pt. 1 (with Sch. 9)
[F2398808B Royalties: special relationship.U.K.
F2399. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2398S. 808B inserted (with effect in accordance with Sch. 30 para. 25(2) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 25(1)
F2399Ss. 808A-809 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 29, Sch. 10 Pt. 1 (with Sch. 9)
809 Relief in respect of discretionary trusts.U.K.
F2400. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2400Ss. 808A-809 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 29, Sch. 10 Pt. 1 (with Sch. 9)
810 Postponement of capital allowances to secure double taxation relief.U.K.
F2401. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2401S. 810 repealed (with effect in accordance with Sch. 30 para. 26(2) of the repealing Act) by Finance Act 2000 (c. 17), Sch. 30 para. 26(1), Sch. 40 Pt. 2(13), Note
811 Deduction for foreign tax where no credit allowable.U.K.
F2402. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2402S. 811 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 29, Sch. 10 Pt. 1 (with Sch. 9)
812 Withdrawal of right to tax credit of certain non-resident companies connected with unitary states.U.K.
F2403. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2403Ss. 812-814 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
813 Recovery of tax credits incorrectly paid.U.K.
F2404. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2404Ss. 812-814 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
814 Arrangements to avoid section 812.U.K.
F2405. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2405Ss. 812-814 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
815 Power to inspect documents.U.K.
F2406. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2406S. 815 omitted (13.8.2009) by virtue of The Finance Act 2009, Schedule 47 (Consequential Amendments) Order 2009 (S.I. 2009/2035), art. 1, Sch. para. 23
[F2407815A Transfer of a non-UK trade.U.K.
F2408. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2407S. 815A inserted (16.7.1992) by Finance (No. 2) Act 1992 (c. 48), s. 50
F2408Ss. 815A-815B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 32, Sch. 10 Pt. 1 (with Sch. 9)
[F2409815AZAUK residents and foreign enterprisesU.K.
F2410. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2409S. 815AZA inserted (with effect in accordance with s. 59(2) of the amending Act) by Finance Act 2008 (c. 9), s. 59(1)
F2410Ss. 815A-815B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 32, Sch. 10 Pt. 1 (with Sch. 9)
[F2411815AA Mutual agreement procedure and presentation of cases under arrangements.U.K.
F2412. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2411S. 815AA inserted (with effect in accordance with Sch. 30 para. 28(2)(3) of the amending Act) by Finance Act 2000 (c. 17), Sch. 30 para. 28(1)
F2412Ss. 815A-815B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 32, Sch. 10 Pt. 1 (with Sch. 9)
[F2413815B The Arbitration Convention.U.K.
F2414. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2413S. 815B inserted (16.7.1992) by Finance (No. 2) Act 1992 (c. 48), s. 51(1)
F2414Ss. 815A-815B repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 32, Sch. 10 Pt. 1 (with Sch. 9)
[F2415815C Exchange of information with other [F2416territories].U.K.
F2417. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2415S. 815C inserted (28.7.2000) by Finance Act 2000 (c. 17), s. 146(1)
F2416Word in s. 815C sidenote substituted (with effect in accordance with s. 88(3) of the amending Act) by Finance Act 2002 (c. 23), s. 88(2)(b)
F2417S. 815C repealed (19.7.2006) by Finance Act 2006 (c. 25), Sch. 26 Pt. 8(2)
816 Disclosure of information.U.K.
F2418. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2418S. 816 repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 32, Sch. 10 Pt. 1 (with Sch. 9) (subject to the omission of s. 816(3), so far as it continues to have effect, by virtue of Finance Act 2011 (c. 11), Sch. 23 paras. 55(e), 65)
PART XIXU.K. SUPPLEMENTAL
MiscellaneousU.K.
817 Deductions not to be allowed in computing profits or gains.U.K.
F2419. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2419S. 817 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 265, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
818 Arrangements for payments of interest less tax or of fixed net amount.U.K.
F2420. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2420S. 818 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 203, Sch. 3 Pt. 1 (with Sch. 2)
819 Old references to standard rate tax.U.K.
F2421. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2421S. 819 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 204, Sch. 3 Pt. 1 (with Sch. 2)
820 Application of Income Tax Acts from year to year.U.K.
M94 In order to ensure the collection in due time of income tax which may be granted for any year commencing on 6th April, all such provisions contained in the Income Tax Acts as were in force on the preceding day shall have full force and effect with respect to tax which may be so granted, in the same manner as if that tax had been actually granted by Act of Parliament and those provisions had been applied thereto by the Act.
Modifications etc. (not altering text)
C74S. 820 applied (6.4.2005) by Income Tax (Trading and Other Income) Act 2005 (c. 5), s. 883(1)(2), Sch. 2 para. 160
Marginal Citations
M94Source—1970 s.520
821 Under-deductions from payments made before passing of annual Act.U.K.
M95(1)Where, in any year of assessment [F2422or accounting period], any half-yearly or quarterly payments [F2423(or half-periodic or quarterly payments)] have been made on account of any interest, dividends or other annual profits or gains, previously to the passing of the Act imposing income [F2424or corporation] tax for that year [F2425or period], and tax has not been charged thereon or deducted therefrom or has not been charged thereon or deducted therefrom at the rate ultimately imposed for that year [F2425or period]—
(a)the amount not so charged or deducted shall be charged [F2426in respect of those payments to income tax under Chapter 2 of Part 4 of ITTOIA 2005 (interest) or shall be charged to corporation tax][F2427F2428. . . F2429. . . ; and]
(b)the agents entrusted with the payment of the interest, dividends or other annual profits or gains shall furnish to the Board a list containing the names and addresses of the persons to whom payments have been made and the amount of those payments, upon a requisition made by the Board in that behalf.
(2)Any person liable to pay any rent, interest or annuity, or to make any other annual payment—
(a)shall be authorised—
(i)to make any deduction on account of income tax for any year of assessment which he has failed to make previously to the passing of the Act imposing the tax for that year, or
(ii)to make up any deficiency in any such deduction which has been so made,
on the occasion of the next payment of the rent, interest or annuity or making of the other annual payment after the passing of the Act so imposing the tax, in addition to any other deduction which he may be by law authorised to make; and
(b)shall also be entitled, if there is no future payment from which the deduction may be made, to recover the sum which might have been deducted as if it were a debt due from the person as against whom the deduction could originally have been made if the Act imposing the tax for the year had been in force.
(3)Subsection (2) above shall apply with respect to—
[F2430(a)any payment to which section 906 of ITA 2007 applies (certain royalties etc where usual place of abode of owner is abroad), and]
[F2431(aa)F2432. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(b)any royalty or other sum paid in respect of the user of a patent; F2433. . .
F2433(c). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
as it applies with respect to any rent, interest, annuity or other annual payment.
(4)In this section “interest” and “dividends” do not include any interest or dividend which is a distribution.
Textual Amendments
F2422Words in s. 821(1) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 330(a) (with Sch. 2)
F2423Words in s. 821(1) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 330(b) (with Sch. 2)
F2424Words in s. 821(1) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 330(c) (with Sch. 2)
F2425Words in s. 821(1) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 330(d) (with Sch. 2)
F2426Words in s. 821(1)(a) inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 330(e) (with Sch. 2)
F2427Words in s. 821(1)(a) substituted (with effect in accordance with Sch. 6 para. 28 of the amending Act) by Finance Act 1996 (c. 8), Sch. 6 para. 22
F2428Words in s. 821(1)(a) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 266, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2429Words in s. 821(1)(a) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 330(f), Sch. 3 (with Sch. 2)
F2430S. 821(3)(a) substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 205(a) (with Sch. 2)
F2431S. 821(3)(aa) inserted (1.8.1989) by Copyright, Designs and Patents Act 1988 (c. 48), Sch. 7 para. 36(7); S.I. 1989/816 art. 2
F2432S. 821(3)(aa) and word repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 205(b), Sch. 3 Pt. 1 (with Sch. 2)
F2433S. 821(3)(c) and preceding word repealed (with effect in accordance with Sch. 18 Pt. 6(2) Note of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(2)
Marginal Citations
M95Source—1970 s.521; 1972 Sch.24 29; 1983 s.27.
822 Over-deductions from interest on loan capital etc. made before passing of annual Act.U.K.
M96(1)If in any year of assessment (“the year”) a resolution having statutory effect under the Provisional Collection of Taxes Act 1968 provides for the charging of income tax at a [F2434lower rate less] than that charged for the previous year, the following provisions of this section shall have effect with respect to deductions in respect of income tax by any body corporate, from payments of interest (not being a distribution) on any of its securities.
(2)Any deduction which was made before the expiration of one month from the passing of the resolution and which would, if the tax had been renewed at the rate imposed for the previous year, have been a legal deduction, shall be deemed to be a deduction rendered legal by section 2 of the Provisional Collection of Taxes Act 1968 and that section shall, subject to this section, apply accordingly.
(3)Any over-deduction to be made good under that section may be made good by a reduction of the amount of tax deducted from the next payment of like nature made on the security in question after the passing of the Act imposing the tax for the year.
(4)Any amount made good under section 2 of the Provisional Collection of Taxes Act 1968 shall—
(a)in the case of an over-deduction which is made good under subsection (3) above, enure to the benefit of the person entitled to the payment on the occasion of which the over-deduction is made good; and
(b)in any other case, enure to the benefit of the person entitled to the security in question at the date when the amount is made good,
irrespective, in either case, of whether or not he is the person who was entitled to the payment, or to the security at the date when the original deduction was made.
(5)Subsection (3) above shall not authorise the retention of any part of the amount over-deducted for more than one year from the passing of the Act imposing the tax for the year.
Textual Amendments
F2434Words in s. 822(1) substituted (with effect in accordance with Sch. 6 para. 28 of the amending Act) by Finance Act 1996 (c. 8), Sch. 6 para. 23
Marginal Citations
M96Source—1970 s.522; 1971 Sch.6 76; 1972 Sch.24 30
823 Adjustments of reliefs where given at different times.U.K.
F2435. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2435S. 823 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 206, Sch. 3 Pt. 1 (with Sch. 2)
824 Repayment supplements: individuals and others.U.K.
[F2436(1)Subject to the following provisions of this section, a repayment made by the Board or an officer of the Board of any of the following, namely—
(a)an amount paid on account of income tax under section 59A of the Management Act;
(b)any income tax paid by or on behalf of an individual for a year of assessment;
[F2437[F2438(c)a penalty payable under any paragraph of Schedule 56 to the Finance Act 2009 in respect of an amount falling within any of the following items of the Table in paragraph 1 of that Schedule—
(i)item 1, 12, 18 or 19; or
(ii)insofar as the tax falls within item 1, item 17, 23 or 24; and]]
(d)a penalty incurred by an individual under any of the provisions of [F2439that Act] [F2439the Finance Act 2009 or Schedules 24 to 26 to the Finance Act 2021],
shall be increased under this section by an amount (a “repayment supplement”) equal to interest on the amount repaid at the rate applicable under section 178 of the Finance Act 1989 for the period (if any) between the relevant time and the date on which the order for the repayment is issued.]
F2440(1A). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F2441(2). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F2442(2A)Subsection (1) above shall apply to a repayment made in consequence of a claim under section 228 of the Income Tax Act 1952 (relief in respect of income accumulated under trusts) as if the repayment were of income tax paid by the claimant for the year of assessment in which the contingency mentioned in that section happened.]
[F2443(2B)Subsection (1) above shall apply to a payment made by the Board under section 375(8) (payment of amount which borrower would have been able to deduct from interest payment under section 369(1)) as if the payment were a repayment falling within that subsection.]
[F2444(2C)Subsection (1) above shall apply to a repayment made by the Board as a result of a claim for relief under—
(a)paragraph 2 of Schedule 1B to the Management Act (carry back of loss relief),
(b)paragraph 3 of that Schedule (relief for fluctuating profits of farming etc.), or
(c)Schedule 4A to this Act (relief for fluctuating profits of creative artists etc.),
as if it were a repayment falling within that subsection.]
[F2445(2D)Subsection (1) shall apply—
F2446(a). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(b)to a payment made under paragraph 6(1) of Schedule 14 (payment where entitlement to life assurance premium relief has not been given by deduction) as if the payment were a repayment of income tax paid for the tax year in which the entitlement to relief arose.]
[F2447(3)For the purposes of subsection (1) above—
[F2448(aa)if the repayment is a payment made by the Board under section 375(8), the relevant time is—
(i)if the interest payment was made in the year 1996-97 or a subsequent year of assessment, the 31st January next following that year;
(ii)if the interest payment was made in an earlier year of assessment, the 5th April next following that year;]
[F2449(ab)if the repayment is a repayment as a result of a claim for relief under any of the provisions mentioned in subsection (2C) above, the relevant time is the 31st January next following the year that is the later year in relation to the claim;]
[F2450(ac)if the repayment is a repayment as a result of a claim under section 496B of ITA 2007 (relief for payments by discretionary trust taxable as employment income), the relevant time is the 31 January next following the end of the tax year to which the claim relates;]
[F2451(ad)if the repayment is a payment falling within subsection (2D)(b), the relevant time is 31 January next following the end of the tax year in which the entitlement to relief arose;]
[F2452(a)if the repayment is—
(i)the repayment of an amount paid in accordance with the requirements of section 59A of the Management Act on account of income tax for a year of assessment, or
(ii)the repayment of income tax for such a year which is not income tax deducted at source [F2453(other than a repayment within paragraph (ac))],
the relevant time is the date of the payment that is being repaid;
(b)if the repayment is of income tax deducted at source for a year of assessment, the relevant time is the 31st January next following that year; and]
(c)if the repayment is of a penalty or surcharge, [F2454the relevant time is the date on which the penalty or surcharge was paid].]
[F2455(4)For the purposes of subsection (3) above, where a repayment in respect of income tax for a year of assessment is made to any person, that repayment—
(a)shall be attributed first to so much of any payment made by him under section 59B of the Management Act as is a payment in respect of income tax for that year;
(b)in so far as it exceeds the amount (if any) to which it is attributable under paragraph (a) above, shall be attributed in two equal parts to each of the payments made by him under section 59A of the Management Act on account of income tax for that year;
(c)in so far as it exceeds the amounts (if any) to which it is attributable under paragraphs (a) and (b) above, shall be attributed to income tax deducted at source for that year; and
(d)in so far as it is attributable to a payment made in instalments shall be attributed to a later instalment before being attributed to an earlier one.
(4A)In this section any reference to income tax deducted at source for a year of assessment is a reference to—
(a)income tax deducted or treated as deducted from any income, or treated as paid on any income, in respect of that year, F2456. . .
F2456(b). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
but does not include a reference to amounts which, in that year, are deducted at source under [F2457PAYE regulations] in respect of previous years.]
F2458(5). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)F2459... The Treasury may by order from time to time increase or decrease the rate of interest by reference to which—
(a)repayment supplements are calculated under subsection (1) above; and
(b)repayment supplements are calculated under section 47 of the Finance (No. 2) Act 1975.
(7)A repayment supplement shall not be payable under this section in respect of a repayment or payment made in consequence of an order or judgment of a court having power to allow interest on the repayment or payment, or in respect of a repayment of a post-war credit within the meaning of the Income Tax (Repayment of Post-War Credits) Act 1959.
(8)F2460. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(9)M97Subsections (1) [F2461to (7)] above shall apply in relation to F2462. . . [F2463the trustees of a settlement] [F2464, scheme administrators of registered pension schemes sub-scheme administrators of sub-schemes which form part of a split scheme pursuant to the Registered Pensions (Splitting of Schemes) Regulations 2006] [F2465or personal representatives F2462 ... ] as they apply in relation to an individual.
F2466(10). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2436S. 824(1) substituted (with effect in accordance with s. 199(2)(3), Sch. 19 para. 41(4) of the amending Act) by Finance Act 1994 (c. 9), Sch. 19 para. 41(1); S.I. 1998/3173, art. 2
F2437S. 824(1)(c) omitted (6.4.2024 for specified purposes, 1.4.2026 for specified purposes) by virtue of Finance Act 2021 (c. 26), s. 118(2), Sch. 27 para. 10(a); S.I. 2024/440, reg. 2; S.I. 2026/370, reg. 3
F2438S. 824(1)(c) substituted (1.4.2011) by The Finance Act 2009, Schedules 55 and 56 (Income Tax Self Assessment and Pension Schemes) (Appointed Days and Consequential and Savings Provisions) Order 2011 (S.I. 2011/702), arts. 1(1), 11 (with arts. 20, 22)
F2439Words in s. 824(1)(d) substituted (6.4.2024 for specified purposes, 1.4.2026 for specified purposes) by Finance Act 2021 (c. 26), s. 118(2), Sch. 27 para. 10(b); S.I. 2024/440, reg. 2; S.I. 2026/370, reg. 3
F2440S. 824(1A) repealed (from 18.8.1989) by Finance Act 1989 (c. 26), ss. 178(7), 187, Sch. 17 Pt. 10, Note; S.I. 1989/1298
F2441S. 824(2) omitted (with effect in accordance with Sch. 1 para. 73 of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(3)
F2442S. 824(2A) inserted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 7(d)
F2443S. 824(2B) inserted (retrospectively, with effect in accordance with s. 41(4)-(6) of the amending Act) by Finance Act 1999 (c. 16), s. 41(2)
F2444S. 824(2C) inserted (with effect in accordance with s. 90(4) of the amending Act) by Finance Act 2001 (c. 9), s. 90(2)
F2445S. 824(2D) inserted (1.4.2011 with effect in accordance with art. 9(1) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2011 (S.I. 2011/1037), arts. 1, 7(2)
F2446S. 824(2D)(a) omitted (with effect in accordance with Sch. 39 para. 31(3) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 39 para. 31(2)(a)
F2447S. 824(3) substituted (with effect in accordance with s. 199(2)(3), Sch. 19 para. 41(4) of the amending Act) by Finance Act 1994 (c. 9), Sch. 19 para. 41(2); S.I. 1998/3173, art. 2
F2448S. 824(3)(aa) inserted (retrospectively, with effect in accordance with s. 41(4)-(6) of the amending Act) by Finance Act 1999 (c. 16), s. 41(3)
F2449S. 824(3)(ab) inserted (with effect in accordance with s. 90(4) of the amending Act) by Finance Act 2001 (c. 9), s. 90(3)
F2450S. 824(3)(ac) inserted (1.4.2010 with effect in accordance with art. 4(3) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2010 (S.I. 2010/157), arts. 1, 4(1)(a)
F2451S. 824(3)(ad) inserted (1.4.2011 with effect in accordance with art. 9(1) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2011 (S.I. 2011/1037), arts. 1, 7(3)
F2452S. 824(3)(a)(b) substituted (with effect in accordance with s. 92(6) of the amending Act) by Finance Act 1997 (c. 16), s. 92(2)
F2453Words in s. 824(3)(a)(ii) inserted (1.4.2010 with effect in accordance with art. 4(3) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2010 (S.I. 2010/157), arts. 1, 4(1)(b)
F2454Words in s. 824(3)(c) substituted (with effect in accordance with s. 92(6) of the amending Act) by Finance Act 1997 (c. 16), s. 92(3)
F2455S. 824(4)(4A) substituted for s. 824(4) (with effect in accordance with s. 92(6) of the amending Act) by Finance Act 1997 (c. 16), s. 92(4)
F2456S. 824(4A)(b) and preceding word omitted (with effect in accordance with Sch. 1 para. 73 of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(4)
F2457Words in s. 824(4A) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 104 (with Sch. 7)
F2458S. 824(5) repealed (with effect in accordance with s. 199(2)(3), Sch. 19 para. 41(4) of the repealing Act) by Finance Act 1994 (c. 9), Sch. 19 para. 41(3)(a), Sch. 26 Pt. 5(23), Note 3; S.I. 1998/3173, art. 2
F2459Words in s. 824(6) repealed (from 18.8.1989) by Finance Act 1989 (c. 26), ss. 178(7), 187, Sch. 17 Pt. 10, Note; S.I. 1989/1298
F2460S. 824(8) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 331(3), Sch. 3 (with Sch. 2)
F2461Words in s. 824(9) substituted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 331(4) (with Sch. 2)
F2462Words in s. 824(9) repealed (with effect in accordance with s. 199(2)(3), Sch. 19 para. 41(4) of the repealing Act) by Finance Act 1994 (c. 9), Sch. 19 para. 41(3)(b), Sch. 26 Pt. 5(23), Note 3; S.I. 1998/3173, art. 2
F2463Words in s. 824(9) substituted (1989-90 and subsequent years) by Finance Act 1989 (c. 26), s. 110(5)(6)-(9)
F2464Words in s. 824(9) inserted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 33 (as amended by The Registered Pension Schemes (Splitting of Schemes) Regulations 2006 (S.I. 2006/569), regs. 1(1), 5(6)(7)) (with Sch. 36)
F2465Words in s. 824(9) substituted (1989-90 and subsequent years) by Finance Act 1989 (c. 26), s. 111(4)(5)-(8)
F2466S. 824(10) repealed (with effect in accordance with s. 199(2)(3), Sch. 19 para. 41(4) of the repealing Act) by Finance Act 1994 (c. 9), Sch. 19 para. 41(3)(c), Sch. 26 Pt. 5(23), Note 3; S.I. 1998/3173, art. 2
Modifications etc. (not altering text)
C75S. 824 excluded (27.7.1993 with effect for the year 1992-93 and subsequent years of assessment) by Finance Act 1993 (c. 34), ss. 173, 184(3), Sch. 19 Pt. III para. 13(4)
C76S. 824 excluded (2.1.1996) by The Lloyd's Underwriters (Gilt-edged Securities) (Periodic Accounting for Tax on Interest) Regulations 1995 (S.I. 1995/3225), reg. 12(2) (with reg. 13)
C77S. 824 excluded (27.12.2005 with effect in accordance with reg. 1(2) of the affecting S.I.) by The Lloyd's Underwriters (Tax) Regulations 2005 (S.I. 2005/3338), regs. 1(1), 14(4)
C78S. 824 restricted (1.4.2011) by The Finance Act 2009, Sections 101 to 103 (Income Tax Self Assessment) (Appointed Days and Transitional and Consequential Provisions) Order 2011 (S.I. 2011/701), arts. 1(1), 4(2)(a), 5
C79S. 824 excluded (5.10.2020) by The Finance Act 2009, Sections 101 and 102 (Disguised Remuneration Repayment Scheme) (Appointed Day and Consequential Amendment) Order 2020 (S.I. 2020/979), arts. 1, 4
C80S. 824(3) modified (22.7.2004) by Finance Act 2004 (c. 12), s. 108
C81S. 824(3) modified (1.4.2010 with effect in accordance with s. 381(1) of the modifying Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 137 (with Sch. 9)
Marginal Citations
M97Source—1975 (No.2) s.47(11), (12).
825 Repayment supplements: companies.U.K.
(1)M98This section applies to the following payments made to a company in connection with any accounting period for which the company was resident in the United Kingdom (“the relevant accounting period”), that is to say—
(a)a repayment of corporation tax paid by the company for that accounting period (including advance corporation tax paid in respect of distributions made by the company in that accounting period F2467. . . ); or
(b)a repayment of income tax in respect of a payment received by the company in that accounting period on which the company bore income tax by deduction; F2468. . .
(c)F2468. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)Subject to the following provisions of this section, where a payment F2469. . . to which this section applies is made by the Board or an inspector after the end of the 12 months beginning with the material date, the payment shall be increased under this section by an amount (a “repayment supplement”) equal to interest on the amount paid at the [F2470rate applicable under section 178 of the Finance Act 1989] for each complete tax month contained in the period (if any) beginning with the relevant date and ending at the end of the tax month in which the order for the payment is issued.
[F2471F2472(2A). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(3)M99For the purposes of subsection (2) above—
(a)if the payment is a repayment of corporation tax that was paid on or after the first anniversary of the material date, the relevant date is the anniversary of the material date that occurs next after the date on which that tax was paid;
(b)in any other case, the relevant date is the first anniversary of the material date;
and where a payment to which this section applies is a repayment of corporation tax paid by a company on different dates, the payment shall as far as possible be treated for the purposes of this subsection as a repayment of tax paid on a later rather than an earlier date among those dates.
(4)For the purposes of this section—
(a)a repayment of corporation tax made in consequence of a claim by a company under section 239(3) to have the whole or any part of an amount of surplus advance corporation tax arising in the case of any accounting period treated as if it were advance corporation tax paid in respect of distributions made by the company in any earlier accounting period shall be treated as a repayment of corporation tax paid for the accounting period in the case of which that amount of surplus advance corporation tax arose; and
(b)a repayment of income tax or corporation tax made on a claim under subsection (4) of section 419 shall be treated as if it were a repayment of corporation tax paid for the accounting period in which the repayment of, or of the part in question of, the loan or advance mentioned in that subsection was made; [F2473and
(c)a repayment of corporation tax or income tax falling to be made as a result of a claim under section 393A(1) to have the whole or any part of a loss incurred in an accounting period set off against profits of an earlier accounting period (“the earlier period”)—
(i)shall, in a case where the earlier period falls wholly within the period of twelve months immediately preceding the accounting period in which the loss was incurred, be treated as a repayment of tax paid for the earlier period; and
(ii)in any other case, shall be treated as a repayment of tax paid for the accounting period in which the loss is incurred; and
F2474(d). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(5)[F2475F2476. . . ] The Treasury may by order from time to time increase or decrease the rate of interest by reference to which repayment supplements are calculated under subsection (2) above.
(6)A repayment supplement shall not be payable under this section in respect of a payment made in consequence of an order or judgment of a court having power to allow interest on the payment.
(7)A repayment supplement paid under this section shall be disregarded for all purposes of income tax and corporation tax.
(8)In this section—
“tax month” means the period beginning with the 6th day of any calendar month and ending with the 5th day of the following calendar month;
“the material date” in relation to a payment to which this section applies, means the last date on which corporation tax on any of the profits of the company in question arising in the relevant accounting period could have been paid—
(a)in a case where section 10(1) applies, within the nine months there mentioned;
(b)in a case where section 478 applies, within the time limit imposed by subsection (2)(a) of that section, but subject to subsection (6) of that section.
(9)This section has effect subject to section 826(8).
Textual Amendments
F2467Words in s. 825(1)(a) repealed (for accounting periods beginning after 31.3.1989) by Finance Act 1989 (c. 26), s. 187, Sch. 17 Pt. V, Note 6
F2468S. 825(1)(c) and preceding word omitted (with effect in accordance with Sch. 1 para. 73 of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(5)
F2469Words in s. 825(2) repealed (with effect in relation to payments made on and after 6.4.1993) by Finance Act 1989 (c. 26), ss. 158(2), 187, Sch. 17 Pt. 8, Note 5; S.I. 1993/753
F2470Words in s. 825(2) substituted (from 18.8.1989) by Finance Act 1989 (c. 26), s. 179(1)(a)(vii); S.I. 1989/1298
F2471S. 825(2A) inserted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 8(a)
F2472S. 825(2A) repealed (from 18.8.1989) by Finance Act 1989 (c. 26), ss. 178(7), 187, Sch. 17 Pt. 10, Note; S.I. 1989/1298
F2473Words in s. 825(4) added by Finance Act 1991 (c. 31, SIF 63:1), s. 73(3)(4)(5), Sch. 15 para.22
F2474S. 825(4)(d) repealed (with effect in accordance with s. 20 of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 8 Pt. 2(4), Note
F2475Words in s. 825(2A) inserted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 8(b)
F2476Words in s. 825(5) repealed (from 18.8.1989) by Finance Act 1989 (c. 26), ss. 178(7), 187, Sch. 17 Pt. 10, Note; S.I. 1989/1298
Modifications etc. (not altering text)
C82S. 825(4)(a) modified (27.7.1993) by Finance Act 1993 (c. 34), s. 120, Sch. 14 para. 10(6)
S. 825(4)(a) modified (1.5.1995) by Finance Act 1995 (c. 4), s. 120, Sch. 24 para. 12(5)
Marginal Citations
M98Source—1975 (No.2) s.48(1), (2)
M99Source—1975 (No.2) s.48(4)-(9)
826 Interest on tax overpaid.U.K.
M100(1)In any case where—
(a)a repayment falls to be made of corporation tax paid by a company for an accounting period which ends after the appointed day; or
[F2477(aa)a repayment falls to be made under sections 246N and 246Q of advance corporation tax paid by a company in respect of distributions made by it in such an accounting period; or]
(b)a repayment of income tax falls to be made in respect of a payment received by a company in such an accounting period; or
(c)F2478. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F2479(d)a payment of R&D tax credit falls to be made to a company under [F2480Chapter 2 or 7 of Part 13 of CTA 2009] in respect of an accounting period][F2481; or
[F2482(da)F2483. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(e)a payment of land remediation tax credit or life assurance company tax credit falls to be made to a company under [F2484Part 14 of CTA 2009] in respect of an accounting period][F2485; or
(f)a payment of film tax credit falls to be made to a company][F2486, or
[F2487(fa)a payment of television tax credit falls to be made to a company; or
(fb)a payment of video game tax credit falls to be made to a company; or]
[F2488(fc)a payment of theatre tax credit falls to be made to a company; or]
[F2489(fd)a payment of orchestra tax credit falls to be made to a company; or]
[F2490(fe)a payment of museums and galleries exhibition tax credit falls to be made to a company; or]
(g)a payment of first-year tax credit falls to be made to a company under Schedule A1 to the Capital Allowances Act,]
then, from the material date until [F2491the order for repayment or payment is issued], the repayment or payment shall carry interest at the rate which, under section 89 of the Management Act, is for the time being the prescribed rate for the purposes of this section.
(2)[F2492Subject to section 826A(2),] in relation to corporation tax paid by a company for an accounting period, the material date for the purposes of this section is the date on which corporation tax was paid or, if it is later, the date on which corporation tax for that accounting period became (or, as the case may be, would have become) due and payable in accordance with [F2493section 59D of the Management Act (payment of corporation tax)].
[F2494(2A)F2495. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(3)In relation to a repayment of income tax falling within subsection (1)(b) above F2496. . . , [F2497the material date is the day after the end of the accounting period] in which the payment referred to in subsection (1)(b) above F2498. . . was received by the company.
[F2499(3A)In relation to a payment of R&D tax credit falling within subsection (1)(d) above the material date is whichever is the later of—
(a)the filing date for the company’s company tax return for the accounting period for which the R&D tax credit is claimed, and
(b)the date on which the company tax return or amended company tax return containing the claim for payment of the R&D tax credit is delivered to the Inland Revenue.
For this purpose “the filing date”, in relation to a company tax return, has the same meaning as in Schedule 18 to the M101Finance Act 1998.]
[F2500(3AA)F2501. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F2502(3B)In relation to a payment of land remediation tax credit or life assurance company tax credit falling within subsection (1)(e) above the material date is whichever is the later of—
(a)the filing date for the company’s company tax return for the accounting period for which the land remediation tax credit or the life assurance company tax credit is claimed, and
(b)the date on which the company tax return or amended company tax return containing the claim for payment of the land remediation tax credit or the life assurance company tax credit is delivered to the Inland Revenue.
For this purpose “the filing date”, in relation to a company tax return, has the same meaning as in Schedule 18 to the Finance Act 1998.]
[F2503(3C)In relation to a payment of film tax credit [F2504, television tax credit [F2505, video game tax credit [F2506, theatre tax credit [F2507, orchestra tax credit or museums and galleries exhibition tax credit]]]] the material date is whichever is the later of—
(a)the filing date for the company's company tax return for the accounting period for which the tax credit is payable, and
(b)the date on which the company tax return or amended company tax return containing the claim for payment is delivered to an officer of Revenue and Customs.
For this purpose “the filing date”, in relation to a company tax return, has the same meaning as in Schedule 18 to the Finance Act 1998.]
[F2508(3D)In relation to a payment of first-year tax credit falling within subsection (1)(g) above the material date is whichever is the later of—
(a)the filing date for the company's company tax return for the accounting period for which the tax credit is claimed, and
(b)the date on which the company tax return or amended company tax return containing the claim for payment of the tax credit is delivered to the Commissioners for Her Majesty's Revenue and Customs.
For this purpose “the filing date”, in relation to a company tax return, has the same meaning as in Schedule 18 to the Finance Act 1998.]
(4)For the purposes of this section a repayment of tax made on a claim under [F2509section 458 of CTA 2010] shall be treated as if it were a repayment of corporation tax for the accounting period in which [F2510the event giving rise to entitlement to relief under [F2511that section] occurred] but, in relation to such a repayment of tax, the material date for the purposes of this section is—
[F2512(a)the date when the entitlement to relief in respect of the repayment accrued, that is to say—
(i)where the repayment [F2513, or the release or writing off,] of the loan or advance (or part thereof) occurred on or after the day mentioned in [F2514section 458(4) of CTA 2010], the date nine months after the end of that accounting period; and
(ii)in any other case, the date nine months after the end of the accounting period in which the loan or advance was made;
or]
(b)if it is later, the date on which the tax which is to be repaid was in fact paid.
(5)F2515. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F2516(5A)F2515. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(6)Where a repayment of corporation tax is a repayment of tax paid by a company on different dates, the repayment shall so far as possible be treated for the purposes of this section as a repayment of tax paid on a later rather than an earlier date among those dates.
(7)F2517. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F2518[F2519(7A)In any case where—
(a)a company carrying on a trade incurs a loss in the trade in an accounting period (“the later period”),
(b)as a result of a claim under [F2520section 37 of CTA 2010], the whole or any part of that loss is [F2521relieved][F2522(whether under [F2523section 37 or 42 of that Act])] for the purposes of corporation tax against profits (of whatever description) of an earlier accounting period (“the earlier period”) which does not fall wholly within the period of twelve months immediately preceding the later period, and
(c)a repayment falls to be made of corporation tax paid for the earlier period or of income tax in respect of a payment received by the company in that accounting period,
then, in determining the amount of interest (if any) payable under this section on the repayment referred to in paragraph (c) above, no account shall be taken of [F2524so much of the amount of that repayment as falls to be made]] as a result of the claim under [F2525section 37 of CTA 2010], except so far as concerns interest for any time after the date on which any corporation tax for the later period became (or, as the case may be, would have become) due and payable, [F2526as mentioned in subsection (7D) below].
[F2519(7AA)F2527. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F2528(7AA)In any case where—
(a)a company ceases to carry on a trade in an accounting period (“the terminal period”),
(b)as a result of a claim under section 45F of CTA 2010, the whole or any part of a loss made in the trade is relieved for the purposes of corporation tax against profits (of whatever description) of an earlier accounting period (“the earlier period”) which does not fall wholly within the period of 12 months immediately preceding the terminal period, and
(c)a repayment falls to be made of corporation tax paid for the earlier period or of income tax in respect of a payment received by the company in that accounting period,
then, in determining the amount of interest (if any) payable under this section on the repayment referred to in paragraph (c) above, no account shall be taken of so much of the amount of that repayment as falls to be made as a result of the claim under section 45F, except so far as concerns interest for any time after the date on which any corporation tax for the terminal period became (or, as the case may be, would have become) due and payable, as mentioned in subsection (7D) below).]
F2529(7B). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F2530(7BB)Subject to subsection (7BC) below, in any case where—
(a)within the meaning of section 806D, any relievable underlying tax or relievable withholding tax arises in an accounting period of a company (“the later period”),
(b)pursuant to a claim under section 806G, the whole or any part of that tax is treated as mentioned in section 806D(4)(c) or (5)(c) in relation to the single related dividend or the single unrelated dividend arising in an earlier accounting period (“the earlier period”), and
(c)a repayment falls to be made of corporation tax paid for the earlier period or of income tax in respect of a payment received by the company in that period,
then, in determining the amount of interest (if any) payable under this section on the repayment referred to in paragraph (c) above, no account shall be taken of so much of the amount of the repayment as falls to be made as a result of the claim under section 806G, except so far as concerns interest for any time after the date on which any corporation tax for the later period became due and payable (as mentioned in subsection (7D) below).
(7BC)F2531. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F2532(7C)In a case where—
(a)there is for an accounting period of a company (“the later period”) [F2533a non-trading deficit on the company’s loan relationships,]
(b)as a result of a claim under [F2534[F2535section 389(1) or 459(1)(b) of CTA 2009] the whole or part of the deficit for the later period is set off against profits] of an earlier accounting period (“the earlier period”), and
(c)a repayment falls to be made of corporation tax for the earlier period [F2536or of income tax in respect of a payment received by the company in that accounting period],
then, in determining the amount of interest (if any) payable under this section on the [F2537repayment referred to in paragraph (c) above, no account shall be taken of so much of the amount of the repayment as falls to be made as a result of] the claim under [F2538section 389(1) or 459(1)(b) of CTA 2009] except so far as concerns interest for any time after the date on which any corporation tax for the later period became (or, as the case may be, would have become) due and payable, [F2526as mentioned in subsection (7D) below].]
F2539[F2540(7CA). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F2541(7D)In subsections (7), (7A), [F2542(7AA),] (7B) [F2543, (7BB)] and (7C) above, any reference to the date on which corporation tax for an accounting period became, or would have become, due and payable shall be construed on the basis that corporation tax for an accounting period becomes due and payable on the day following the expiry of nine months from the end of the accounting period.]
[F2544(7E)The power conferred by section 59E of the Management Act (alteration of date on which corporation tax becomes due and payable) does not include power to make provision in relation to subsection (7), (7A), [F2545(7AA)] (7B), [F2546(7BB),] (7C) or (7D) above the effect of which would be to change the meaning of references in subsection (7), (7A), [F2545(7AA)] (7B) [F2546, (7BB)] or (7C) above to the date on which corporation tax for an accounting period became, or would have become, due and payable (as mentioned in subsection (7D) above).]
(8)In consequence of the preceding provisions of this section, no repayment supplement (within the meaning of section 825) shall be paid in respect of any repayment of tax or payment of tax credit where the relevant accounting period (within the meaning of that section) ends after the appointed day.
[F2547(8A)Where—
(a)interest has been paid to a company under subsection (1)(a) [F2548[F2549, (d)]][F2550[F2551, (e) [F2552(f), (fa), (fb) [F2553, (fc) [F2554, (fd) or (fe)]]]]] above,
[F2555(b)there is—
(i)a change in the company’s assessed liability to corporation tax, or
(ii)a change in the amount of the R&D tax credit F2556[F2557. . . ][F2558, land remediation tax credit or life assurance company tax credit][F2559or film tax credit][F2560or television tax credit or video game tax credit][F2561or theatre tax credit][F2562or orchestra tax credit][F2563or museums and galleries exhibition tax credit][F2564or first-year tax credit under Schedule A1 to the Capital Allowances Act] payable to the company (which does not result in a change falling within sub-paragraph (i)),
other than a change which in whole or in part corrects an error made by the Board or an officer of the Board, and]
(c)as a result only of that change (and, in particular, not as a result of any error in the calculation of the interest), it appears to an officer of the Board that the interest ought not to have been paid, either at all or to any extent,
the interest that ought not to have been paid may be recovered from the company as if it were interest charged under Part IX of the Management Act (interest on overdue tax).
(8B)For the purposes of subsection (8A) above, the cases where there is a change in a company’s assessed liability to corporation tax are those cases where—
(a)an assessment, or an amendment of an assessment, of the amount of corporation tax payable by the company for the accounting period in question is made, or
(b)a determination of that amount is made under paragraph 36 or 37 of Schedule 18 to the Finance Act 1998 (which until superseded by a self-assessment under that Schedule has effect as if it were one),
whether or not any previous assessment or determination has been made.
[F2565(8BA)For the purposes of subsection (8A)(b) above, the cases where there is a change in the amount of the R&D tax credit F2566[F2567. . . ][F2568, the land remediation tax credit or the life assurance company tax credit][F2569or film tax credit][F2570or television tax credit or video game tax credit][F2571or theatre tax credit][F2572or orchestra tax credit][F2573or museums and galleries exhibition tax credit][F2574or first-year tax credit under Schedule A1 to the Capital Allowances Act] payable to the company are those cases where an assessment, or an amendment to an assessment, is made to recover an amount of R&D tax credit F2566[F2567. . . ][F2575, land remediation tax credit or life assurance company tax credit][F2569or film tax credit][F2570or television tax credit or video game tax credit][F2571or theatre tax credit][F2572or orchestra tax credit][F2573or museums and galleries exhibition tax credit][F2574or first-year tax credit under Schedule A1 to the Capital Allowances Act] paid to the company for the accounting period in question.]
(8C)In subsection (8A)(b) above “error” includes—
(a)any computational error; and
(b)the allowance of a claim or election which ought not to have been allowed.]
(9)In this section “the appointed day” means such day or days, not being earlier than 31st March 1992, as the Treasury may by order appoint for the purposes of this section.
Subordinate Legislation Made
P2S. 826(1)(8)(9) power exercised: 30.9.1993 appointed by S.I. 1992/3066, art. 2(2)(b)
Textual Amendments
F2477S. 826(1)(aa) inserted (3.5.1994) by Finance Act 1994 (c. 9), Sch. 16 para. 20(2)
F2478S. 826(1)(c) and word omitted (with effect in accordance with Sch. 1 para. 73 of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(6)(a)
F2479S. 826(1)(d) and preceding word inserted (with effect in accordance with s. 69(1) of the amending Act) by Finance Act 2000 (c. 17), Sch. 21 para. 1(2)
F2480Words in s. 826(1)(d) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(2)(a) (with Sch. 2 Pts. 1, 2, para. 56)
F2481S. 826(1)(e) and preceding word inserted (with effect in accordance with s. 70(1) of the amending Act) by Finance Act 2001 (c. 9), Sch. 23 para. 3(2)
F2482S. 826(1)(da) inserted (with effect in accordance with Sch. 14 para. 5 of the amending Act) by Finance Act 2002 (c. 23), Sch. 14 para. 1(2)
F2483S. 826(1)(da) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(2)(b), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2, para. 56)
F2484Words in s. 826(1)(e) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(2)(c) (with Sch. 2 Pts. 1, 2, para. 56)
F2485S. 826(1)(f) and preceding word inserted (1.1.2007) by Finance Act 2006 (c. 25), s. 53(1), Sch. 5 para. 26(2); S.I. 2006/3399, art. 2
F2486S. 826(1)(g) and preceding word inserted (with effect in accordance with Sch. 25 para. 9 of the amending Act) by Finance Act 2008 (c. 9), Sch. 25 para. 7(2)
F2487S. 826(1)(fa)(fb) inserted (19.7.2013 for specified purposes and 1.4.2014 for remaining purposes, and with effect in accordance with Sch. 18 para. 23 of the amending Act and S.I. 2014/1962, art. 2(2)) by Finance Act 2013 (c. 29), Sch. 18 paras. 1(2), 22; S.I. 2013/1817, art. 2(2); S.I. 2014/1962, art. 2(3)
F2488S. 826(1)(fc) inserted (22.8.2014 with effect in accordance with Sch. 4 para. 17 of the amending Act) by Finance Act 2014 (c. 26), Sch. 4 paras. 2(2), 16; S.I. 2014/2228, art. 2
F2489S. 826(1)(fd) inserted (with effect in accordance with Sch. 8 para. 17(1)(b) of the amending Act) by Finance Act 2016 (c. 24), Sch. 8 para. 2(2)
F2490S. 826(1)(fe) inserted (with effect in accordance with Sch. 6 para. 21(1)(b) of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 6 para. 2(2)
F2491Words in s. 826(1) substituted (retrospectively) by Finance Act 1989 (c. 26), s. 180(6)(7)
F2492Words in s. 826(2) inserted (31.7.1998) by Finance Act 1998 (c. 36), Sch. 4 para. 1(1)
F2493Words in s. 826(2) substituted (with effect in accordance with s. 199(2) of the amending Act) by Finance Act 1994 (c. 9), Sch. 19 para. 42; S.I. 1998/3173, art. 2
F2494S. 826(2A) inserted (3.5.1994) by Finance Act 1994 (c. 9), Sch. 16 para. 20(3)
F2495S. 826(2A) repealed (with effect in accordance with Sch. 3 para. 38(5) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 38(2), Sch. 27 Pt. 3(2), Note
F2496Words in s. 826(3) omitted (with effect in accordance with Sch. 1 para. 73 of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(6)(b)(i)
F2497Words in s. 826(3) substituted (with effect in accordance with Sch. 4 para. 2(2) of the amending Act) by Finance Act 1998 (c. 36), Sch. 4 para. 2(1)
F2498Words in s. 826(3) omitted (with effect in accordance with Sch. 1 para. 73 of the repealing Act) by virtue of Finance Act 2016 (c. 24), Sch. 1 para. 52(6)(b)(ii)
F2499S. 826(3A) inserted (with effect in accordance with s. 69(1) of the amending Act) by Finance Act 2000 (c. 17), Sch. 21 para. 1(3)
F2500S. 826(3AA) inserted (with effect in accordance with Sch. 14 para. 5 of the amending Act) by Finance Act 2002 (c. 23), Sch. 14 para. 1(3)
F2501S. 826(3AA) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(3), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2502S. 826(3B) inserted (with effect in accordance with s. 70(1) of the amending Act) by Finance Act 2001 (c. 9), Sch. 23 para. 3(3)
F2503S. 826(3C) inserted (1.1.2007) by Finance Act 2006 (c. 25), s. 53(1), Sch. 5 para. 26(3); S.I. 2006/3399, art. 2
F2504Words in s. 826(3C) inserted (19.7.2013 for specified purposes and 1.4.2014 for remaining purposes, and with effect in accordance with Sch. 18 para. 23 of the amending Act and S.I. 2014/1962, art. 2(2)) by Finance Act 2013 (c. 29), Sch. 18 paras. 1(3), 22; S.I. 2013/1817, art. 2(2); S.I. 2014/1962, art. 2(3)
F2505Words in s. 826(3C) substituted (22.8.2014 with effect in accordance with Sch. 4 para. 17 of the amending Act) by Finance Act 2014 (c. 26), Sch. 4 paras. 2(3), 16; S.I. 2014/2228, art. 2
F2506Words in s. 826(3C) substituted (with effect in accordance with Sch. 8 para. 17(1)(b) of the amending Act) by Finance Act 2016 (c. 24), Sch. 8 para. 2(3)
F2507Words in s. 826(3C) substituted (with effect in accordance with Sch. 6 para. 21(1)(b) of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 6 para. 2(3)
F2508S. 826(3D) inserted (with effect in accordance with Sch. 25 para. 9 of the amending Act) by Finance Act 2008 (c. 9), Sch. 25 para. 7(3)
F2509Words in s. 826(4) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(2)(a) (with Sch. 2)
F2510Words in s. 826(4) substituted (with effect in accordance with s. 90(2) of the amending Act) by Finance Act 1999 (c. 16), s. 90(1)(a)
F2511Words in s. 826(4) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(2)(b) (with Sch. 2)
F2512S. 826(4)(a) substituted (with effect in accordance with s. 173(6) of the amending Act) by Finance Act 1996 (c. 8), s. 173(5)
F2513Words in s. 826(4)(a)(i) inserted (with effect in accordance with s. 90(2) of the amending Act) by Finance Act 1999 (c. 16), s. 90(1)(b)
F2514Words in s. 826(4)(a)(i) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(2)(c) (with Sch. 2)
F2515S. 826(5)(5A) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(4), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2516S. 826(5A) inserted (with effect in accordance with s. 34(5) of the amending Act) by Finance Act 1998 (c. 36), s. 34(4)
F2517S. 826(7) repealed (with effect in accordance with Sch. 3 para. 38(6) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 38(3), Sch. 27 Pt. 3(2), Note
F2518S. 826(7A)(7B) inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 73(3)(4)(5), Sch. 15 para. 23
F2519S. 826(7AA) inserted (27.7.1993) by 1993 c. 34, s. 120, Sch. 14 para. 10(3)(5)
F2520Words in s. 826(7A)(b) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(3)(a)(i) (with Sch. 2)
F2521Words in s. 826(7A)(b) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(3)(a)(ii) (with Sch. 2)
F2522Words in s. 826(7A)(b) inserted (with effect in accordance with s. 111(3) of the amending Act) by Finance Act 2008 (c. 9), Sch. 35 para. 7
F2523Words in s. 826(7A)(b) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(3)(a)(iii) (with Sch. 2)
F2524Words in s. 826(7A) substituted (27.7.1993) by 1993 c. 34, s. 120, Sch. 14 para. 10(2)
F2525Words in s. 826(7A) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 117(3)(b) (with Sch. 2)
F2526Words in s. 826(7)(7A)(7B)(7C) substituted (with effect in accordance with Sch. 4 para. 5(5)(6) of the amending Act) by Finance Act 1998 (c. 36), Sch. 4 para. 5(2)
F2527S. 826(7AA)(7CA) repealed (with effect in accordance with Sch. 3 para. 38(7) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 38(4), Sch. 27 Pt. 3(2), Note
F2528S. 826(7AA) inserted (with effect in accordance with Sch. 4 paras. 190-192 of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 4 para. 106(2) (with Sch. 4 para. 194)
F2529S. 826(7B) repealed (with effect in accordance with s. 20 of the repealing Act) by Finance (No. 2) Act 1997 (c. 58), Sch. 8 Pt. 2(4), Note
F2530S. 826(7BB)(7BC) inserted (28.7.2000) by Finance Act 2000 (c. 17), Sch. 30 para. 29(2)
F2531S. 826(7BC) omitted (with effect in accordance with Sch. 14 para. 31 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 14 para. 10
F2532S. 826(7C) inserted (27.7.1993) by 1993 c. 34, s. 170, Sch. 18 para.5
F2533Words in s. 826(7C)(a) substituted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 48(1)(a) (with Sch. 15)
F2534Words in s. 826(7C)(b) substituted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 48(1)(b) (with Sch. 15)
F2535Words in s. 826(7C)(b) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(5)(a) (with Sch. 2 Pts. 1, 2)
F2536Words in s. 826(7C)(c) inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 24 para. 11(a)
F2537Words in s. 826(7C) substituted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 24 para. 11(b)
F2538Words in s. 826(7C) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(5)(b) (with Sch. 2 Pts. 1, 2)
F2539S. 826(7AA)(7CA) repealed (with effect in accordance with Sch. 3 para. 38(7) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 38(4), Sch. 27 Pt. 3(2), Note
F2540S. 826(7CA) inserted (with effect in accordance with Sch. 24 para. 12(4)(5) of the amending Act) by Finance Act 1995 (c. 4), Sch. 24 para. 12(2)
F2541S. 826(7D) inserted (with effect in accordance with Sch. 4 para. 5(5)(6) of the amending Act) by Finance Act 1998 (c. 36), Sch. 4 para. 5(3)
F2542Words in s. 826(7D) inserted (with effect in accordance with Sch. 4 paras. 190-192 of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 4 para. 106(3) (with Sch. 4 para. 194)
F2543Words in s. 826(7D) inserted (28.7.2000) by Finance Act 2000 (c. 17), Sch. 30 para. 29(3)
F2544S. 826(7E) inserted (with effect in accordance with Sch. 4 para. 5(5)(6) of the amending Act) by Finance Act 1998 (c. 36), Sch. 4 para. 5(4)
F2545Words in s. 826(7E) inserted (with effect in accordance with Sch. 4 paras. 190-192 of the amending Act) by virtue of Finance (No. 2) Act 2017 (c. 32), Sch. 4 para. 106(4) (with Sch. 4 para. 194)
F2546Words in s. 826(7E) inserted (28.7.2000) by virtue of Finance Act 2000 (c. 17), Sch. 30 para. 29(4)
F2547S. 826(8A)-(8C) inserted (with effect in accordance with Sch. 4 para. 3(3) of the amending Act) by Finance Act 1998 (c. 36), Sch. 4 para. 3(1)
F2548Words in s. 826(8A)(a) inserted (with effect in accordance with s. 69(1) of the amending Act) by Finance Act 2000 (c. 17), Sch. 21 para. 1(4)(a)
F2549Word in s. 826(8A)(a) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(6)(a) (with Sch. 2 Pts. 1, 2)
F2550Words in s. 826(8A)(a) inserted (with effect in accordance with s. 70(1) of the amending Act) by Finance Act 2001 (c. 9), Sch. 23 para. 3(4)(a)
F2551Words in s. 826(8A)(a) substituted (1.1.2007) by Finance Act 2006 (c. 25), s. 53(1), Sch. 5 para. 26(4)(a); S.I. 2006/3399, art. 2
F2552Words in s. 826(8A)(a) substituted (22.8.2014 with effect in accordance with Sch. 4 para. 17 of the amending Act) by Finance Act 2014 (c. 26), Sch. 4 paras. 2(4)(a), 16; S.I. 2014/2228, art. 2
F2553Words in s. 826(8A)(a) substituted (with effect in accordance with Sch. 8 para. 17(1)(b) of the amending Act) by Finance Act 2016 (c. 24), Sch. 8 para. 2(4)(a)
F2554Words in s. 826(8A)(a) substituted (with effect in accordance with Sch. 6 para. 21(1)(b) of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 6 para. 2(4)(a)
F2555S. 826(8A)(b) substituted (with effect in accordance with s. 69(1) of the amending Act) by Finance Act 2000 (c. 17), Sch. 21 para. 1(4)(b)
F2556Words in s. 826(8A)(b)(ii) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(6)(b), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2557Words in s. 826(8A)(b)(ii) inserted (with effect in accordance with Sch. 14 para. 5 of the amending Act) by Finance Act 2002 (c. 23), Sch. 14 para. 1(4)(b)
F2558Words in s. 826(8A)(b)(ii) inserted (with effect in accordance with s. 70(1) of the amending Act) by Finance Act 2001 (c. 9), Sch. 23 para. 3(4)(b)
F2559Words in s. 826(8A)(b)(ii) inserted (1.1.2007) by Finance Act 2006 (c. 25), s. 53(1), Sch. 5 para. 26(4)(b); S.I. 2006/3399, art. 2
F2560Words in s. 826(8A)(b)(ii) inserted (19.7.2013 for specified purposes and 1.4.2014 for remaining purposes, and with effect in accordance with Sch. 18 para. 23 of the amending Act and S.I. 2014/1962, art. 2(2)) by Finance Act 2013 (c. 29), Sch. 18 paras. 1(4), 22; S.I. 2013/1817, art. 2(2); S.I. 2014/1962, art. 2(3)
F2561Words in s. 826(8A)(b)(ii) inserted (22.8.2014 with effect in accordance with Sch. 4 para. 17 of the amending Act) by Finance Act 2014 (c. 26), Sch. 4 paras. 2(4)(b), 16; S.I. 2014/2228, art. 2
F2562Words in s. 826(8A)(b)(ii) inserted (with effect in accordance with Sch. 8 para. 17(1)(b) of the amending Act) by Finance Act 2016 (c. 24), Sch. 8 para. 2(4)(b)
F2563Words in s. 826(8A)(b)(ii) inserted (with effect in accordance with Sch. 6 para. 21(1)(b) of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 6 para. 2(4)(b)
F2564Words in s. 826(8A)(b)(ii) inserted (with effect in accordance with Sch. 25 para. 9 of the amending Act) by Finance Act 2008 (c. 9), Sch. 25 para. 7(4)
F2565S. 826(8BA) inserted (with effect in accordance with s. 69(1) of the amending Act) by Finance Act 2000 (c. 17), Sch. 21 para. 1(5)
F2566Words in s. 826(8BA) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 267(7), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2567Words in s. 826(8BA) inserted (with effect in accordance with Sch. 14 para. 5 of the amending Act) by Finance Act 2002 (c. 23), Sch. 14 para. 1(5)
F2568Words in s. 826(8BA) inserted (with effect in accordance with s. 70(1) of the amending Act) by Finance Act 2001 (c. 9), Sch. 23 para. 3(5)(a)
F2569Words in s. 826(8BA) inserted (1.1.2007) by virtue of Finance Act 2006 (c. 25), s. 53(1), Sch. 5 para. 26(5); S.I. 2006/3399, art. 2
F2570Words in s. 826(8BA) inserted (19.7.2013 for specified purposes and 1.4.2014 for remaining purposes, and with effect in accordance with Sch. 18 para. 23 of the amending Act and S.I. 2014/1962, art. 2(2)) by Finance Act 2013 (c. 29), Sch. 18 paras. 1(5), 22; S.I. 2013/1817, art. 2(2); S.I. 2014/1962, art. 2(3)
F2571Words in s. 826(8BA) inserted (22.8.2014 with effect in accordance with Sch. 4 para. 17 of the amending Act) by Finance Act 2014 (c. 26), Sch. 4 paras. 2(5), 16; S.I. 2014/2228, art. 2
F2572Words in s. 826(8BA) inserted (with effect in accordance with Sch. 8 para. 17(1)(b) of the amending Act) by Finance Act 2016 (c. 24), Sch. 8 para. 2(5)
F2573Words in s. 826(8BA) inserted (with effect in accordance with Sch. 6 para. 21(1)(b) of the amending Act) by Finance (No. 2) Act 2017 (c. 32), Sch. 6 para. 2(5)
F2574Words in s. 826(8BA) inserted (with effect in accordance with Sch. 25 para. 9 of the amending Act) by Finance Act 2008 (c. 9), Sch. 25 para. 7(5)
F2575Words in s. 826(8BA) inserted (with effect in accordance with s. 70(1) of the amending Act) by Finance Act 2001 (c. 9), Sch. 23 para. 3(5)(b)
Modifications etc. (not altering text)
C83S. 826 excluded (2.1.1996) by The Lloyd's Underwriters (Gilt-edged Securities) (Periodic Accounting for Tax on Interest) Regulations 1995 (S.I. 1995/3225), reg. 12(2) (with reg. 13)
C84S. 826 applied (with modifications) (7.1.1999 in accordance with reg. 1(2) of the affecting S.I.) by The Corporation Tax (Instalment Payments) Regulations 1998 (S.I. 1998/3175), reg. 8 (as amended by: S.I. 2005/889, regs. 1(1)(3), 7; S.I. 2011/1785, regs. 1, 11; S.I. 2017/1072, regs. 1, 10)
C85S. 826 excluded (27.12.2005 with effect in accordance with reg. 1(2) of the affecting S.I.) by The Lloyd's Underwriters (Tax) Regulations 2005 (S.I. 2005/3338), regs. 1(1), 14(4)(6)(b)
Marginal Citations
M100Source—1987 (No.2) s.87
[F2576826A Interest on payments in respect of corporation tax and meaning of “the material date".U.K.
(1)The Treasury may by regulations make provision applying section 826, with such modifications as may be prescribed, for the purpose of conferring on companies of such descriptions as may be prescribed a right to interest—
(a)on such payments made by them in respect of corporation tax as may be prescribed,
(b)at the rate applicable under section 178 of the M102Finance Act 1989, and
(c)for such period as may be prescribed,
and for treating any such interest for the purposes, or prescribed purposes, of the Tax Acts as interest under section 826(1)(a) on a repayment of corporation tax.
(2)The Treasury may by regulations make provision modifying section 826(2) in relation to companies of such description as may be prescribed.
(3)Subsections (1) and (2) above do not apply in relation to companies in relation to which section 826(2) is modified or otherwise affected by regulations under section 59E of the Management Act (alteration of date on which corporation tax becomes due and payable) in relation to the accounting period to which the corporation tax in question relates.
(4)Where the Treasury make regulations under subsection (2) above in relation to companies of any description, they may also make regulations modifying section 59DA(2) of the Management Act in relation to those companies, or any description of such companies, by varying the date before which the claim there mentioned may not be made.
(5)Regulations under this section—
(a)may make different provision in relation to different cases or circumstances or in relation to companies or accounting periods of different descriptions;
(b)may make such supplementary, incidental, consequential or transitional provision as appears to the Treasury to be necessary or expedient.
(6)Regulations under this section may not make provision in relation to accounting periods ending before the day appointed under section 199 of the M103Finance Act 1994 for the purposes of Chapter III of Part IV of that Act (corporation tax self-assessment).
(7)In this section “prescribed” means prescribed by regulations made under this section.]
Textual Amendments
F2576S. 826A inserted (31.7.1998) by Finance Act 1998 (c. 36), Sch. 4 para. 1(2)
Marginal Citations
827 VAT penalties etc.U.K.
F2577. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2577S. 827 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 268, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
[F2578827ATerritorial scope of charges under certain provisions to which section 836B appliesU.K.
F2579. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2578S. 827A inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 333 (with Sch. 2)
F2579S. 827A repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 207, Sch. 3 Pt. 1 (with Sch. 2)
828 Orders and regulations made by the Treasury or the Board.U.K.
(1)M104F2580. . . Any power of the Treasury or the Board to make any order or regulations under this Act F2581. . . shall be exercisable by statutory instrument.
(2)F2582. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)M105Subject to [F2583subsection (4)] below and to any other provision to the contrary, any statutory instrument containing any order or regulations made by the Treasury or the Board F2584. . . shall be subject to annulment in pursuance of a resolution of the House of Commons.
(4)Subsection (3) above shall not apply in relation to an order or regulations made under section F2585. . . [F2586F2587. . . ]F2588. . . F2589. . . F2590. . . F2591. . . [F2592F2588. . . ][F2593590C(6)]. . . [F2594F2595. . . F2596. . . ] or paragraph 7 of Schedule 14 [F2597F2598. . . ] or—
(a)if any other Parliamentary procedure is expressly provided;
(b)if the order in question is an order appointing a day for the purposes of any provision of the Tax Acts, being a day as from which the provision will have effect, with or without amendments, or will cease to have effect.
[F2599(5)F2600. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F2601(6)F2600. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2580Words in s. 828(1) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(2)(a), Sch. 3 Pt. 1 (with Sch. 2)
F2581Words in s. 828(1) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(2)(b), Sch. 3 Pt. 1 (with Sch. 2)
F2582S. 828(2) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(3), Sch. 3 Pt. 1 (with Sch. 2)
F2583Words in s. 828(3) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(4)(a) (with Sch. 2)
F2584Words in s. 828(3) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(4)(b), Sch. 3 Pt. 1 (with Sch. 2)
F2585Words in s. 828(4) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 208(5)(a), Sch. 3 Pt. 1 (with Sch. 2)
F2586Words in s. 828(4) inserted (10.7.2003) by Finance Act 2003 (c. 14), s. 180(2)
F2587Words in s. 828(4) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 269(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2588Words in s. 828(4) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 208(5)(b), Sch. 3 Pt. 1 (with Sch. 2)
F2589Words in s. 828(4) repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 334(2), Sch. 3 (with Sch. 2)
F2590Words in s. 828(4) repealed (3.5.1994) by Finance Act 1994 (c. 9), Sch. 26 Pt. 5(19)
F2591Words in s. 828(4) repealed (with effect in accordance with Sch. 20 Pt. 3(7) Note 4 of the repealing Act) by Finance Act 1999 (c. 16), Sch. 20 Pt. 3(7)
F2592Words in s. 828(4) inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 118(2)
F2593Words in s. 828(4) inserted by Finance Act 1989 (c. 26), Sch. 6 para. 16
F2594Words in s. 828(4) substituted (29.4.1996) by Finance Act 1996 (c. 8), Sch. 37 para. 1(2)
F2595Words in s. 828(4) repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 33, Sch. 10 Pt. 1 (with Sch. 9)
F2596Words in s. 828(4) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(5), Sch. 3 Pt. 1 (with Sch. 2)
F2597Words in s. 828(4) inserted by Capital Allowances Act 1990 (c. 1), Sch. 1 para. 8(34)
F2598Words in s. 828(4) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 208(5)(c), Sch. 3 Pt. 1 (with Sch. 2)
F2599S. 828(5) added (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 105(4) (with Sch. 7)
F2600S. 828(5)(6) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 118(6), Sch. 3 Pt. 1 (with Sch. 2)
F2601S. 828(6) inserted (6.4.2006) by Finance Act 2004 (c. 12), s. 284(1), Sch. 35 para. 34 (with Sch. 36)
Modifications etc. (not altering text)
C86S. 828 excluded (18.3.2010) by Taxation (International and Other Provisions) Act 2010 (c. 8), ss. 372(4), 381(2)(a) (with Sch. 9)
C87S. 828(3) excluded by Finance Act 2000 (c. 17), Sch. 22 para. 22C(3) (as inserted (1.7.2005) by Finance Act 2005 (c. 7), Sch. 7 paras. 8, 18(1) (with Sch. 7 paras. 19-21))
C88S. 828(3) excluded (21.7.2009) by Finance Act 2009 (c. 10), Sch. 22 para. 14(2)
C89S. 828(4) modified (20.3.2007) by Income Tax Act 2007 (c. 3), ss. 1030(4), 1034(4)(b)
Marginal Citations
M104Source—1970 ss.65(5), 204, 231(3), 343 (1A); 1970(F) s.29(6), Sch.5 2(3), 10; 1972 ss.91(3), 108(4); 1973 Sch.16 17(2); 1975 (No.2) ss.47(10), 48(6), 69(9), 70(8), 70A(3); 1976 ss.64(4), 64A, (4) Sch.4 16(2); 1980 s.24(9); Sch.10 13(3); 1982 ss.28(5), 29(1), (3), Sch.7 14(2); 1984 ss.26(1), 88(8), 126(1), Sch.8 2(1)(f), 3A; 1983 Sch.5 5A(9), 6(8); 1986 s.28, 61, Sch.11 11, Sch.12 3, Sch.17 6(7).
M105Source—1970 ss.65(5), 204, 343(1B); 1970(F) s.29(8), Sch.5 2(3), 10; 1973 Sch.16 17(2); 1975 (No.2) ss.47(10), 48(6), 69(9), 70(8), 70A(3); 1976 ss.64(4), 64A(4); 1982 s.29(5); 1983 Sch.5 5A(9), 6(9); 1984 ss.26(6), 88(8), Sch.8 2(1), 3A; 1986 ss.26, 27(7), 55, Sch.11 11, Sch.12 3, Sch.17 6(7)
829 Application of Income Tax Acts to public departments and avoidance of exempting provisions.U.K.
F2602. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2602S. 829 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 209, Sch. 3 Pt. 1 (with Sch. 2)
830 Territorial sea F2603. . . .U.K.
(1)F2604. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)F2605. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)F2605. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)F2605. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)F2606. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2603Words in s. 830 title omitted (1.4.2009 with effect in accordance with art. 1(2) of the repealing S.I.) by virtue of The Corporation Tax Act 2009 (Amendment) Order 2009 (S.I. 2009/2860), arts. 1, 3(4)(b)
F2604S. 830(1) repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 119, Sch. 3 Pt. 1 (with Sch. 2)
F2605S. 830(2)-(4) repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 270, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2606S. 830(5) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 106, Sch. 8 Pt. 1 (with Sch. 7)
InterpretationU.K.
831 Interpretation of this Act.U.K.
(1)M106In this Act, except so far as the context otherwise requires—
(a)“the Corporation Tax Acts” means the enactments relating to the taxation of the income and chargeable gains of companies and of company distributions (including provisions relating also to income tax); and
(b)“the Income Tax Acts” means the enactments relating to income tax, including any provisions of the Corporation Tax Acts which relate to income tax.
(2)In this Act “the Tax Acts”, except so far as the context otherwise requires, means this Act and all other provisions of the Income Tax Acts and the Corporation Tax Acts.
(3)In this Act—
[F2607“CTA 2009” means the Corporation Tax Act 2009;]
[F2608“CTA 2010” means the Corporation Tax Act 2010;]
[F2609“ITEPA 2003” means the Income Tax (Earnings and Pensions) Act 2003;]
[F2610“ITTOIA 2005” means the Income Tax (Trading and Other Income) Act 2005;]
[F2611“ITA 2007” means the Income Tax Act 2007;]
“the Management Act” means the Taxes Management Act 1970;
[F2612“TIOPA 2010” means the Taxation (International and Other Provisions) Act 2010;]
“the 1968 Act” means the Capital Allowances Act 1968;
“the 1970 Act” means the Income and Corporation Taxes Act 1970; and
“the 1979 Act” means the Capital Gains Tax Act 1979.
[F2613“the 1990 Act” means the Capital Allowances Act 1990.]
[F2614“the 1992 Act” means the Taxation of Chargeable Gains Act 1992.]
(4)Section 1 of the M107Family Law Reform Act 1987, the paragraph inserted in Schedule 1 to the M108Interpretation Act 1978 by paragraph 73 of Schedule 2 to that Act and section 1(3) of the M109Law Reform (Parent and Child) (Scotland) Act 1986 (legal equality of illegitimate children) shall be disregarded in construing references in this Act to a child or to children (however expressed).
(5)M110This Act, so far as it relates to capital gains tax, shall be construed as one with the [F26151992] Act.
(6)Any reference in this Act to a section, Part or Schedule is a reference to that section, Part or Schedule of or to this Act, unless the context otherwise requires.
Textual Amendments
F2607S. 831(3): definition of "CTA 2009" inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 271 (with Sch. 2 Pts. 1, 2)
F2608S. 831(3): definition of "CTA 2010" inserted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 120 (with Sch. 2)
F2609S. 831(3): definition of "ITEPA 2003" inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 107 (with Sch. 7)
F2610S. 831(3): definition of "ITTOIA 2005" inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 336 (with Sch. 2)
F2611S. 831(3): definition of "ITA 2007" inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 211 (with Sch. 2)
F2612S. 831(3): definition of "TIOPA 2010" inserted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 316 (with Sch. 9)
F2613S. 831(3): definition of "the 1990 Act" inserted by Capital Allowances Act 1990 (c. 1), Sch. 1 para. 8(35); and that amendment continued by Capital Allowances Act 2001 (c. 2), s. 579, Sch. 2 para. 59
F2614S. 831(3): definition of "the 1992 Act" inserted (with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(53)(a) (with ss. 60, 101(1), 171, 201(3))
F2615Words in s. 831(5) substituted (with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(53)(b) (with ss. 60, 101(1), 171, 201(3))
Modifications etc. (not altering text)
C90S. 831(4) applied (28.7.2000) by Finance Act 2000 (c. 17), Sch. 22 para. 144(2)
Marginal Citations
M106Source—1970 s.526(1), (2); 1987 Sch.15 12
M110Source—1970 s.540(2)
832 Interpretation of the [F2616Corporation Tax Acts etc].U.K.
F2617. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2616Words in s. 832 sidenote substituted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 212(6) (with Sch. 2)
F2617S. 832 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 121, Sch. 3 Pt. 1 (with Sch. 2)
833 Interpretation of Income Tax Acts.U.K.
F2618. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2618S. 833 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 213, Sch. 3 Pt. 1 (with Sch. 2)
834 Interpretation of the Corporation Tax Acts.U.K.
F2619. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2619S. 834 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 122, Sch. 3 Pt. 1 (with Sch. 2)
[F2620834AMiscellaneous charges (list for the purposes of certain provisions that formerly referred to Case VI of Schedule D)U.K.
F2621. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2620S. 834A inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 274 (with Sch. 2 Pts. 1, 2)
F2621S. 834A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 123, Sch. 3 Pt. 1 (with Sch. 2)
[F2622834BMeaning of “UK property business” and “overseas property business”U.K.
F2623. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2622S. 834B inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 275 (with Sch. 2 Pts. 1, 2)
F2623S. 834B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 124, Sch. 3 Pt. 1 (with Sch. 2)
[F2624834CTotal profitsU.K.
F2625. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2624S. 834C inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 276 (with Sch. 2 Pts. 1, 2)
F2625S. 834C repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 125, Sch. 3 Pt. 1 (with Sch. 2)
835“Total income” in the Income Tax Acts.U.K.
F2626. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2626S. 835 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 215, Sch. 3 Pt. 1 (with Sch. 2)
836 Returns of total income.U.K.
F2627. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2627S. 836 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 216, Sch. 3 Pt. 1 (with Sch. 2)
[F2628836A Generally accepted accounting practiceU.K.
F2629. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2628S. 836A inserted (with effect in accordance with s. 103(6) of the amending Act) by Finance Act 2002 (c. 23), s. 103(2)
F2629S. 836A repealed (with effect in accordance with s. 80(4) of the repealing Act) by Finance Act 2005 (c. 7), Sch. 4 para. 25, Sch. 11 Pt. 2(7), Note 2
[F2630836BTable of provisions to which this section appliesU.K.
F2631. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2630S. 836B inserted (6.4.2005 with effect in accordance with s. 883(1) of the amending Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 340 (with Sch. 2)
F2631S. 836B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 217, Sch. 3 Pt. 1 (with Sch. 2)
837“Annual value” of land.U.K.
F2632. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2632S. 837 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 218, Sch. 3 Pt. 1 (with Sch. 2)
[F2633837A Meaning of “research and development”.U.K.
F2634. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2633S. 837A inserted (28.7.2000) by Finance Act 2000 (c. 17), Sch. 19 para. 1
F2634S. 837A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 126, Sch. 3 Pt. 1 (with Sch. 2)
[F2635837B Meaning of “oil and gas exploration and appraisal”.U.K.
F2636. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2635S. 837B inserted (28.7.2000) by Finance Act 2000 (c. 17), Sch. 19 para. 2
F2636S. 837B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 127, Sch. 3 Pt. 1 (with Sch. 2)
[F2637837CMeaning of “offshore installation”U.K.
F2638. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2637S. 837C inserted (with effect in accordance with Sch. 27 para. 3 of the amending Act) by Finance Act 2004 (c. 12), Sch. 27 para. 1
F2638S. 837C repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 128, Sch. 3 Pt. 1 (with Sch. 2)
838 Subsidiaries.U.K.
F2639. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2639S. 838 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 129, Sch. 3 Pt. 1 (with Sch. 2)
839 Connected persons.U.K.
F2640. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2640S. 839 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 130, Sch. 3 Pt. 1 (with Sch. 2)
840 Meaning of “control” in certain contexts.U.K.
F2641. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2641S. 840 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 131, Sch. 3 Pt. 1 (with Sch. 2)
[F2642840ZAMeaning of “tax advantage”U.K.
F2643. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2642S. 840ZA inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 225 (with Sch. 2)
F2643S. 840ZA repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 132, Sch. 3 Pt. 1 (with Sch. 2)
[F2644840A Banks.U.K.
F2645. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2644S. 840A inserted (29.4.1996) by Finance Act 1996 (c. 8), Sch. 37 para. 1(1)
F2645S. 840A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 133, Sch. 3 Pt. 1 (with Sch. 2)
841Meaning of “recognised stock exchange” etcU.K.
F2646. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2646S. 841 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 134, Sch. 3 Pt. 1 (with Sch. 2)
[F2647841A Recognised clearing systems.U.K.
F2648. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2647S. 841A inserted (with effect in accordance with Sch. 7 para. 32 of the amending Act) by Finance Act 1996 (c. 8), Sch. 7 para. 26 (with Sch. 7 paras. 33-35)
F2648S. 841A repealed (28.7.2000) by Finance Act 2000 (c. 17), Sch. 40 Pt. 2(17)
842 Investment trusts.U.K.
F2649. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2649S. 842 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 135, Sch. 3 Pt. 1 (with Sch. 2)
[F2650842AA Venture capital trusts.U.K.
F2651. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2650S. 842AA inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 70(1)
F2651S. 842AA repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 229, Sch. 3 Pt. 1 (with Sch. 2)
[F2652842A Local authorities.U.K.
F2653. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2652S. 842A inserted (1.4.1990) by Finance Act 1990 (c. 29), s.127(1)(4)
F2653S. 842A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 136, Sch. 3 Pt. 1 (with Sch. 2)
[F2654842B Meaning of F2655. . . “property investment LLP”U.K.
F2656. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F2654S. 842B inserted (6.4.2001 with effect in accordance with s. 76(1) of the amending Act) by Finance Act 2001 (c. 9), s. 76(2), Sch. 25 para. 1(1)
F2655Words in s. 842B sidenote repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 231(4), Sch. 3 Pt. 1 (with Sch. 2)
F2656S. 842B repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 137, Sch. 3 Pt. 1 (with Sch. 2)
Commencement, savings, repeals etc.U.K.
843 Commencement.U.K.
(1)Except as otherwise provided by the following provisions of this section, this Act shall come into force in relation to tax for the year 1988-89 and subsequent years of assessment, and for companies’ accounting periods ending after 5th April 1988.
(2)Except as otherwise provided by the following provisions of this section, such of the provisions of this Act as relate to capital gains tax (including the provisions of Part XVIII as applied to capital gains tax by section [F2657277 of [F2658the 1992 Act]]) shall come into force in relation to that tax for the year 1988-89 and subsequent years of assessment.
(3)The following provisions of this Act, that is to say—
(a)so much of any provision as authorises the making of any Order in Council or regulations or other instrument;
(b)so much of any provision as relates to the making of a return, the furnishing of a certificate or the giving of any other information, including any such provision which imposes a duty on the Board or an officer of the Board as well as any such provision which imposes a duty on any other person;
(c)so much of any provision as imposes any penalty;
(d)except where the tax concerned is all tax for years of assessment before the year 1988-89 or accounting periods ending before 6th April 1988, so much of any other provision as confers any power or imposes any duty the exercise or performance of which operates or may operate in relation to tax for more than one chargeable period,
shall come into force for all purposes on 6th April 1988 to the exclusion of the corresponding enactments repealed by this Act.
(4)This section has effect except as otherwise provided by any other provision of this Act, and in particular except as provided by sections 96, 380 to 384, 393, F2659 . . ., 400, 703 F2660. . . .
Textual Amendments
F2657Words in s. 843(2) substituted (with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(56) (with ss. 60, 101(1), 171, 201(3))
F2658Words in s. 843(2) substituted (retrospectively) by Finance Act 1994 (c. 9), Sch. 17 para. 8
F2659Words in s. 843(4) repealed by Finance Act 1991 (c. 31, SIF 63:1), ss. 73(3)(4)(5), 123, Sch. 15 para. 24, Sch. 19 Pt. V, Note 4
F2660Words in s. 843(4) repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1, Note
844 Savings, transitional provisions, consequential amendments and repeals.U.K.
(1)Schedule 29, which makes amendments to other enactments consequential on the passing of this Act, shall have effect.
(2)Schedule 29, section 843 and this section are without prejudice to the provisions of the M111Interpretation Act 1978 as respects the effect of repeals.
(3)Schedule 30 which contains savings and transitional provisions shall have effect.
(4)The enactments mentioned in Schedule 31 are hereby repealed to the extent specified in the third column of that Schedule.
(5)Subject to subsection (6) below, section 843(3), Schedule 30 and to any other provision of this Act by which any provision is brought into force to the exclusion of the corresponding enactments repealed by this Act, those repeals shall come into force in accordance with subsections (1) and (2) of section 843.
(6)No provision mentioned in subsection (5) above shall be taken as bringing a repeal into force except to the extent that the repealed enactment is being superseded.
Marginal Citations
845 Short title.U.K.
This Act may be cited as the Income and Corporation Taxes Act 1988.
SCHEDULES
F2661F2661[F2662SCHEDULE A1U.K.Determination of profits attributable to permanent establishment: supplementary provisions]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2661Sch. A1 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 278, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2663F2663[F2664SCHEDULE A2U.K.Corporation tax: the non-corporate distribution rate: supplementary provisions]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2663Sch. A2 repealed (with effect in accordance with s. 26(8)-(11) of the repealing Act) by Finance Act 2006 (c. 25), s. 26(2), Sch. 26 Pt. 3(1), Note
F2664Sch. A2 inserted (with effect in accordance with s. 28(4)(5) of the amending Act) by Finance Act 2004 (c. 12), s. 28(2)(6), Sch. 3
F2665F2665SCHEDULE 1U.K.
Textual Amendments
F2665Sch. 1 repealed (with effect in accordance with s. 38(2)(3) of the repealing Act) by Finance Act 1998 (c. 36), s. 165, Sch. 27 Pt. 3(4), Note
Expenditure before 1964-65: deductions from rentsU.K.
1(1)M112Except as provided by sub-paragraphs (2) and (3) below, no payment shall be deductible under sections 25 and 26 if made before the beginning of the year 1964-65.
(2)Where, by virtue of paragraph 1(2) of Schedule 2 to the 1970 Act, any amount fell to be treated as a payment in relation to premises made by a person in the year 1964-65 in respect of dilapidation attributable to that year, the amount shall be similarly treated for the purposes of sections 25 and 26.
(3)If the amount of any loss was treated, by virtue of paragraph 1(3) of that Schedule, as if it were a payment such as is mentioned in section 72(1) of the 1970 Act made by any person in respect of any premises in and in respect of any year, it shall be treated for the purposes of sections 25 and 26 as if it were a payment such as is mentioned in section 25(1) made by that person in respect of those premises in and in respect of that year.
(4)A deduction falling to be made by virtue of sub-paragraph (3) above shall be made notwithstanding anything in sections 392(3) and 396(1); and relief shall not be given under either of those sections in respect of the loss in so far as a deduction in respect of it is given under this paragraph.
Expenditure before 1964-65: deductions from other receiptsU.K.
2(1)Subject to sub-paragraph (2) below, no payment shall be deductible under section 28 if made before the beginning of the year 1964-65.
(2)Sub-paragraph (1) above shall not prevent the deduction of a payment in so far as a loss in respect thereof was carried forward to the year 1964-65 by virtue of section 346 of the M113Income Tax Act 1952 (Case VI losses).
(3)Paragraph 1(4) above shall apply in the case of a deduction falling to made by virtue of sub-paragraph (2) above as it applies in the case of one falling to be made by virtue of paragraph 1(3) above.
Expenditure on sea walls before 1964-65U.K.
3(1)Section 30 shall not apply in relation to expenditure incurred before the beginning of the year 1964-65 except in accordance with sub-paragraphs (2) and (3) below.
(2)Subject to sub-paragraph (3) below, section 30 shall apply in relation to expenditure which, by virtue of paragraph 3(1) of Schedule 2 to the 1970 Act, was treated as if—
(a)it had been incurred in the year of assessment following that in which it was actually incurred, and
(b)in so far as it was incurred in repairing an embankment, it had been incurred in making it,
as if it had been incurred in that year and in making that embankment.
(3)If, by virtue of the proviso to paragraph 3(1) of Schedule 2 to the 1970 Act, any expenditure fell to be treated for the purposes of sections 71 to 77 of that Act as if it were an amount paid by any person in and in respect of the year 1964-65 in respect of the maintenance of premises preserved or protected by an embankment, it shall be similarly treated for the purposes of sections 25 to 31.
F2666F2666SCHEDULE 2U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2666Sch. 2 repealed (with effect in accordance with Sch. 14 Pt. IV Note 9 of the repealing Act) by Finance Act 1988 (c. 39) ss. 75, 148, Sch.14 Part IV
F2667F2667SCHEDULE 3U.K.
Textual Amendments
F2667Sch. 3 repealed (with effect in accordance with Sch. 7 para. 32 of the repealing Act) by Finance Act 1996 (c. 8), ss. 79, 205, Sch. 7 para. 27, Sch. 41 Pt. 5(2), Note (with Sch. 7 paras. 33-35)
PART IU.K. PUBLIC REVENUE DIVIDENDS ETC. PAYABLE TO THE BANK OF ENGLAND OR THE BANK OF IRELAND OR ENTRUSTED FOR PAYMENT TO THE BANK OF ENGLAND, THE BANK OF IRELAND OR THE NATIONAL DEBT COMMISSIONERS
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .2(1)In the case of dividends and profits attached thereto payable to the Bank of England out of the public revenue of the United Kingdom, the Bank of England shall set apart the income tax in respect of the amount payable to them.
(2)M115In the case of dividends and profits attached thereto entrusted to the Bank of England for payment and distribution, dividends payable by the Bank of Ireland at its principal office in Belfast, and dividends payable by the National Debt Commissioners or of which the National Debt Commissioners have the distribution—
(a)the Bank of England, the Bank of Ireland and the National Debt Commissioners respectively shall, before any payment is made by them, retain the amount of the income tax for the purposes of the Income Tax Acts, and
(b)the retaining of the amount shall be deemed to be a payment of the income tax by the persons entitled to the dividends, and shall be allowed by them on the receipt of the residue thereof, and
(c)the Bank of England, the Bank of Ireland and the National Debt Commissioners respectively shall be acquitted and discharged of a sum equal to the amount retained as though that sum had been actually paid.
(3)In relation to dividends payable to the Bank of Ireland out of the public revenue of the United Kingdom, and public revenue dividends which are entrusted to the Bank of Ireland for payment and distribution and are not payable by that Bank out of its principal office in Belfast, the following provisions shall have effect—
(a)the money which, apart from this sub-paragraph, would be issuable to the Bank of Ireland under section 14 of the M116National Debt Act 1870, or otherwise payable to the Bank of Ireland for the purpose of dividends on securities of the United Kingdom government entered in the register of the Bank of Ireland in Dublin, shall be issued and paid to the Bank of England; and
(b)the Bank of England shall set apart and retain out of moneys so issued and paid to them the amount of the income tax on the dividends payable to the Bank of Ireland, and on the dividends on the securities of the United Kingdom government entered in the register of the Bank of Ireland in Dublin; and
(c)the Bank of England shall pay to the Bank of Ireland the residue of moneys so issued and paid to them, to be applied by the Bank of Ireland to the payment of the dividends; and
(d)the retaining of the amount shall be deemed to be a payment of the income tax by the persons entitled to the dividends, and shall be allowed by them on the receipt of the residue thereof, and the Bank of England and the Bank of Ireland shall be acquitted and discharged of a sum equal to the amount retained as though that sum had been actually paid.
3Money set apart or retained under paragraph 2 above, and the amount of any tax charged on the trading profits of the Bank of England or the Bank of Ireland, shall be paid into the general account of the Board at the Bank of England or the Bank of Ireland.
4No deduction of income tax under this Part of this Schedule shall be made from any dividends payable in respect of stock, securities or annuities standing in the name of the official custodian for charities, nor from any dividends in respect of which there is given to the Bank of England a certificate from the Charity Commissioners that the dividends are subject only to charitable trusts and are exempt from tax.
PART IIU.K. PUBLIC REVENUE DIVIDENDS PAYABLE BY PUBLIC OFFICES AND DEPARTMENTS
5Where any payment is made of public revenue dividends payable by any public office or department of the Crown, the appropriate officer shall retain the income tax charged and pay the same into the general account of the Board at the Bank of England or the Bank of Ireland.
PART IIIU.K. OTHER PUBLIC REVENUE DIVIDENDS, FOREIGN DIVIDENDS AND PROCEEDS OF COUPONS
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IVU.K. INTEREST PAYABLE OUT OF THE PUBLIC REVENUE OF THE REPUBLIC OF IRELAND ETC.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2690F2690 SCHEDULE 4U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2690Sch. 4 repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 14 para. 50, Sch. 41 Pt. 5(3), Note (with Sch. 15)
F2718F2718[F2719SCHEDULE 4AA]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2718Sch. 4AA repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 279, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
F2719Sch. 4AA inserted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 109 (with Sch. 7)
F2724F2724[F2725SCHEDULE 4AU.K. CREATIVE ARTISTS: RELIEF FOR FLUCTUATING PROFITS]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2724Sch. 4A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 342, Sch. 3 (with Sch. 2)
F2725Sch. 4A inserted (11.5.2001) by Finance Act 2001 (c. 9), s. 71(2), Sch. 24 para. 1
F2726F2726SCHEDULE 5U.K.
Textual Amendments
F2726Sch. 5 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 280, Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Farming: the general ruleU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Farming: election for the herd basisU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Farming: provisions applicable to special casesU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Exclusion of working animals, and interpretation of preceding provisionsU.K.
7Nothing in this Schedule applies to any animals kept wholly or mainly for the work they do in connection with the carrying on of the farming.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Application of preceding provisions to trades other than farming, creatures other than animals, and animals and creatures kept singlyU.K.
9(1)The preceding provisions of this Schedule shall, with the necessary adaptations, apply in relation to trades other than farming, and trades consisting only in part of farming as they apply in relation to farming, and references to farmers shall be construed accordingly.
(2)Those provisions shall (both in relation to farming and in relation to other trades) apply in relation to living creatures other than animals as they apply in relation to animals.
(3)Laying birds shall be treated for the purposes of this Schedule as becoming mature when they first lay.
(4)The provisions of this Schedule shall (both in relation to farming and in relation to other trades) apply, with the necessary adaptations [F2756—
(a)in relation to animals or other creatures kept singly as they apply in relation to herds; and
(b)in relation to shares in animals or other creatures as they apply in relation to animals or other creatures themselves.]
(5)Nothing in this Schedule shall apply in relation to any animal or other creature kept wholly or mainly for public exhibition or for racing or other competitive purposes.
Supplemental and savingU.K.
10Where an election for the herd basis is made, every person carrying on any farming or other trade affected by the election shall, if required to do so by notice from the inspector, make and deliver to the inspector, within the time specified in the notice, such returns as to, and as to the products of, the animals or other creatures kept by him for the purposes of the trade as may be required by the notice.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .12The validity of an election for the herd basis in force immediately before the commencement of this Schedule and made in pursuance of—
(a)section 35 of the Finance Act 1973 on or after 25th July 1973 and before 6th April 1976, or
(b)section 48(6) to (9) of the Finance Act 1984,
shall not be affected by the repeal of those sections by this Act.
F2758F2758[F2759SCHEDULE 5AA]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2758Sch. 5AA repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 344, Sch. 3 (with Sch. 2)
F2759Sch. 5AA inserted (with effect in accordance with s. 80(6)(7) of the amending Act) by Finance Act 1997 (c. 16), s. 80(2), Sch. 11
F2776F2776[F2777SCHEDULE 5AU.K. Stock lending: interest on cash collateral]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2776Sch. 5A repealed (with effect in accordance with Sch. 10 para. 7(1) of the amending Act) by Finance Act 1997 (c. 16), Sch. 10 para. 1(2), Sch. 18 Pt. 6(10), Note 1; S.I. 1997/991, art. 2
F2778F2778SCHEDULE 6U.K.
Textual Amendments
F2778Schs. 6, 6A, 7, 7A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 paras. 110, 111, Sch 8 Pt. 1 (with Sch. 7)
[F2779Part IU.K. Tables of Flat Rate Cash Equivalents
Table A
Cars with an original market value up to £19,250 and having a cylinder capacity
| Cylinder capacity of car in cubic centimetres | Age of car at end of relevant year of assessment | |
|---|---|---|
| Under 4 years | 4 years or more | |
| 1,400 or less | £2,310 | £1,580 |
| More than 1,400 but not more than 2,000 | £2,990 | £2,030 |
| More than 2,000 | £4,800 | £3,220 |
Table B
Cars with an original market value up to £19,250 and not having a cylinder capacity
| Original market value of car | Age of car at end of relevant year of assessment | |
|---|---|---|
| Under 4 years | 4 years or more | |
| Less than £6,000 | £2,310 | £1,580 |
| £6,000 or more but less than £8,500 | £2,990 | £2,030 |
| £8,500 or more but not more than £19,250 | £4,800 | £3,220 |
Table C
Cars with an original market value of more than £19,250
| Original market value of car | Age of car at end of relevant year of assessment | |
|---|---|---|
| Under 4 years | 4 years or more | |
| More than £19,250 but not more than £29,000 | £6,210 | £4,180 |
| More than £29,000 | £10,040 | £6,660] |
PART IIU.K. SUPPLEMENTARY PROVISIONS
Cash equivalentU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .The appropriate percentageU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Car with CO2 emissions figureU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .The lower thresholdU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Bi-fuel carsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Automatic cars made available to disabled driversU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .“EC certificate of conformity", “EC type-approval certificate" and “UK approval certificate"U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Car with no CO2 emissions figureU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Diesel car supplementU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .DiscountsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Car registered before 1st January 1998U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Electrically propelled vehicleU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2780Reduction for periods when car unavailableU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2783Reduction for payments for use of carU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2785Replacement carsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2787 Meaning of “unavailable”U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2788GeneralU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2791F2791[F2792Schedule 6A]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2791Schs. 6, 6A, 7, 7A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 paras. 110, 111, Sch 8 Pt. 1 (with Sch. 7)
F2792Sch. 6A inserted (27.7.1993 with effect for the year 1993-94 and subsequent years of assessment) by 1993 c. 34, s. 73, Sch. 4 paras.7, 8
F2820F2820SCHEDULE 7U.K.
Textual Amendments
F2820Schs. 6, 6A, 7, 7A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 paras. 110, 111, Sch 8 Pt. 1 (with Sch. 7)
PART IU.K. MEANING OF “OBTAINED BY REASON OF EMPLOYMENT”
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .2M129In paragraph 1 above—
(a)references to a loan being made by any person include references to his assuming the rights and liabilities of the person who originally made the loan and to his arranging, guaranteeing or in any way facilitating the continuation of a loan already in existence;
(b)“employer” includes a prospective employer; and
(c)“company”, except in the expression “close company”, includes a partnership.
PART IIU.K. CALCULATION OF CASH EQUIVALENT OF LOAN BENEFIT
GeneralU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Normal method of calculation (averaging)U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Election for alternative method of calculationU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Apportionment of cash equivalent in case of joint loan etc.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IIIU.K.F2831. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IVU.K.F2835. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART VU.K.F2841. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2845F2845[F2846SCHEDULE 7AU.K. Beneficial loans: loans on ordinary commercial terms]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2845Schs. 6, 6A, 7, 7A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 paras. 110, 111, Sch 8 Pt. 1 (with Sch. 7)
F2846Sch. 7A inserted (with effect in accordance with s. 57(2) of the amending Act) by Finance Act 2000 (c. 17), s. 57(1), Sch. 10 para. 5(2)
F2847F2847SCHEDULE 8U.K.
Textual Amendments
F2847Sch. 8 repealed (with effect in accordance with s. 61(2)(3), Sch. 18 Pt. 6(3) Notes 1-3 of the repealing Act) by Finance Act 1997 (c. 16), Sch. 18 Pt. 6(3)
FormU.K.
1The terms of the scheme must be set out in writing.
Employer and employment unitU.K.
2The scheme must identify the scheme employer.
3If the scheme employer does not pay the emoluments of all the employees to whom the scheme relates, the scheme must identify each of the persons who pays the emoluments of any of those employees.
4(1)The scheme must identify the undertaking to which the scheme relates and that undertaking must be one which is carried on with a view to profit.
(2)The references in sub-paragraph (1) above to an undertaking include references to part of an undertaking; and the provisions of a scheme identifying part of an undertaking must do so in such a way as to distinguish it, otherwise than by name only, from other parts of the undertaking.
EmployeesU.K.
5The scheme must contain provisions by reference to which the employees to whom the scheme relates may be identified.
6The scheme must contain provisions ensuring that no payments are made under it by reference to a profit period if the employees to whom the scheme relates constitute less than 80 per cent. of all the employees in the employment unit at the beginning of that profit period, but for this purpose any person who is at that time within paragraph 7 or 8 below shall not be counted.
7(1)The scheme must contain provisions ensuring that no payments are made under it to any person who is employed in the employment unit by a company and who has F2848. . . a material interest in the company.
(2)For the purposes of this paragraph a person shall be treated as having a material interest [F2849 in a company if he, either on his own or with one or more associates,or if any associate of his with or without such other associates,—
(a)is the beneficial owner of, or able, directly or through the medium ofother companies, or by any other indirect means to control, more than 25 percent. of the ordinary share capital of the company, or
(b)in the case of a close company, possesses, or is entitled to acquire, such rights as would, in the event of the winding-up of the company or in any other circumstances, give an entitlement to receive more than 25 per cent. of the assets which would then be available for distribution among the participators].
(3)In this paragraph—
"associate" has the same meaning as in section 417(3) and (4) [F2850, but subject to sub-paragraph (4) below]; F2851. . .
"control" has the meaning given by section 840; [F2852and
“participator” has the meaning given by section 417(1)]
and the definition of "control" in section 840 applies (with the necessary modifications) in relation to a company which is an unincorporated association as it applies in relation to one that is not.
[F2853(4)For the purposes of this paragraph, where an employee of a company has an interest in shares or obligations of the company as a beneficiary of an employee benefit trust, the trustees shall not be regarded as associates of his by reason only of that interest unless sub-paragraph (8) below applies in relation to him.
(5)A trust is an employee benefit trust for the purposes of this paragraph if—
(a)all or most of the employees of the company are eligible to benefit under it, and
(b)none of the property subject to it has been disposed of on or after 14th March 1989 (whether by sale, loan or otherwise) except in the ordinary course of management of the trust or in accordance with sub-paragraph (6) below.
(6)Property is disposed of in accordance with this sub-paragraph if—
(a)it is applied for the benefit of—
(i)individual employees or former employees of the company,
(ii)spouses, former spouses, widows or widowers of employees or former employees of the company,
(iii)relatives, or spouses of relatives, of persons within sub-paragraph (i) or (ii) above, or
(iv)dependants of persons within sub-paragraph (i) above,
(b)it is applied for charitable purposes, or
(c)it is transferred to the trustees of an approved profit sharing scheme (within the meaning of section 187), of another employee benefit trust, or of a qualifying employee share ownership trust (within the meaning of Schedule 5 to the Finance Act 1989),
and the property applied or transferred consists of any of the ordinary share capital of the company or of money paid outright.
(7)In sub-paragraph (6)(a)(iii) above “relative” means parent or remoter forebear, child or remoter issue, brother, sister, uncle, aunt, nephew or niece.
(8)This sub-paragraph applies in relation to an employee if at any time on or after 14th March 1989—
(a)the employee, either on his own or with any one or more of his associates,or
(b)any associate of his, with or without other such associates,
has been the beneficial owner of, or able (directly or through the medium of other companies or by any other indirect means) to control, more than 25per cent. of the ordinary share capital of the company.
(9)Where—
(a)on or after 14th March 1989 an employee of a company, or an associate of his, receives a payment (“the relevant payment”) from the trustees of anemployee benefit trust, and
(b)at any time during the period of three years ending with the day on whichthe relevant payment is received, the property subject to the trust consists of or includes any part of the ordinary share capital of the company,
the employee or associate shall be treated for the purposes of sub-paragraph (8) above as if he were the beneficial owner of the appropriate percentage of the ordinary share capital of the company on the day on which the relevant payment is received (in addition to any percentage of that share capital of which he is actually the beneficial owner on that day).
(10)For the purposes of sub-paragraph (9) above, the appropriate percentage is—

where—
A is the smaller of—
(a) the aggregate of the relevant payment and any other payments received by the employee or associates of his from the trustees of the trust during the period of 12 months ending with the day on which the relevant payment is received, and
(b) the aggregate of the distributions made to the trustees of the trust by the company in respect of its ordinary share capital during the period of three years ending with the day on which the relevant payment is received; and
B is the aggregate of—
(a) any distributions made by the company in respect of its ordinary share capital during the period of 12 months ending with the day on which the relevant payment is received,
(b) any distributions so made during the period of 12 months immediately preceding that mentioned in paragraph (a) above, and
(c) any distributions so made during the period of 12 months immediately preceding that mentioned in paragraph (b) above,
divided by the number of the periods mentioned in paragraphs (a) to (c) above in which distributions were so made.
(11)Where—
(a)an employee or associate is treated by sub-paragraph (9) above as if he were the beneficial owner of a percentage of the ordinary share capital of a company by reason of receiving the relevant payment from the trustees of a trust, and
(b)that employee, or an associate of his, has, during the period of 12 months ending with the day on which the relevant payment is received, received one or more payments from trustees of another employee benefit trust or trusts satisfying the requirement in paragraph (b) of sub-paragraph (9) above,
that sub-paragraph shall have effect in relation to the employee or associate mentioned in paragraph (a) above as if he had received the payment from the trustees of the trust or of each of the trusts mentioned in paragraph (b) above (or where more than one payment has been received from the trustees of a trust, the last of the payments) on the day on which the relevant paymentis received.
(12)In sub-paragraphs (8) to (11) above “associate”, in relation to an employee, does not include the trustees of an employee benefit trust by reason only that the employee has an interest in shares or obligations of the trust.]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Profit periodsU.K.
9The scheme must identify the accounting period or periods by reference to which any profit-related pay is to be calculated.
10(1)Subject to sub-paragraphs (2) and (3) below, any such accounting period must be a period of 12 months.
(2)If the scheme is a replacement scheme, the first of two profit periods may be a period of less than 12 months, but the scheme may not provide for more than two profit periods.
(3)The scheme may make provision for a profit period to be abbreviated where registration of the scheme is cancelled with effect from a day after the beginning of the period; and a scheme making such provision may exclude the operation of all or any of the provisions of paragraph 13(4) and (5) or (as the case may be) paragraph 14(3)(b), (4) and (5) below in relation to the determination of the distributable pool for an abbreviated period.
(4)For the purposes of this paragraph, a scheme is a replacement scheme if—
(a)it succeeds another scheme (or two or more other schemes) registration of which was cancelled under section 178(1)(a) on the ground of a change in the employment unit or in the circumstances relating to the scheme; and
(b)that change occurred not more than three months before the beginning of the first (or only) profit period of the new scheme, and the Board are satisfied that it was not brought about with a view to the registration of the new scheme or in circumstances satisfying the conditions in section 177(1)(a), (b) and (c); and
(c)not less than one half of the employees to whom the new scheme relates were employees to whom the previous scheme (or any of the previous schemes) related at the time of that change.
Distributable poolU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Payment from distributable pool etc.U.K.
16The scheme must provide for the whole of the distributable pool to be paid to employees in the employment unit.
17The scheme must make provision as to when payments will be made to employees.
18(1)The provisions of the scheme must be such that employees participate in the scheme on similar terms.
(2)For the purposes of sub-paragraph (1) above, the fact that the payments to employees vary according to the levels of their remuneration, the length of their service or similar factors shall not be regarded as meaning that they do not participate on similar terms.
Ascertainment of profitsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Parts of undertakingsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Sections 185, 186, 187.
SCHEDULE 9U.K. APPROVED SHARE OPTION SCHEMES AND PROFIT SHARING SCHEMES
Modifications etc. (not altering text)
C102Sch. 9 excluded (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 238(2)(c)(4), 289 (with ss. 60, 101(1), 171, 201(3))
C103Sch. 9 modified (29.4.1996) by Finance Act 1996 (c. 8), s. 115
C104Sch. 9 modified (29.4.1996) by Finance Act 1996 (c. 8), s. 116(3)
C105Sch. 9 modified (28.7.2000) by Finance Act 2000 (c. 17), s. 49(1)(2)
C106Sch. 9 continued for specified purposes (6.4.2003 with effect in accordance with s. 723(1) of the affecting Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 418(3) (with Sch. 7)
[F2875PART IU.K. GENERAL
Textual Amendments
F2875Sch. 9 Pts. 1, 2, 6 repealed (except for specified purposes) (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 112(1), Sch 8 Pt. 1 (with Sch. 7)
1(1)M136Subject to the provisions of this Schedule, on the application of a body corporate (“the grantor”) which has established a share option scheme or a profit sharing scheme, the Board shall approve the scheme if they are satisfied that it fulfils such requirements of Part II and this Part as apply in relation to the scheme in question, and the requirements of Part III, IV or V of this Schedule; and in this Schedule—U.K.
“the relevant requirements” means, in relation to any scheme, the requirements of this Schedule by reference to which the scheme is approved; and
“” means a scheme in relation to which the relevant requirements include the requirements of Part III of this Schedule.
(2)M137An application under sub-paragraph (1) above shall be made in writing and contain such particulars and be supported by such evidence as the Board may require.
(3)M138Where the grantor has control of another company or companies, the scheme may be expressed to extend to all or any of the companies of which it has control and in this Schedule a scheme which is expressed so to extend is referred to as a “group scheme”.
(4)M139In relation to a group scheme the expression “participating company” means the grantor or any other company to which for the time being the scheme is expressed to extend.
Marginal Citations
M136Source—1978 Sch.9 1(1)(a); 1980 Sch.10 1(1)(a); 1984 Sch.10 1(1)
M137Source—1978 Sch.9 1(5); 1980 Sch.10 1(2); 1984 Sch.10 1(2)
M138Source—1978 Sch.9 1(2); 1980 Sch.10 1(3); 1984 Sch.10 1(3)
M139Source—1978 Sch.9 1(2); 1980 Sch.10 1(3); 1984 Sch.10 1(4)
2(1)M140The Board shall not approve a scheme under this Schedule if it appears to them that it contains features which are neither essential nor reasonably incidental to the purpose of providing for employees and directors benefits in the nature of rights to acquire shares or, in the case of a profit sharing scheme, in the nature of interests in shares.U.K.
(2)M141A profit sharing scheme shall not be approved under paragraph 1 above unless the Board are satisfied that, whether under the terms of the scheme or otherwise, every participant in the scheme is bound in contract with the grantor—
(a)to permit his shares to remain in the hands of the trustees throughout the period of retention; and
(b)not to assign, charge or otherwise dispose of his beneficial interest in his shares during that period; and
(c)if he directs the trustees to transfer the ownership of his shares to him at any time before the release date, to pay to the trustees before the transfer takes place a sum equal to income tax at the basic rate on the appropriate percentage of the locked-in value of the shares at the time of the direction; and
(d)not to direct the trustees to dispose of his shares at any time before the release date in any other way except by sale for the best consideration in money that can reasonably be obtained at the time of the sale or, in the case of redeemable shares in a workers’ cooperative, by redemption.
[F2876(2A)The Board shall not approve a profit sharing scheme unless they are satisfied—
(a)that the arrangements for the scheme do not make any provision, and are not in any way associated with any provision made, for loans to some or all of the employees of—
(i)the company that established the scheme, or
(ii)in the case of a group scheme, any participating company, and
(b)that the operation of the scheme is not in any way associated with such loans.
(2B)For the purposes of sub-paragraph (2A) above “arrangements” includes any scheme, agreement or understanding, whether or not legally enforceable.]
(3)M142The Board must be satisfied in the case of a savings-related share option scheme or a profit sharing scheme—
(a)that there are no features of the scheme (other than any which are included to satisfy requirements of this Schedule) which have or would have the effect of discouraging any description of employees or former employees who fulfil the conditions in paragraph 26(1) or, as the case may be, 36(1) below from actually participating in the scheme; and
(b)where the grantor is a member of a group of companies, that the scheme does not and would not have the effect of conferring benefits wholly or mainly on directors of companies in the group or on those employees of companies in the group who are in receipt of the higher or highest levels of remuneration.
(4)For the purposes of sub-paragraph (3) above “a group of companies” means a company and any other companies of which it has control.
Textual Amendments
F2876Sch. 9 para. 2(2A)(2B) inserted (21.3.2000) by Finance Act 2000 (c. 17), s. 53(1)(3)
Modifications etc. (not altering text)
C107Sch. 9 para. 2(2) excluded (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 238(1)(4), 289 (with ss. 60, 101(1), 171, 201(3))
Marginal Citations
M140Source—1978 Sch.9 1(1)(b); 1980 Sch.10 1(1), (b); 1984 Sch.10 1(1); 1987 Sch.15 13
M141Source—1978 s.54(1); 1986 s.24(3)(a)
M142Source—1978 Sch.9 2(3), (4); 1980 Sch.10 1(1)(aa), (ab), (1A); 1983 s.25(5); 1984 s.39(2)
3(1)If, at any time after the Board have approved a share option scheme, any of the relevant requirements ceases to be satisfied or the grantor fails to provide information requested by the Board under paragraph 6 below, the Board may withdraw the approval with effect from that time or such later time as the Board may specify; but where rights obtained under a savings-related share option scheme before the withdrawal of approval from the scheme under this paragraph are exercised after the withdrawal, section 185(3) shall apply in respect of the exercise as if the scheme were still approved.U.K.
(2)If at any time after the Board have approved a profit sharing scheme—
(a)a participant is in breach of any of his obligations under paragraph 2(2)(a), (c) and (d) above; or
(b)there is, with respect to the operation of the scheme, any contravention of any of the relevant requirements, Schedule 10, the scheme itself or the terms of the trust referred to in paragraph 30(1)(c) below; or
(c)any shares of a class of which shares have been appropriated to the participants receive different treatment in any respect from the other shares of that class, in particular, different treatment in respect of—
(i)the dividend payable;
(ii)repayment;
(iii)the restrictions attaching to the shares; or
(iv)any offer of substituted or additional shares, securities or rights of any description in respect of the shares; or
[F2877(ca)the Board—
(i)cease to be satisfied of the matters mentioned in paragraph 2(2A) above, or
(ii)in the case of a scheme approved before 21st March 2000, are not satisfied of those matters; or]
(d)the Board cease to be satisfied that the scheme complies with the requirements of paragraph 2(3) above or paragraph 36 below; or
(e)the trustees, the grantor or, in the case of a group scheme, a company which is or has been a participating company fail or fails to furnish any information which they are or it is required to furnish under paragraph 6 below [F2878; or,
(f)the trustees appropriate shares to participants, one or more of whom have had free shares appropriated to them, at an earlier time in the same year of assessment, under a relevant share plan],
the Board may, subject to sub-paragraph (3) below, withdraw the approval with effect from that time or from such later time as the Board may specify.
(3)M143It shall not be a ground for withdrawal of approval of a profit sharing scheme that shares which have been newly issued receive, in respect of dividends payable with respect to a period beginning before the date on which the shares were issued, treatment which is less favourable than that accorded to shares issued before that date.
[F2879(4)For the purposes of sub-paragraph (2)(f) above the reference to persons having had free shares appropriated to them includes persons who would have had free shares appropriated to them but for their failure to obtain a performance allowance (within the meaning of paragraph 25 of Schedule 8 to the Finance Act 2000).
(5)In sub-paragraph (2)(f) and (4) above—
“” has the same meaning as in Schedule 8 to the Finance Act 2000;
“”, in relation to a profit sharing scheme, means an employee share ownership plan that—
(a)was established by the grantor or a connected company, and
(b)is approved under Schedule 8 to that Act.
(6)For the purposes of sub-paragraph (5) above “connected company” means—
(a)a company which controls or is controlled by the grantor or which is controlled by a company which also controls the grantor, or
(b)a company which is a member of a consortium owning the grantor or which is owned in part by the grantor as a member of a consortium.]
Textual Amendments
F2877Sch. 9 para. 3(2)(ca) inserted (21.3.2000) by Finance Act 2000 (c. 17), s. 53(2)(3)
F2878Sch. 9 para. 3(2)(f) and preceding word inserted (28.7.2000) by Finance Act 2000 (c. 17), s. 51(1)
F2879Sch. 9 para. 3(4)-(6) inserted (28.7.2000) by Finance Act 2000 (c. 17), s. 51(2)
Marginal Citations
M143Source—1978 Sch.9 3(3)
4U.K.M144If an alteration is made in the scheme at any time after the Board have approved the scheme, the approval shall not have effect after the date of the alteration unless the Board have approved the alteration.
Modifications etc. (not altering text)
C108Sch. 9 para. 4 modified (with effect in accordance with Sch. 16 para. 1 of the modifying Act) by Finance Act 1996 (c. 8), Sch. 16 para. 4
Marginal Citations
M144Source—1978 Sch.9 3(2); 1980 Sch.10 3(2); 1984 Sch.10 2(2)
5U.K.M145If aggrieved—
(a)in any case, by the failure of the Board to approve the scheme or to approve an alteration in the scheme or by the withdrawal of approval; or
(b)in the case of a savings-related share option scheme, by the failure of the Board to decide that a condition subject to which the approval has been given is satisfied; or
(c)in the case of a profit sharing scheme, by the failure of the Board to approve an alteration in the terms of the trust referred to in paragraph 30(1)(c) below;
the grantor may, by notice given to the Board within 30 days from the date on which it is notified of the Board’s decision, require the matter to be determined by the Special Commissioners, and the Special Commissioners shall hear and determine the matter in like manner as an appeal.
Modifications etc. (not altering text)
C109Sch. 9 para. 5 modified (1.4.2009) by The Transfer of Tribunal Functions and Revenue and Customs Appeals Order 2009 (S.I. 2009/56), art. 1(2), Sch. 1 para. 158
Marginal Citations
M145Source—1978 Sch.9 4; 1980 Sch.10 4; 1984 Sch.10 3
6U.K.M146The Board may by notice require any person to furnish them, within such time as the Board may direct (not being less than 30 days), with such information as the Board think necessary for the performance of their functions under the relevant provisions and as the person to whom the notice is addressed has or can reasonably obtain, including in particular information—
(a)to enable the Board to determine—
(i)whether to approve a scheme or withdraw an approval already given; or
(ii)the liability to tax, including capital gains tax, of any person who has participated in a scheme; and
(b)in relation to the administration of a scheme and any alteration of the terms of a scheme.]
Marginal Citations
M146Source—1978 s.53(7); 1980 Sch.10 25; 1984 Sch.10 14
[F2880PART IIU.K. REQUIREMENTS GENERALLY APPLICABLE
Textual Amendments
F2880Sch. 9 Pts. 1, 2, 6 repealed (except for specified purposes) (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 112(1), Sch 8 Pt. 1 (with Sch. 7)
7U.K.The provisions of this Part apply in relation to all schemes unless otherwise stated.
8U.K.M147The scheme must not provide for any person to be eligible to participate in it, that is to say, to obtain and exercise rights under it, or in the case of a profit sharing scheme to have shares appropriated to him, at any time when he has, or has within the preceding 12 months had, a material interest in a close company which is—
(a)a company shares in which, in the case of a profit sharing scheme, are to be appropriated or, in the case of a share option scheme, may be acquired pursuant to the exercise of rights obtained under the scheme; or
(b)a company which has control of such a company or is a member of a consortium which owns such a company.
In determining whether a company is a close company for the purposes of this paragraph, sections 414(1)(a) and 415 shall be disregarded.
Marginal Citations
M147Source—1978 Sch.9 11(1), (2); 1980 Sch.10 23; 1984 Sch.10 4(1)(b), (3)
F28818A(1)In the case of a savings-related share option scheme or a profit sharing scheme, the scheme must specify what age is to be the specified age for the purposes of the scheme.U.K.
(2)The age specified—
(a)must be the same for men and women, and
(b)must be not less than 60 and not more than 75.]
Textual Amendments
9(1)M148A share option scheme must provide for directors and employees to obtain rights to acquire shares (“”) which satisfy the requirements of paragraphs 10 to 14 below [F2882(disregarding paragraph 11A)].U.K.
(2)In the case of a profit sharing scheme, the shares to be acquired by the trustees as mentioned in paragraph 30 below (“”) must satisfy the requirements of paragraphs 10 to 12 and 14 below.
Textual Amendments
F2882Words in Sch. 9 para. 9(1) inserted (21.3.2000) by Finance Act 2000 (c. 17), s. 52(2)(5)
Marginal Citations
M148Source—1978 Sch.9 1(1), (3); 1980 Sch.10 5(a); 1984 Sch.10
10U.K.M149Scheme shares must form part of the ordinary share capital of—
(a)the grantor; or
(b)a company which has control of the grantor; or
(c)a company which either is, or has control of, a company which—
(i)is a member of a consortium owning either the grantor or a company having control of the grantor; F2883. . .
F2883(ii). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2883Sch. 9 para. 10(c)(ii) and preceding word repealed by Finance Act 1989 (c. 26), s. 64, Sch. 17 Pt. 4
Marginal Citations
M149Source—1978 Sch.9 5; 1980 Sch.10 15; 1984 Sch.10 7
11U.K.M150Scheme shares must be—
(a)shares of a class [F2884listed] on a recognised stock exchange; or
(b)shares in a company which is not under the control of another company; or
(c)shares in a company which is under the control of a company (other than a company which is, or would if resident in the United Kingdom be, a close company), whose shares are [F2884listed] on a recognised stock exchange.
Textual Amendments
F2884Words in Sch. 9 para. 11(a)(c) substituted (with effect in accordance with Sch. 38 para. 6(10) of the amending Act) by Finance Act 1996 (c. 8), Sch. 38 para. 6(1)(2)(j)
Marginal Citations
M150Source—1978 Sch.9 6; 1980, s.46(10), Sch.10 16; 1984 Sch.10 8
[F288511A(1)In the case of a profit sharing scheme, scheme shares must not be shares—U.K.
(a)in an employer company, or
(b)in a company that—
(i)has control of an employer company, and
(ii)is under the control of a person or persons within sub-paragraph (2)(b)(i) below in relation to an employer company.
(2)For the purposes of this paragraph a company is “an employer company” if—
(a)the business carried on by it consists substantially in the provision of the services of the persons employed by it, and
(b)the majority of those services are provided to—
(i)a person who has, or two or more persons who together have, control of the company, or
(ii)a company associated with the company.
(3)For the purposes of sub-paragraph (2)(b)(ii) above a company shall be treated as associated with another company if both companies are under the control of the same person or persons.
(4)For the purposes of sub-paragraphs (1) to (3) above—
(a)references to a person include a partnership, and
(b)where a partner, alone or together with others, has control of a company, the partnership shall be treated as having like control of that company.
(5)For the purposes of this paragraph the question whether a person controls a company shall be determined in accordance with section 416(2) to (6).]
Textual Amendments
F2885Sch. 9 para. 11A inserted (21.3.2000) by Finance Act 2000 (c. 17), s. 52(3)(5) (with s. 52(6))
12(1)M151Scheme shares must be—U.K.
(a)fully paid up;
(b)not redeemable; and
(c)not subject to any restrictions [F2886other than those permitted by sub-paragraph (1A) below.]
Sub-paragraph (b) above does not apply, in the case of a profit sharing scheme, in relation to shares in a workers’ cooperative.
[F2887(1A)Subject to sub-paragraph (1B) below, scheme shares may be subject to—
(a)restrictions which attach to all shares of the same class, or
(b)a restriction authorised by sub-paragraph (2) below.
(1B)In the case of a profit sharing scheme, scheme shares must not be subject to any restrictions affecting the rights attaching to those shares which relate to—
(a)dividends, or
(b)assets on a winding-up of the company,
other than restrictions which attach to all other ordinary shares in the same company.]
(2)Except as provided below, the shares may be subject to a restriction imposed by the company’s articles of association—
(a)requiring all shares held by directors or employees of the company or of any other company of which it has control to be disposed of on ceasing to be so held; and
(b)requiring all shares acquired, in pursuance of rights or interests obtained by such directors or employees, by persons who are not (or have ceased to be) such directors or employees to be disposed of when they are acquired.
(3)A restriction is not authorised by sub-paragraph (2) above unless—
(a)any disposal required by the restriction will be by way of sale for a consideration in money on terms specified in the articles of association; and
(b)the articles also contain general provisions by virtue of which any person disposing of shares of the same class (whether or not held or acquired as mentioned in sub-paragraph (2) above) may be required to sell them on terms which are the same as those mentioned in paragraph (a) above.
(4)In the case of a profit sharing scheme, except in relation to redeemable shares in a workers’ cooperative, nothing in sub-paragraph (2) above authorises a restriction which would require a person, before the release date, to dispose of his beneficial interest in shares the ownership of which has not been transferred to him.
Textual Amendments
F2886Words in Sch. 9 para. 12(1)(c) substituted (21.3.2000) by Finance Act 2000 (c. 17), s. 52(4)(a)(5) (with s. 52(6))
F2887Sch. 9 para. 12(1A)(1B) inserted (21.3.2000) by Finance Act 2000 (c. 17), s. 52(4)(b)(5) (with s. 52(6))
Marginal Citations
M151Source—1978 Sch.9 7; 1980 Sch.10 17; 1984 Sch.10 9; 1986 s.22, 24(2)
13(1)M152In determining, in the case of a share option scheme, for the purposes of paragraph 12(1)(c) above whether scheme shares which are or are to be acquired by any person are subject to any restrictions, there shall be regarded as a restriction attaching to the shares any contract, agreement, arrangement or condition by which his freedom to dispose of the shares or of any interest in them or of the proceeds of their sale or to exercise any right conferred by them is restricted or by which such a disposal or exercise may result in any disadvantage to him or to a person connected with him.U.K.
(2)Sub-paragraph (1) does not apply to so much of any contract, agreement, arrangement or condition as contains provisions similar in purpose and effect to any of the provisions of the Model Rules set out in the Model Code for Securities Transactions by Directors of Listed Companies issued by the Stock Exchange in November 1984.
[F2888(3)In the case of schemes other than savings-related share option schemes, sub-paragraph (1) above does not apply in relation to any terms of a loan making provision about how it is to be repaid or the security to be given for it.]
Textual Amendments
F2888Sch. 9 para. 13(3) added (retrospectively) by Finance Act 1988 (c. 39), s. 69(1)
Marginal Citations
M152Source—1980 Sch.10 18; 1982 s.41; 1984 Sch.10 10; 1986 s.23(4)
14(1)M153Except where scheme shares are shares in a company the ordinary share capital of which consists of shares of one class only, the majority of the issued shares of the same class either must be employee-control shares or must be held by persons other than—U.K.
(a)persons who acquired their shares in pursuance of a right conferred on them or an opportunity afforded to them as a director or employee of the grantor or any other company and not in pursuance of an offer to the public;
(b)trustees holding shares on behalf of persons who acquired their beneficial interests in the shares as mentioned in sub-paragraph (a) above; and
(c)in a case where the shares fall within sub-paragraph (c), but not within sub-paragraph (a), of paragraph 11 above, companies which have control of the company whose shares are in question or of which that company is an associated company.
(2)In its application to a profit sharing scheme, sub-paragraph (1) above shall have effect with the addition after the words “ordinary share capital of which” of the words “ at the time of the acquisition of the shares by the trustees ”.
(3)For the purposes of this paragraph, shares in a company are employee-control shares if—
(a)the persons holding the shares are, by virtue of their holding, together able to control the company; and
(b)those persons are or have been employees or directors of the company or of another company which is under the control of the company.
Marginal Citations
M153Source—1978 Sch.9 8; 1980 s.46(11), Sch.10 19; 1984 Sch.10 11; 1986 s.23(3)
15(1)M154Except in the case of a profit sharing scheme, the scheme may provide that if any company (“the acquiring company”)—U.K.
(a)obtains control of a company whose shares are scheme shares as a result of making a general offer—
(i)to acquire the whole of the issued ordinary share capital of the company which is made on a condition such that if it is satisfied the person making the offer will have control of the company; or
(ii)to acquire all the shares in the company which are of the same class as the scheme shares;
(b)obtains control of a company whose shares are scheme shares in pursuance of a compromise or arrangement sanctioned by the court under section 425 of the M155Companies Act 1985 or Article 418 of the M156Companies (Northern Ireland) Order 1986; or
(c)becomes bound or entitled to acquire shares in a company whose shares are scheme shares under sections 428 to 430 of that Act or Articles 421 to 423 of that Order,
any participant in the scheme may at any time within the appropriate period, by agreement with the acquiring company, release his rights under the scheme (in this paragraph referred to as “the old rights”) in consideration of the grant to him of rights (in this paragraph referred to as “the new rights”) which are equivalent to the old rights but relate to shares in a different company (whether the acquiring company itself or some other company falling within paragraph 10(b) or (c) above).
(2)In sub-paragraph (1) above “the appropriate period” means—
(a)in a case falling within paragraph (a), the period of six months beginning with the time when the person making the offer has obtained control of the company and any condition subject to which the offer is made is satisfied;
(b)in a case falling within paragraph (b), the period of six months beginning with the time when the court sanctions the compromise or arrangement; and
(c)in a case falling within paragraph (c), the period during which the acquiring company remains bound or entitled as mentioned in that paragraph.
(3)The new rights shall not be regarded for the purposes of this paragraph as equivalent to the old rights unless—
(a)the shares to which they relate satisfy the conditions specified, in relation to scheme shares, in paragraphs 10 to 14 above; and
(b)the new rights will be exercisable in the same manner as the old rights and subject to the provisions of the scheme as it had effect immediately before the release of the old rights; and
(c)the total market value, immediately before the release, of the shares which were subject to the participant’s old rights is equal to the total market value, immediately after the grant, of the shares in respect of which the new rights are granted to the participant; and
(d)the total amount payable by the participant for the acquisition of shares in pursuance of the new rights is equal to the total amount that would have been payable for the acquisition of shares in pursuance of the old rights.
(4)Where any new rights are granted pursuant to a provision included in a scheme by virtue of this paragraph they shall be regarded—
(a)for the purposes of section 185 and this Schedule; and
(b)for the purposes of the subsequent application (by virtue of a condition complying with sub-paragraph (3)(b) above) of the provisions of the scheme,
as having been granted at the time when the corresponding old rights were granted.
(5)M157Where a scheme which was approved before 1st August 1987 is altered before 1st August 1989 so as to include such a provision as is mentioned above (“an exchange provision”), the scheme as altered may by virtue of this and the following sub-paragraphs apply that provision to rights obtained under the scheme before the date on which the alteration takes effect.
(6)If an exchange provision is applied as mentioned in sub-paragraph (5) above in a case where, on or after 17th March 1987 but before the date on which the alteration takes effect, an event has occurred by reason of which a person holding rights under the scheme would be able to take advantage of the exchange provision—
(a)the scheme may permit a person who held rights under the scheme immediately before that event to take advantage of the exchange provision; and
(b)in a case where rights then held would otherwise, by reason of the event, have ceased to be exercisable, the scheme may provide that the exchange provision shall apply as if the rights were still exercisable.
(7)The application of an exchange provision as mentioned in sub-paragraph (5) or (6) above shall not itself be regarded for the purposes of this Schedule as the acquisition of a right.
(8)Sub-paragraphs (5) and (6) above have effect subject to paragraph 4 above.
Marginal Citations
M154Source—1980 Sch.10, 10A; 1984 Sch.10 4A; 1987 Sch.4 1, 2; 1987 (No.2) s.59
M157Source—1987 Sch.4 3
F2889F2889PART IIIU.K. REQUIREMENTS APPLICABLE TO SAVINGS-RELATED SHARE OPTION SCHEMES
Textual Amendments
F2889Sch. 9 Pts. 3, 4 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 112(2), Sch 8 Pt. 1 (with Sch. 7)
16(1)M158The scheme must provide for the scheme shares to be paid for with moneys not exceeding the amount of repayments made and any interest paid to them under a certified contractual savings scheme which has been approved by the Board for the purposes of this Schedule.
(2)M159Where the Board are satisfied that—
(a)a person has entered into a certified contractual savings scheme before 15th November 1980, and
(b)he has obtained rights under a scheme established before that date to acquire shares in a company of which he is an employee or director (or a company of which such a company has control) using repayments made under the certified contractual savings scheme;
then, repayments and interest paid under the certified contractual savings scheme shall be treated as repayments and interest paid, under a scheme approved by the Board for the purposes of this Schedule under sub-paragraph (1) above, and, accordingly, may be used for the purchase of shares under a savings-related share option scheme approved under this Schedule.
(3)The repayments and interest to which sub-paragraph (2) above applies shall not exceed the repayments and interest to which the participant would have been entitled if the terms of the scheme had corresponded to those of a certified contractual savings scheme approved by the Board under sub-paragraph (1) above.
17M160Subject to paragraphs 18 to 21 below, the rights obtained under the scheme must not be capable of being exercised before the bonus date, that is to say, the date on which repayments under the certified contractual savings scheme are due; and for the purposes of this paragraph and paragraph 16 above—
(a)repayments under a certified contractual savings scheme may be taken as including or as not including a bonus;
(b)the time when repayments are due shall be, where repayments are taken as including the maximum bonus, the earliest date on which the maximum bonus is payable and, in any other case, the earliest date on which a bonus is payable under the scheme; and
(c)the question what is to be taken as so included must be required to be determined at the time when rights under the scheme are obtained.
18M161The scheme must provide that if a person who has obtained rights under the scheme dies before the bonus date the rights must be exercised, if at all, within 12 months after the date of his death and if he dies within six months after the bonus date the rights may be exercised within 12 months after the bonus date.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .22M167Except as provided in paragraph 18 above, rights obtained by a person under the scheme must not be capable—
(a)of being transferred by him, or
(b)of being exercised later than six months after the bonus date.
23M168No person shall be treated for the purposes of paragraph 19 or 21(1)(e) above as ceasing to hold an office or employment by virtue of which he is eligible to participate in the scheme until he ceases to hold an office or employment in the grantor or in any associated company or company of which the grantor has control.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .25M171The price at which scheme shares may be acquired by the exercise of a right obtained under the scheme—
(a)must be stated at the time the right is obtained, and
(b)must not be manifestly less than [F289780%.] of the market value of shares of the same class at that time or, if the Board and the grantor agree in writing, at such earlier time or times as may be provided in the agreement,
but the scheme may provide for such variation of the price as may be necessary to take account of any variation in the share capital of which the scheme shares form part.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F2900F2900PART IVU.K. REQUIREMENTS APPLICABLE TO OTHER SHARE OPTION SCHEMES
Textual Amendments
F2900Sch. 9 Pts. 3, 4 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 112(2), Sch 8 Pt. 1 (with Sch. 7)
PART VU.K. REQUIREMENTS APPLICABLE TO PROFIT SHARING SCHEMES
30(1)M178The scheme must provide for the establishment of a body of persons resident in the United Kingdom (“the trustees”)—U.K.
(a)who, out of moneys paid to them by the grantor or, in the case of a group scheme, a participating company, are required by the scheme to acquire shares in respect of which the conditions in paragraphs 10 to 12 and 14 above are fulfilled; and
(b)who are under a duty to appropriate shares acquired by them to individuals who participate in the scheme, not being individuals who are ineligible by virtue of paragraph 8 or 35 of this Schedule; and
(c)whose functions with respect to shares held by them are regulated by a trust which is constituted under the law of a part of the United Kingdom and the terms of which are embodied in an instrument which complies with the provisions of paragraphs 31 to 34 below.
(2)M179If at any time after the Board have approved the scheme, an alteration is made in the terms of the trust referred to in sub-paragraph (1)(c) above, the approval shall not have effect after the date of the alteration unless the Board have approved the alteration.
(3)M180The scheme must provide that the total of the initial market values of the shares appropriated to any one participant in a year of assessment will not exceed the relevant amount.
(4)M181In this Part of this Schedule “initial market value”, in relation to a participant’s shares, means the market value of those shares determined—
(a)except where paragraph (b) below applies, on the date on which the shares were appropriated to him; and
(b)if the Board and the trustees agree in writing, on or by reference to such earlier date or dates as may be provided for in the agreement.
Marginal Citations
M178Source—1978 Sch.9 1(3)
M179Source—1978 Sch.9 3(2)
M180Source—1978 Sch.9 1 (4); 1983 s.25(1)
M181Source—1978 s.53(4)
31U.K.M182The trust instrument shall provide that, as soon as practicable after any shares have been appropriated to a participant, the trustees will give him notice of the appropriation—
(a)specifying the number and description of those shares; and
(b)stating their initial market value.
Marginal Citations
M182Source—1978 Sch.9 12
32(1)M183The trust instrument must contain a provision prohibiting the trustees from disposing of any shares, except as mentioned in paragraph 1(1)(a), (b) [F2907, (c) or (cc)] of Schedule 10, during the period of retention (whether by transfer to the participant or otherwise).U.K.
(2)The trust instrument must contain a provision prohibiting the trustees from disposing of any shares after the end of the period of retention and before the release date except—
(a)pursuant to a direction given by or on behalf of the participant or any person in whom the beneficial interest in his shares is for the time being vested; and
(b)by a transaction which would not involve a breach of the participant’s obligations under paragraph 2(2)(c) or (d) above.
Textual Amendments
F2907Words in Sch. 9 para. 32(1) substituted (with effect in accordance with s. 101(9)(10) of the amending Act) by Finance Act 1994 (c. 9), s. 101(5)
Marginal Citations
M183Source—1978 Sch.9 13; 1980 s.46(13)
33U.K.M184The trust instrument must contain a provision requiring the trustees—
(a)subject to their obligations under paragraph 7 of Schedule 10 and to any such direction as is mentioned in paragraph 4(2) of that Schedule to pay over to the participant any money or money’s worth received by them in respect of or by reference to any of his shares other than money’s worth consisting of new shares within the meaning of paragraph 5 of that Schedule; and
(b)to deal only pursuant to a direction given by or on behalf of the participant or any person in whom the beneficial interest in his shares is for the time being vested with any right conferred in respect of any of his shares to be allotted other shares, securities or rights of any description.
Modifications etc. (not altering text)
C111Sch. 9 para. 33(a) modified (with effect in accordance with s. 101(11)(12) of the affecting Act) by Finance Act 1994 (c. 9), s. 101(6) (with s. 101(14))
Marginal Citations
M184Source—1978 Sch.9 14
34U.K.M185The trust instrument must impose an obligation on the trustees—
(a)to maintain such records as may be necessary to enable the trustees to carry out their obligations under paragraph 7 of Schedule 10; and
(b)where the participant becomes liable to income tax under Schedule E by reason of the occurrence of any event, to inform him of any facts relevant to determining that liability.
Marginal Citations
M185Source—1978 Sch.9 15
35(1)M186An individual shall not be eligible to have shares appropriated to him under the scheme at any time unless he is at that time or was within the preceding 18 months a director or employee of the grantor or, in the case of a group scheme, of a participating company.U.K.
(2)M187An individual shall not be eligible to have shares appropriated to him under the scheme at any time if in that year of assessment shares have been appropriated to him under another approved scheme established by the grantor or by—
(a)a company which controls or is controlled by the grantor or which is controlled by a company which also controls the grantor, or
(b)a company which is a member of a consortium owning the grantor or which is owned in part by the grantor as a member of a consortium.
36(1)M188Subject to paragraphs 8 and 35 above, every person who at any time—U.K.
(a)is [F2908an employee] or a full-time director of the grantor or, in the case of a group scheme, a participating company, and
(b)has been such an employee or director at all times during a qualifying period, not exceeding five years, ending at that time, and
(c)is chargeable to tax in respect of his office or employment under Case I of Schedule E,
must then be eligible (subject to paragraphs 8 and 35 of this Schedule) to participate in the scheme on similar terms and those who do participate must actually do so on similar terms.
(2)For the purposes of sub-paragraph (1) above, the fact that the number of shares to be appropriated to the participants in a scheme varies by reference to the levels of their remuneration, the length of their service or similar factors shall not be regarded as meaning that they are not eligible to participate in the scheme on similar terms or do not actually do so.
Textual Amendments
F2908Words in Sch. 9 para. 36(1)(a) substituted (with application in accordance with s. 137(7) of the amending Act) by Finance Act 1995 (c. 4), s. 137(4)
Marginal Citations
M188Source—1978 Sch.9 2; 1983 s.25(4)
[F2909PART VIU.K. MATERIAL INTEREST TEST
Textual Amendments
F2909Sch. 9 Pts. 1, 2, 6 repealed (except for specified purposes) (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 112(1), Sch 8 Pt. 1 (with Sch. 7)
Interests under trustsU.K.
37(1)This M189 paragraph applies in a case where—U.K.
(a)the individual (“the beneficiary”) was one of the objects of a discretionary trust; and
(b)the property subject to the trust at any time consisted of or included any shares or obligations of the company.
(2)If neither the beneficiary nor any relevant associate of his had received any benefit under the discretionary trust before 14th November 1986, then, as respects any time before that date, the trustees of the settlement concerned shall not be regarded, by reason only of the matters referred to in sub-paragraph (1) above, as having been associates (as defined in section 417(3) and (4)) of the beneficiary.
(3)If, on or after 14th November 1986—
(a)the beneficiary ceases to be eligible to benefit under the discretionary trust by reason of—
(i)an irrevocable disclaimer or release executed by him under seal; or
(ii)the irrevocable exercise by the trustees of a power to exclude him from the objects of the trust; and
(b)immediately after he so ceases, no relevant associate of his is interested in the shares or obligations of the company which are subject to the trust; and
(c)during the period of 12 months ending with the date when the beneficiary so ceases, neither the beneficiary nor any relevant associate of his received any benefit under the trust,
the beneficiary shall not be regarded, by reason only of the matters referred to in sub-paragraph (1) above, as having been interested in the shares or obligations of the company as mentioned in section 417(3)(c) at any time during the period of 12 months referred to in paragraph (c) above.
(4)In sub-paragraphs (2) and (3) above “relevant associate” has the meaning given to “associate” by subsection (3) of section 417 but with the omission of paragraph (c) of that subsection.
(5)Sub-paragraph (3)(a)(i) above, in its application to Scotland, shall be construed as if the words “under seal” were omitted.
Marginal Citations
M189Source—1987 Sch.4 6-8
Options etc.U.K.
38(1)For the purposes of section 187(3)(a) a right to acquire shares (however arising) shall be taken to be a right to control them.U.K.
(2)Any reference in sub-paragraph (3) below to the shares attributed to an individual is a reference to the shares which, in accordance with section 187(3)(a), fall to be brought into account in his case to determine whether their number exceeds a particular percentage of the company’s ordinary share capital.
(3)In any case where—
(a)the shares attributed to an individual consist of or include shares which he or any other person has a right to acquire; and
(b)the circumstances are such that, if that right were to be exercised, the shares acquired would be shares which were previously unissued and which the company is contractually bound to issue in the event of the exercise of the right;
then, in determining at any time prior to the exercise of that right whether the number of shares attributed to the individual exceeds a particular percentage of the ordinary share capital of the company, that ordinary share capital shall be taken to be increased by the number of unissued shares referred to in paragraph (b) above.
(4)This paragraph has effect as respects any time after 5th April 1987.
Shares held by trustees of approved profit sharing schemesU.K.
39U.K.In applying section 187(3), as respects any time before or after the passing of this Act, there shall be disregarded—
(a)the interest of the trustees of an approved profit sharing scheme in any shares which are held by them in accordance with the scheme and have not yet been appropriated to an individual; and
(b)any rights exercisable by those trustees by virtue of that interest.
[F2910 Shares subject to an employee benefit trustU.K.
Textual Amendments
F2910Sch. 9 para. 40 and preceding cross-heading inserted by Finance Act 1989 (c. 26), s. 65
40(1)Where an individual has an interest in shares or obligations of the company as a beneficiary of an employee benefit trust, the trustees shall not be regarded as associates of his by reason only of that interest unless sub-paragraph (3) below applies in relation to him.U.K.
(2)In this paragraph “employee benefit trust” has the same meaning as in paragraph 7 of Schedule 8.
(3)This sub-paragraph applies in relation to an individual if at any time on or after 14th March 1989—
(a)the individual, either on his own or with any one or more of his associates, or
(b)any associate of his, with or without other such associates,
has been the beneficial owner of, or able (directly or through the medium of other companies or by any other indirect means) to control, more than 25 per cent., or in the case of a share option scheme which is not a savings-related share option scheme more than 10 per cent., of the ordinary share capital of the company.
(4)Sub-paragraphs (9) to (12) of paragraph 7 of Schedule 8 shall apply for the purposes of this paragraph in relation to an individual as they apply for the purposes of that paragraph in relation to an employee.]]
SCHEDULE 10U.K. FURTHER PROVISIONS RELATING TO PROFIT SHARING SCHEMES
Modifications etc. (not altering text)
C112Sch. 10 excluded (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 238(2)(c)(4), 289 (with ss. 60, 101(1), 171, 201(3))
C113Sch. 10 modified (29.4.1996) by Finance Act 1996 (c. 8), s. 116(3)
C114Sch. 10 continued (6.4.2003 with effect in accordance with s. 723(1) of the affecting Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), s. 418(3) (with Sch. 7)
Limitations on contractual obligations of participantsU.K.
1(1)M190Any obligation placed on the participant by virtue of paragraph 2(2) of Schedule 9 shall not prevent the participant from—U.K.
(a)directing the trustees to accept an offer for any of his shares (“”) if the acceptance or agreement will result in a new holding being equated with the original shares for the purposes of capital gains tax; or
(b)directing the trustees to agree to a transaction affecting his shares or such of them as are of a particular class, if the transaction would be entered into pursuant to a compromise, arrangement or scheme applicable to or affecting—
(i)all the ordinary share capital of the company in question or, as the case may be, all the shares of the class in question; or
(ii)all the shares, or all the shares of the class in question, which are held by a class of shareholders identified otherwise than by reference to their employment or their participation in an approved scheme; or
(c)directing the trustees to accept an offer of cash, with or without other assets, for his shares if the offer forms part of a general offer which is made to holders of shares of the same class as his or of shares in the same company and which is made in the first instance on a condition such that if it is satisfied the person making the offer will have control of that company, within the meaning of section 416; or
[F2911(cc)directing the trustees to accept an offer of a qualifying corporate bond, whether alone or with cash or other assets or both, for his shares if the offer forms part of a general offer which is made as mentioned in paragraph (c) above; or]
(d)agreeing after the expiry of the period of retention to sell the beneficial interest in his shares to the trustees for the same consideration as, in accordance with sub-paragraph (d) of paragraph 2(2) of Schedule 9, would be required to be obtained for the shares themselves.
(2)M191No obligation placed on the participant by virtue of paragraph 2(2)(c) of Schedule 9 shall be construed as binding his personal representatives to pay any sum to the trustees.
(3)M192If, in breach of his obligation under paragraph 2(2)(b) of Schedule 9 a participant assigns, charges or otherwise disposes of the beneficial interest in any of his shares, then, as respects those shares, he shall be treated for the purposes of the relevant provisions as if at the time they were appropriated to him he was ineligible to participate in the scheme; and paragraph 6 below shall apply accordingly.
[F2912(4)In sub-paragraph (1)(cc) above “qualifying corporate bond” shall be construed in accordance with section 117 of the 1992 Act.]
Textual Amendments
F2911Sch. 10 para. 1(1)(cc) inserted (with effect in accordance with s. 101(7) of the amending Act) by Finance Act 1994 (c. 9), s. 101(2)
F2912Sch. 10 para. 1(4) inserted (with effect in accordance with s. 101(7) of the amending Act) by Finance Act 1994 (c. 9), s. 101(3)
Marginal Citations
M190Source—1978 s.54(2); 1979 Sch.7
M191Source—1978 s.54(1A); 1980 s.46(2)
M192Source—1978 s.54(3)
The period of retentionU.K.
2U.K.M193For the purposes of any of the relevant provisions, “the period of retention”, in relation to any of a participant’s shares, means the period beginning on the date on which they are appropriated to him and ending on the second anniversary of that date or, if it is earlier—
(a)the date on which the participant ceases to be a director or employee of the grantor or, in the case of a group scheme, a participating company by reason of injury or disability or on account of his being dismissed by reason of redundancy, within the meaning of [F2913the Employment Rights Act 1996] or the [F2914Employment Rights (Northern Ireland) Order 1996]; or
(b)the date on which the participant reaches [F2915the relevant age]; or
(c)the date of the participant’s death; [F2916or]
(d)in a case where the participant’s shares are redeemable shares in a workers’ cooperative, the date on which the participant ceases to be employed by, or by a subsidiary of, the cooperative.
For the purposes of sub-paragraph (a) above, in the case of a group scheme, the participant shall not be treated as ceasing to be a director or employee of a participating company until such time as he is no longer a director or employee of any of the participating companies.
[F2917In this paragraph, the reference to the relevant age is a reference, in the case of a scheme approved before the day on which the Finance Act 1991 was passed, [F2918in the case of a man, to the age of 65, and in the case of a woman, to the age of 60] and, in the case of a scheme approved on or after that day, to the specified age.]
Textual Amendments
F2913Words in Sch. 10 para. 2 substituted (22.8.1996) by Employment Rights Act 1996 (c. 18), s. 243, Sch. 1 para. 35(4)(b)
F2914Words in Sch. 10 para. 2 substituted (24.9.1996) by The Employment Rights (Northern Ireland) Order 1996 (S.I. 1996/1919 (N.I. 16)), art. 1(2), Sch. 1 (with Sch. 2)
F2915Words in Sch. 10 para. 2(b) substituted by Finance Act 1991 (c. 31, SIF 63:1), s. 38(3)
F2916Word at the end of Sch. 10 para. 2(c) inserted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 9
F2917Words in Sch. 10 para. 2 inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 38(3)
F2918Words in Sch. 10 para. 2 substituted (19.7.1995) by Pensions Act 1995 (c. 26), ss. 126, 180(2)(a), Sch. 4 para. 12(b), s. 178(3)
Marginal Citations
M193Source—1978 s.54(4), (5); 1980 s.46(3); 1986 s.24(3)
The appropriate percentageU.K.
3[F2919(1)For the purposes of any of the relevant provisions [F2920under which an amount counts as employment income of an individual] by reason of the occurrence of an event relating to any of his shares, the “appropriate percentage” in relation to those shares is 100 per cent., unless sub-paragraph (2) below applies.U.K.
(2)Where the individual—
(a)ceases to be a director or employee of the grantor or, in the case of a group scheme, a participating company as mentioned in paragraph 2(a) above, or
(b)reaches the relevant age,
before the event occurs, the “appropriate percentage” is 50 per cent., unless paragraph 6(4) below applies.]
Textual Amendments
F2919Sch. 10 para. 3 substituted (with effect in accordance with s. 107(3) of the amending Act) by Finance Act 1996 (c. 8), s. 117(1)
F2920Words in Sch. 10 paras. 3(1), 6(4) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 113(2) (with Sch. 7)
[F29213A(1)In paragraph 3 above the reference to the relevant age shall be construed as follows.U.K.
(2)Where the scheme is approved before 25th July 1991 and the event occurs before 30th November 1993, the relevant age is
[F2922(a)in the case of a man, 65, and
(b)in the case of a woman, 60.]
(3)Where—
(a)the scheme is approved before 25th July 1991,
(b)the event occurs on or after 30th November 1993,
(c)the scheme defines the period of retention by reference to the age of 60 for both men and women, and
(d)the reference to that age is incorporated in the definition by virtue of an alteration approved by the Board under paragraph 4 of Schedule 9 before the event occurs,
the relevant age is 60.
(4)Where—
(a)the scheme is approved before 25th July 1991,
(b)the event occurs on or after 30th November 1993, and
(c)sub-paragraph (3) above does not apply,
the relevant age is [F2923in the case of a man, 65, and in the case of a woman, 60.]
(5)Where the scheme is approved on or after 25th July 1991, the relevant age is the specified age.]
Textual Amendments
F2921Sch. 10 para. 3A inserted (3.5.1994) by Finance Act 1994 (c. 9), s. 100(3)
F2922Words in Sch. 10 para. 3A(2) substituted (19.7.1995) by Pensions Act 1995 (c. 26), s. 180(2)(a), Sch. 4 para. 12(c)
F2923Words in Sch. 10 para. 3A(4) substituted (19.7.1995) by Pensions Act 1995 (c. 26), s. 180(2)(a), Sch. 4 para. 12(d)
Capital receiptsU.K.
4(1)M194Money or money’s worth is not a capital receipt for the purposes of section 186(3) if or, as the case may be, to the extent that—U.K.
(a)it constitutes income in the hands of the recipient for the purposes of income tax; or
(b)it consists of the proceeds of a disposal falling within section 186(4); or
(c)it consists of new shares within the meaning of paragraph 5 below.
(2)If, pursuant to a direction given by or on behalf of the participant or any person in whom the beneficial interest in the participant’s shares is for the time being vested, the trustees—
(a)dispose of some of the rights arising under a rights issue, as defined in section 186(8), and
(b)use the proceeds of that disposal to exercise other such rights,
the money or money’s worth which constitutes the proceeds of that disposal is not a capital receipt for the purposes of section 186(3).
(3)If, apart from this sub-paragraph, the amount or value of a capital receipt would exceed the sum which, immediately before the entitlement to the receipt arose, was the locked-in value of the shares to which the receipt is referable, section 186(3) shall have effect as if the amount or value of the receipt were equal to that locked-in value.
(4)Section 186(3) does not apply in relation to a capital receipt if the entitlement to it arises after the death of the participant to whose shares it is referable.
Marginal Citations
M194Source—1978 s.56(2)-(5)
Company reconstructionsU.K.
5(1)M195This paragraph applies where there occurs in relation to any of a participant’s shares (“the original holding”) a transaction which results in a new holding being equated with the original holding for the purposes of capital gains tax; and any such transaction is referred to below as a “company reconstruction”.U.K.
(2)Where an issue of shares of any of the following descriptions (in respect of which a charge to income tax arises) is made as part of a company reconstruction, those shares shall be treated for the purposes of this paragraph as not forming part of the new holding, that is to say—
(a)redeemable shares or securities issued as mentioned in [F2924condition C or D in section 1000(1) of CTA 2010];
(b)share capital issued in circumstances such that [F2925section 1022 of CTA 2010] applies; and
(c)share capital to which [F2926section 1049 of CTA 2010] applies.
(3)In this paragraph—
“”, in relation to any new shares, means those shares in respect of which the new shares are issued or which the new shares otherwise represent;
“” means shares comprised in the new holding which were issued in respect of, or otherwise represent, shares comprised in the original holding; and
“original holding” has the meaning given by sub-paragraph (1) above.
(4)Subject to the following provisions of this paragraph, in relation to a profit sharing scheme, references in the relevant provisions to a participant’s shares shall be construed, after the time of the company reconstruction, as being or, as the case may be, as including references to any new shares, and for the purposes of the relevant provisions—
(a)a company reconstruction shall be treated as not involving a disposal of shares comprised in the original holding;
(b)the date on which any new shares are to be treated as having been appropriated to the participant shall be that on which the corresponding shares were appropriated; and
(c)the conditions in paragraphs 10 to 12 and 14 of Schedule 9 shall be treated as fulfilled with respect to any new shares if they were (or were treated as) fulfilled with respect to the corresponding shares.
(5)In relation to shares comprised in the new holding, section 186(5) shall apply as if the references in that subsection to the initial market value of the shares were references to their locked-in value immediately after the company reconstruction, which shall be determined as follows—
(a)ascertain the aggregate amount of locked-in value immediately before the reconstruction of those shares comprised in the original holding which had at that time the same locked-in value; and
(b)distribute that amountpro rata among—
(i)such of those shares as remain in the new holding, and
(ii)any new shares in relation to which those shares are the corresponding shares, according to their market value immediately after the date of their reconstruction;
and section 186(5)(a) shall apply only to capital receipts after the date of the reconstruction.
(6)For the purposes of the relevant provisions if, as part of a company reconstruction, trustees become entitled to a capital receipt, their entitlement to the capital receipt shall be taken to arise before the new holding comes into being and, for the purposes of sub-paragraph (5) above, before the date on which the locked-in value of any shares comprised in the original holding falls to be ascertained.
(7)In the context of a new holding, any reference in this paragraph to shares includes securities and rights of any description which form part of the new holding for the purposes of Chapter II of Part IV of the [F29271992] Act.
Textual Amendments
F2924Words in Sch. 10 para. 5(2)(a) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 138(a) (with Sch. 2)
F2925Words in Sch. 10 para. 5(2)(b) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 138(b) (with Sch. 2)
F2926Words in Sch. 10 para. 5(2)(c) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 138(c) (with Sch. 2)
F2927Word in Sch. 10 para. 5(7) substituted (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(58) (with ss. 60, 101(1), 171, 201(3))
Marginal Citations
M195Source—1978 s.57; 1979(C) Sch.7
[F29285A(1)Paragraph 5(2) to (6) above apply where there occurs in relation to any of a participant’s shares (“the original holding”) a relevant transaction which would result in a new holding being equated with the original holding for the purposes of capital gains tax, were it not for the fact that what would be the new holding consists of or includes a qualifying corporate bond; and “relevant transaction” here means a transaction mentioned in Chapter II of Part IV of the 1992 Act.U.K.
(2)In paragraph 5(2) to (6) above as applied by this paragraph—
(a)references to a company reconstruction are to the transaction referred to in sub-paragraph (1) above;
(b)references to the new holding are to what would be the new holding were it not for the fact mentioned in sub-paragraph (1) above;
(c)references to the original holding shall be construed in accordance with sub-paragraph (1) above (and not paragraph 5(1));
(d)references to shares, in the context of the new holding, include securities and rights of any description which form part of the new holding.
(3)In sub-paragraph (1) above “qualifying corporate bond” shall be construed in accordance with section 117 of the 1992 Act.]
Textual Amendments
F2928Sch. 10 para. 5A inserted (with effect in accordance with s. 101(8) of the amending Act) by Finance Act 1994 (c. 9), s. 101(4) (with s. 101(13))
Excess or unauthorised sharesU.K.
6(1)M196This paragraph applies in any case where—U.K.
(a)the total amount of the initial market value of all the shares which are appropriated to an individual in any one year of assessment (whether under a single approved profit sharing scheme or under two or more such schemes) exceeds the relevant amount; or
(b)the trustees of an approved profit sharing scheme appropriate shares to an individual at a time when he is ineligible to participate in the scheme by virtue of paragraph 8 or 35 of Schedule 9.
(2)In this paragraph—
“” means any share which caused the relevant amount to be exceeded and any share appropriated after that amount was exceeded; and
“” means any share appropriated as mentioned in sub-paragraph (1)(b) above.
(3)For the purposes of sub-paragraph (1)(a) above, if a number of shares is appropriated to an individual at the same time under two or more approved profit sharing schemes, the same proportion of the shares appropriated at that time under each scheme shall be regarded as being appropriated before the relevant amount is exceeded.
(4)For the purposes of any of the relevant provisions [F2929under which an amount counts as employment income of an individual] by reason of the occurrence of an event relating to any of his shares—
(a)the appropriate percentage in relation to excess or unauthorised shares shall in every case be 100 per cent.; and
(b)without prejudice to section 187(8), the event shall be treated as relating to shares which are not excess or unauthorised shares before shares which are.
(5)Excess or unauthorised shares which have not been disposed of before the release date or, if it is earlier, the date of the death of the participant whose shares they are, shall be treated for the purposes of the relevant provisions as having been disposed of by the trustees immediately before the release date or, as the case may require, the date of the participant’s death, for a consideration equal to their market value at that time.
(6)The locked-in value at any time of any excess or unauthorised shares shall be their market value at that time.
(7)Where there has been a company reconstruction to which paragraph 5 above applies, a new share (within the meaning of that paragraph) shall be treated as an excess or unauthorised share if the corresponding share (within the meaning of that paragraph) or, if there was more than one corresponding share, each of them was an excess or unauthorised share.
Textual Amendments
F2929Words in Sch. 10 paras. 3(1), 6(4) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 113(2) (with Sch. 7)
Marginal Citations
M196Source—1978 s.58; 1983 s.25(1)
P.A.Y.E. deduction of taxU.K.
7(1)M197Subject to sub-paragraphs (4) and (5) below, where the trustees of an approved profit sharing scheme receive a sum of money which constitutes (or forms part of)—U.K.
(a)the proceeds of a disposal of shares falling within section 186(4), or
(b)a capital receipt,
in respect of which [F2930an amount counts as employment income of the participant] in accordance with section 186, the trustees shall pay out of that sum of money to the company specified in sub-paragraph (3) below an amount equal to that on which income tax is so payable; and the company shall then pay over that amount to the participant but in so doing shall make a P.A.Y.E. deduction.
(2)Where a participant disposes of his beneficial interest in any of his shares to the trustees of the scheme and the trustees are deemed by virtue of section 186(9) to have disposed of the shares in question, this paragraph shall apply as if the consideration payable by the trustees to the participant on the disposal had been received by the trustees as the proceeds of disposal of shares falling within section 186(4).
(3)The company to which the payment mentioned in sub-paragraph (1) above is to be made is the company—
(a)of which the participant is an employee or director at the time the trustees receive the sum of money referred to in that sub-paragraph, and
(b)whose employees are at that time eligible (subject to the terms of the scheme and Schedule 9) to be participants in the approved profit sharing scheme concerned,
and if there is more than one company which falls within paragraphs (a) and (b) above, such one of those companies as the Board may direct.
(4)Where the trustees of an approved profit sharing scheme receive a sum of money to which sub-paragraph (1) above applies but—
(a)there is no company which falls within paragraphs (a) and (b) of sub-paragraph (3) above, or
(b)the Board is of opinion that it is impracticable for the company which falls within those paragraphs (or, as the case may be, any of them) to make a P.A.Y.E. deduction and accordingly direct that this sub-paragraph shall apply,
then, in paying over to the participant the proceeds of the disposal or the capital receipt, the trustees shall make a P.A.Y.E. deduction in respect of an amount equal to that on which income tax is payable as mentioned in sub-paragraph (1) above as if the participant were a former employee of the trustees.
(5)Where the trustees of an approved profit sharing scheme receive a sum of money to which sub-paragraph (1) above applies and the Board direct that this sub-paragraph shall apply—
(a)the trustees shall make the payment mentioned in that sub-paragraph to the company specified in the Board’s direction; and
(b)that company shall pay over that amount to the participant but in so doing shall make a P.A.Y.E. deduction, and for that purpose if the participant is not an employee of that company he shall be treated as a former employee;
but no such direction shall be given except with the consent of the trustees, the company or companies (if any) specified in sub-paragraph (3) above and the company specified in the direction.
(6)Where, in accordance with this paragraph any person is required to make a P.A.Y.E. deduction in respect of any amount, that amount shall be treated for the purposes of [F2931section 684 of ITEPA 2003 (PAYE regulations) and PAYE regulations as PAYE income payable to the recipient], and, accordingly, such deduction shall be made as is required by those regulations.
(7)Where, in connection with a transfer of a participant’s shares to which sub-paragraph (c) of paragraph 2(2) of Schedule 9 applies, the trustees receive such a sum as is referred to in that sub-paragraph, that sum shall be treated for the purposes of the Income Tax Acts—
(a)as a sum deducted by the trustees pursuant to a requirement to make a P.A.Y.E. deduction under sub-paragraph (4) above; and
(b)as referable to the income tax F2932. . . which, as a result of the transfer, [F2933is charged on the participant] by virtue of section 186(4).
(8)Unless the Board otherwise direct, in the application of this paragraph to a sum of money which constitutes or forms part of the proceeds of a disposal of, or a capital receipt referable to, excess or unauthorised shares (within the meaning of paragraph 6 above), the trustees shall determine the amount of the payment mentioned in sub-paragraph (1) above or, as the case may be, the amount of the P.A.Y.E. deduction to be made under sub-paragraph (4) above as if the shares were not excess or unauthorised shares.
Textual Amendments
F2930Words in Sch. 10 para. 7(1) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 113(3)(a) (with Sch. 7)
F2931Words in Sch. 10 para. 7(6) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 113(3)(b) (with Sch. 7)
F2932Word in Sch. 10 para. 7(7)(b) repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 113(3)(c)(i), Sch 8 Pt. 1 (with Sch. 7)
F2933Words in Sch. 10 para. 7(7)(b) substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 113(3)(c)(ii) (with Sch. 7)
Marginal Citations
M197Source—1978 s.59; 1980 s.46(8); 1987 Sch.15 11(3)
[F2934F2935Schedule 11]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2934Sch. 11 substituted (with effect in accordance with s. 58(4) of the amending Act) by Finance Act 1998 (c. 36), s. 58(2), Sch. 9 Pt. 1
F2935Sch. 11 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 114, Sch 8 Pt. 1 (with Sch. 7)
F2937F2937[F2938SCHEDULE 11A]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F2937Sch. 11A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 115, Sch 8 Pt. 1 (with Sch. 7)
F2938Sch. 11A inserted (27.7.1993) by Finance Act 1993 (c. 34), s. 76, Sch. 5 para. 2
F2997F2997SCHEDULE 12U.K.
Textual Amendments
F2997Sch. 12 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 116, Sch 8 Pt. 1 (with Sch. 7)
[F2999 Amount of emoluments]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Emoluments eligible for reliefU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Qualifying periodsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .SupplementaryU.K.
4M202For the purposes of this Schedule a person shall not be regarded as absent from the United Kingdom on any day unless he is so absent at the end of it.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F3015F3015[F3016SCHEDULE 12AAU.K. MILEAGE ALLOWANCES: INTERPRETATION]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3015Sch. 12AA repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 117, Sch. 8 Pt. 1 (with Sch. 7)
F3016Sch. 12AA inserted (with effect in accordance with s. 57(4) of the amending Act) by Finance Act 2001 (c. 9), s. 57(2), Sch. 12 Pt. 1
F3017F3017[F3018Schedule 12AU.K. Ordinary commuting and private travel]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3017Sch. 12A repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 118, Sch. 8 Pt. 1 (with Sch. 7)
F3019F3019 SCHEDULE 13U.K.
Textual Amendments
F3019Sch. 13 repealed (with effect in accordance with Sch. 3 para. 41(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 41(1), Sch. 27 Pt. 3(2), Note
Duty to make returnsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Contents of returnU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Payment of taxU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .International headquarters companiesU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Receipt of franked investment income after payment of advance corporation taxU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Receipt of foreign income dividends after payment of advance corporation taxU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Claims for set-off in respect of franked investment income received by a companyU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .6(1)Where a claim has been made under paragraph 5 above no proceedings for collecting tax which would fall to be discharged if the claim were allowed shall be instituted pending the final determination of the claim, but this sub-paragraph shall not affect the date when the tax is due.
(2)When the claim is finally determined any tax underpaid in consequence of sub-paragraph (1) above shall be paid.
(3)Where proceedings are instituted for collecting tax assessed, or interest on tax assessed, under any provision of this Schedule, effect shall not be given to any claim made after the institution of the proceedings so as to affect or delay the collection or recovery of the tax charged by the assessment or of interest thereon, until the claim has been finally determined.
(4)When the claim is finally determined any tax overpaid in consequence of sub-paragraph (3) above shall be repaid.
(5)References in this paragraph to proceedings for the collection of tax include references to proceedings by way of distraint or poinding for tax.
Claims for set-off in respect of foreign income dividends received by a companyU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Qualifying distributions which are not payments and payments of uncertain natureU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Amended return where company becomes aware of an errorU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Items included in errorU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Qualifying distribution made otherwise than in an accounting periodU.K.
9Where a company makes a qualifying distribution on a date which does not fall within an accounting period the company shall make a return of that distribution within 14 days from that date, and the advance corporation tax in respect thereof shall be due at the time by which the return is to be made, except where the distribution is not a payment in which case the advance corporation tax shall be assessed on the company.
Manufactured foreign income dividendsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Assessments and due date of taxU.K.
10(1)All the provisions of the Corporation Tax Acts as to the time within which an assessment may be made, so far as they refer or relate to the accounting period for which an assessment is made, or the accounting period to which an assessment relates, shall apply in relation to an assessment under this Schedule notwithstanding that, under this Schedule, the assessment may be said to relate to a quarter or other period which is not an accounting period; and the provisions of [F3057section 36] of the Management Act as to the circumstances in which an assessment may be made out of time shall apply accordingly on the footing that any such assessment relates to the accounting period in which the quarter or other period ends or, in the case of an assessment under paragraph 9 above, to an accounting period ending on the date on which the distribution is made.
(2)Advance corporation tax assessed on a company under this Schedule shall be due within 14 days after the issue of the notice of assessment (unless due earlier under paragraph 3(1) or 9 above).
(3)Sub-paragraph (2) above has effect subject to any appeal against the assessment, but no such appeal shall affect the date when tax is due under paragraph 3(1) or 9 above.
(4)On the determination of an appeal against an assessment under this Schedule any tax overpaid shall be repaid.
(5)Any tax assessable under any one or more of the provisions of this Schedule may be included in one assessment if the tax so included is all due on the same date.
F3058F3058[F3059SCHEDULE 13AU.K. Surrenders of advance corporation tax]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3058Sch. 13A repealed (with effect in accordance with Sch. 3 para. 42(2) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 42(1), Sch. 27 Pt. 3(2), Note
F3059Sch. 13A inserted (with effect in accordance with Sch. 25 para. 3 of the amending Act) by Finance Act 1996 (c. 8), s. 139, Sch. 25 para. 2
F3065F3065[F3066Schedule 13BU.K. Children’s Tax Credit]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3065Sch. 13B repealed (6.4.2003) by Tax Credits Act 2002 (c. 21), s. 61, Sch. 6; S.I. 2003/962, art. 2(3)(e), Sch. 1 (with arts. 3-5)
Section 266(12).
SCHEDULE 14U.K. PROVISIONS ANCILLARY TO SECTION 266
PART IU.K. MODIFICATION OF SECTION 266 IN CERTAIN CASES
[F3075Spouses and civil partners]U.K.
Textual Amendments
F3075Cross-heading preceding Sch. 14 para. 1 substituted (5.12.2005) by virtue of The Tax and Civil Partnership Regulations 2005 (S.I. 2005/3229), regs. 1(1), 101(3)
1[F3076(1)In section 266—U.K.
(a)references to an individual's spouse include any person who—
(i)was that individual's spouse at the time the insurance or contract was made, or
(ii)became that individual's spouse after the insurance or contract was made,
unless the marriage was dissolved before 6th April 1979, and
(b)references to an individual's civil partner include any person who—
(i)was that individual's civil partner at the time the insurance or contract was made, or
(ii)became that individual's civil partner after the insurance or contract was made.]
[F3077(1A)But an individual is entitled to relief by virtue of sub-paragraph (1)(a)(ii) or (b)(ii) only in respect of premiums payable after the date on which the person in question became that individual's spouse or civil partner.]
F3078(2). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
F3078(3). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3076Sch. 14 para. 1(1) substituted (1.4.2011 with effect in accordance with art. 6(3) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2011 (S.I. 2011/1037), arts. 1, 6(1)
F3077Sch. 14 para. 1(1A) inserted (1.4.2011 with effect in accordance with art. 6(3) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2011 (S.I. 2011/1037), arts. 1, 6(2)
F3078Sch. 14 para. 1(2)(3) repealed by Finance Act 1988 (c. 39), Sch.14 Part VIII, Note 6
Premiums payable to friendly societies and industrial assurance companiesU.K.
2(1)M205 This paragraph applies to—U.K.
(a)a policy issued in the course of an industrial assurance business; and
(b)a policy issued by a [F3079friendly society] in the course of tax exempt life or endowment business (as defined in section 466).
[F3080(1A)In sub-paragraph (1)(a) “industrial assurance business” means any industrial assurance business within the meaning given by—
(a)section 1(2) of the Industrial Assurance Act 1923, or
(b)Article 3(1) of the Industrial Assurance (Northern Ireland) Order 1979,
which was carried on before 1 December 2001.]
(2)Subject to paragraph 3(2) below, if a policy to which this paragraph applies was issued before the passing of the Finance Act 1976 (29th July 1976), section 266 shall have effect in relation to it as if subsections (2)(b), (3)(a), (b) and (d) were omitted; and if a policy to which this paragraph applies was issued after the passing of that Act, subsection (2)(b) of that section shall have effect in relation to it as if it permitted the insurance to be on the life of the individual’s parent or grandparent or, subject to sub-paragraph (3) below, on the life of the individual’s child or grandchild.
(3)Relief may be given in respect of premiums under a policy of insurance on the life of an individual’s child or grandchild which was or is issued after the passing of the Finance Act 1976 (29th July 1976), as if subsection (3)(d) of section 266 were omitted, but may be given only if the annual amount of the premiums, together with that of any relevant premiums, does not exceed £52 if the policy was issued in respect of an insurance made before 25th March 1982 or £64 in any other case.
(4)For the purposes of sub-paragraph (3) above, a relevant premium, in relation to an insurance made at any time on the life of an individual’s child or grandchild, is any premium under a policy of insurance on the same life, where the insurance is made at the same time or earlier, whether it is made by the individual or any other person.
(5)In this paragraph “child” includes a step-child and an illegitimate child whose parents have married each other after his birth, and “grandchild”, “parent” and “grandparent” have corresponding meanings.
Textual Amendments
F3079Words in Sch. 14 para. 2(1)(b) substituted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para. 18(2); S.I. 1993/236, art.2
F3080Sch. 14 para. 2(1A) inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 232(2) (with Sch. 2)
Marginal Citations
M205Source—1976 Sch.4 11; 1979/1576; 1982 s.35(2), (4); 1970 s.10
3(1)M206 Where a policy is issued or a contract is made by a [F3081friendly society] or a policy to which paragraph 2 above applies is issued by an industrial assurance company, section 266(4), (5) and (8) shall apply in relation to premiums payable under the policy or contract subject to the following provisions of this paragraph.U.K.
(2)References to the deductions authorised under section 266(5) shall be construed as including references to any amount retained by or refunded to the person paying the premium under any scheme made by the society or company in accordance with regulations made under this paragraph.
(3)The appropriate authority may make regulations authorising—
(a)the adoption by [F3081friendly societies] and industrial assurance companies of any prescribed scheme for securing that in the case of policies or contracts to which the scheme applies amounts equal to [F308212.5 per cent.] of the premiums payable are retained by or refunded to the person paying the premiums or that, in the case of such policies or contracts issued or made before 6th April 1979, the amounts expressed as the amounts of the premiums payable are treated as amounts arrived at by deducting [F308212.5 per cent.] from the amounts payable and that the amounts of the capital sums assured or guaranteed are treated as correspondingly increased; or
(b)the adoption by any such society or company of any special scheme for that purpose which may, in such circumstances as may be prescribed, be approved by the appropriate authority.
(4)Increases treated as made in pursuance of regulations under this paragraph shall not be treated as variations of a policy or contract and shall be disregarded for the purposes of paragraph 2(3) above, sections 268(6), 460, 461(1) and 464 of, and paragraph 7 of Schedule 15 to, this Act F3083 . . . .
(5)The regulations may include such adaptations and modifications of the enactments relating to friendly societies or industrial assurance companies and such other incidental and supplementary provisions as appear to the appropriate authority necessary or expedient for the purpose of enabling such societies or companies to adopt the schemes authorised by the regulations.
(6)Subsections (4), (5) and (7) to (11) of section 6 of the M207Decimal Currency Act 1969 shall, with the necessary modifications, apply in relation to regulations made under this paragraph.
Textual Amendments
F3081Words in Sch. 14 para. 3(1)(3)(a) substituted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para. 18(2)(3); S.I. 1993/236, art.2
F3082Words in Sch. 14 para. 3(3)(a) substituted (6.4.1989) by Finance Act 1988 (c. 39), s. 29
F3083Words in Sch. 14 para. 3(4) repealed (with effect in accordance with s. 173 of the repealing Act) by Finance Act 1989 (c. 26), Sch. 17 Pt. 9, Note
Marginal Citations
M206Source—1976 Sch.4 13; 1978 Sch.3 7; 1980 s.29(2)(c); 1987 Sch.15 9
PART IIU.K. SUPPLEMENTARY PROVISIONS AS TO RELIEF UNDER SECTION 266
4(1)M208Where it appears to the Board that the relief (if any) to which a person is entitled under section 266 has been exceeded or might be exceeded unless the premiums payable by him under any policy or contract were paid in full, they may, by notice to that person and to the person to whom the payments are made, exclude the application of subsection (5) of that section in relation to any payments due or made after such date as may be specified in the notice and before such date as may be specified in a further notice to those persons.U.K.
(2)Where the application of section 266(5) is so excluded in relation to any payments, the relief (if any) to which the person by whom the payments are made is entitled under section 266 shall be given to him under paragraph 6 below.
Marginal Citations
M208Source—1976 Sch.4 14; 1978 Sch.3 2, 8
5U.K.M209Where a person is entitled to relief under section 266 in respect of a payment to which [F3084section 386 of ITEPA 2003 (payments to non-approved retirement benefits schemes)] applies, section 266(5) shall not apply but the like relief shall be given to him under paragraph 6 below.
Textual Amendments
F3084Words in Sch. 14 para. 5 substituted (6.4.2003 with effect in accordance with s. 723(1) of the amending Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 6 para. 119 (with Sch. 7)
Marginal Citations
M209Source—1976 Sch.4 14A; 1978 Sch.3 9
6(1)M210Where in any year of assessment the relief to which a person is entitled under section 266 F3085. . . has not been fully given in accordance with that section and the preceding provisions of this Schedule, he may claim relief for the difference, and relief for the difference shall then be given by a payment made by the Board or by discharge or repayment of tax or partly in one such manner and partly in another; and where relief so given to any person exceeds that to which he is entitled under section 266, he shall be liable to make good the excess and an inspector may make such assessments as may in his judgment be required for recovering the excess.U.K.
(2)The Management Act shall apply to any assessment under this paragraph as if it were an assessment to tax for the year of assessment in which the relief was given F3086. . . .
Textual Amendments
F3085Words in Sch. 14 para. 6(1) omitted (with effect in accordance with Sch. 1 para. 7 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 1 para. 5
F3086Words in Sch. 14 para. 6(2) repealed (with effect in accordance with Sch. 18 para. 17(5) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 18 para. 11(2), Sch. 41 Pt. 5(8), Note
Modifications etc. (not altering text)
C137Sch. 14 para. 6 restricted by Finance Act 2012 (c. 14), Sch. 39 para. 24
Marginal Citations
M210Source—1976 Sch.4 15
7(1)M211The Board may make regulations for carrying into effect section 266(4), (5), (8) and (9) and the preceding provisions of this Schedule [F3087and paragraphs 9 and 10 of Schedule 15] (“the relevant provisions”).U.K.
(2)Regulations under this paragraph may, without prejudice to the generality of sub-paragraph (1) above, provide—
(a)for the furnishing of such information by persons by whom premiums are payable as may be necessary for determining whether they are entitled to make deductions under section 266(5) and for excluding the operation of that subsection in relation to payments made by persons who fail to comply with the regulations;
(b)for rounding to a multiple of one penny any payment which, after a deduction authorised under section 266(5), is not such a multiple;
(c)for the manner in which claims for the recovery of any sum under section 266(5)(b) may be made;
(d)for the furnishing of such information by persons by or to whom premiums are payable as appears to the Board necessary for deciding such claims and for exercising their powers under paragraph 4 or 6 above; and
(e)for requiring persons to whom premiums are paid to make available for inspection by an officer authorised by the Board such books and other documents in their possession or under their control as may reasonably be required for the purposes of determining whether any information given by those persons for the purposes of the relevant provisions is correct and complete.
(3)The following provisions of the Management Act, that is to say—
[F3088(a)section 29(1)(c) (excessive relief) as it has effect apart from section 29(2) to (10) of that Act;]
(b)section 30 (recovery of tax repaid in consequence of fraud or negligence etc.) [F3089apart from subsection (1B)];
(c)[F3090section 86] (interest); and
(d)section 95 (incorrect return or accounts);
[F3091shall apply in relation to an amount which is paid to any person by the Board as an amount recoverable by virtue of section 266(5)(b) but to which that person is not entitled as if it were income tax which ought not to have been repaid and, where that amount was claimed by that person, as if it had been repaid as respects a chargeable period as a relief which was not due.]
[F3092(4)In the application of section 86 of the Management Act by virtue of sub-paragraph (3) above in relation to sums due and payable by virtue of an assessment made for the whole or part of a year of assessment (“the relevant year of assessment”) under section 29(1)(c) or 30 of that Act, as applied by that sub-paragraph, the relevant date—
(a)is 1st January in the relevant year of assessment in a case where the person falling within section 266(5)(b) has made a relevant interim claim; and
(b)in any other case, is the later of the following dates, that is to say—
(i)1st January in the relevant year of assessment; or
(ii)the date of the making of the payment by the Board which gives rise to the assessment.
(5)In this paragraph—
“financial year”, in relation to any person, means a financial year of that person for the purposes of the relevant regulations;
“interim claim” means an interim claim within the meaning of the relevant regulations;
“relevant interim claim” means, in relation to an assessment made for a period coterminous with, or falling wholly within, a person’s financial year, an interim claim made for a period falling wholly or partly within that financial year;
“the relevant regulations” means regulations made under sub-paragraph (1) above.]
Textual Amendments
F3087Words in Sch. 14 para. 7(1) repealed (with effect in accordance with s. 55(1)-(5) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(7), Note (as s. 55 of that repealing Act is amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
F3088Sch. 14 para. 7(3)(a) substituted (with effect in accordance with Sch. 18 para. 17(1)(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 11(3)(a)
F3089Words in Sch. 14 para. 7(3)(b) inserted (with effect in accordance with Sch. 18 para. 17(1)(2) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 11(3)(b)
F3090Words in Sch. 14 para. 7(3)(c) substituted (with effect in accordance with Sch. 18 para. 17(3)(4) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 11(3)(c)
F3091Words in Sch. 14 para. 7(3) substituted (with effect in accordance with Sch. 18 para. 17(8) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 11(3)(d)
F3092Sch. 14 para. 7(4)(5) added (with effect in accordance with Sch. 18 para. 17(3)(4) of the amending Act) by Finance Act 1996 (c. 8), Sch. 18 para. 11(4)
Marginal Citations
M211Source—1976 Sch.4 16; 1978 Sch.3 10
8(1)M212A policy of life insurance issued in respect of an insurance made on or before 19th March 1968 shall be treated for the purposes of section 266(3)(b) as issued in respect of one made after that date if varied after that date so as to increase the benefits secured or to extend the term of the insurance.U.K.
(2)A variation effected before the end of the year 1968 shall be disregarded for the purposes of sub-paragraph (1) above if its only effect was to bring into conformity with paragraph 2 of Schedule 9 to the Finance Act 1968 (qualifying conditions for endowment policies, and now re-enacted as paragraph 2 of Schedule 15 to this Act) a policy previously conforming therewith except as respects the amount guaranteed on death, and no increase was made in the premiums payable under the policy.
(3)M213A policy which was issued in the course of industrial assurance business in respect of an insurance made after 13th March 1984 shall be treated for the purposes of section 266(3)(c) and this paragraph as issued in respect of an insurance made on or before that date if—
(a)the proposal form for the policy was completed on or before that date; and
(b)on or before 31st March 1984 the policy was prepared for issue by the company or society concerned; and
(c)on or before 31st March 1984 and in accordance with the normal business practice of the company or society a permanent record of the preparation of the policy was made in any book or by any other means kept or instituted by the company or society for the purpose.
[F3093(3A)In sub-paragraph (3) “industrial assurance business” means any industrial assurance business within the meaning given by—
(a)section 1(2) of the Industrial Assurance Act 1923, or
(b)Article 3(1) of the Industrial Assurance (Northern Ireland) Order 1979,
which was carried on before 1 December 2001.]
(4)[F3094Subject to sub-paragraph (8) below,] for the purposes of section 266(3)(c) a policy of life insurance which was issued in respect of an insurance made on or before 13th March 1984 shall be treated as issued in respect of an insurance made after that date if the policy is varied after that date so as to increase the benefits secured or to extend the term of the insurance.
(5)If a policy of life insurance which was issued as mentioned in sub-paragraph (4) above confers on the person to whom it was issued an option to have another policy substituted for it or to have any of its terms changed, then, for the purposes of that sub-paragraph and section 266(3)(c), any change in the terms of the policy which is made in pursuance of the option shall be deemed to be a variation of the policy.
(6)In any case where—
(a)one policy is replaced by another in such circumstances that the provisions of paragraph 20 of Schedule 15 apply; and
(b)the earlier policy was issued in respect of an insurance made on or before 13th March 1984; and
(c)the later policy confers on the life or lives assured thereby benefits which are substantially equivalent to those which would have been enjoyed by the life or lives assured under the earlier policy, if that policy had continued in force;
then, for the purposes of section 266(3)(c), the insurance in respect of which the later policy is issued shall be deemed to have been made before 13th March 1984; and in this sub-paragraph “the earlier policy” and “the later policy” have the same meaning as in paragraph 20 of Schedule 15.
(7)In any case where—
(a)there is a substitution of policies falling within paragraph 25(1) or (3) of Schedule 15; and
(b)the old policy was issued in respect of an insurance made on or before 13th March 1984;
then, for the purposes of section 266(3)(c), the insurance in respect of which the new policy is issued shall be deemed to have been made before 13th March 1984; and in this sub-paragraph “the old policy” and “the new policy” have the same meaning as in paragraph 17 of Schedule 15.
[F3095(8)Sub-paragraph (4) above does not apply in the case of a variation so as to increase the benefits secured, if the variation is made—
(a)on or after such day as the Board may by order appoint, and
(b)in consideration of a change in the method of payment of premiums from collection by a person collecting premiums from house to house to payment by a different method.]
Subordinate Legislation Made
P3Sch. 14 para. 8(8)(a) power exercised: 1.12.2001 appointed by S.I. 2001/3643, art. 2(b)
Textual Amendments
F3093Sch. 14 para. 8(3A) inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 232(4) (with Sch. 2)
F3094Words in Sch. 14 para. 8(4) inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 167(5)
F3095Sch. 14 para. 8(8) inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 167(6)
Marginal Citations
M212Source—1970 s.19(5)
M213Source—1984 s.72(2)-(4), (6), (7)
Section 267.
SCHEDULE 15U.K. QUALIFYING POLICIES
Modifications etc. (not altering text)
C138Sch. 15 modified by Finance Act 1991 (c. 31, SIF 63:1), s. 50, Sch. 9 para. 5 (2)
C139Sch. 15 modified (1.5.1995) by Finance Act 1995 (c. 4), Sch. 10 para. 4(2)(3)
[F3096PART A1 U.K.Premium limit for qualifying policies
Textual Amendments
F3096Sch. 15 Pt. A1 inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 2
Premium limit for qualifying policies to apply from 6 April 2013U.K.
A1(1)Sub-paragraph (2) applies if—U.K.
(a)an event falling within sub-paragraph (3) occurs,
(b)apart from sub-paragraph (2), the policy to which the event relates would be a qualifying policy after the event, and
(c)an individual who is a beneficiary under that policy is in breach of the premium limit for qualifying policies.
(2)That policy is not to be a qualifying policy after the event.
(3)The events falling within this sub-paragraph are—
(a)the issue of a policy in respect of an insurance made on or after 6 April 2013;
(b)the variation of a policy on or after 6 April 2013 where as a result of the variation—
(i)the period over which premiums are payable under the policy is or could be lengthened, or
(ii)the total amount of the premiums payable under the policy in any relevant period is or could be increased,
or both;
(c)the assignment on or after 6 April 2013 of any rights, or any share in any rights, under a policy where the assignment falls within paragraph B2(3)(c) to (g) or (5) below;
(d)a deceased beneficiary event on or after 6 April 2013;
(e)the conditions in paragraph 24(3) below being fulfilled for the first time in respect of a new non-resident policy where—
(i)the conditions are fulfilled for the first time on or after 6 April 2013, and
(ii)but for the conditions being fulfilled, the policy could not be a qualifying policy because of paragraph 24(2).
(4)An event does not fall within sub-paragraph (3) if—
(a)the policy to which the event relates is—
(i)a protected policy,
(ii)a restricted relief qualifying policy, or
(iii)a pure protection policy,
(b)the event is the issue of a policy which is a new policy in relation to an earlier policy where—
(i)the new policy is issued in substitution for the earlier policy (and not on its maturity), and
(ii)the life assured under the new policy is different to the life assured under the earlier policy but that is the only difference to what the position would have been had the earlier policy continued to run,
(c)paragraph 20ZA below applies to a policy and the event is the reinstatement or replacement of the policy as mentioned in paragraph 20ZA(4),
(d)the event is the issue or variation of a policy in relation to which paragraph 29 of Schedule 39 to the Finance Act 2012 applies, or
(e)the event is an assignment falling within paragraph B2(3)(e) below where the assignment is a mortgage endowment assignment.
(5)In sub-paragraph (3)(b)(ii) “relevant period” means any period of 12 months beginning at or after the time of the variation.
(6)A variation is to be ignored for the purposes of sub-paragraph (3)(b) if its effect is nullified before the end of the period of 3 months after the day on which the variation occurs.
(7)Sub-paragraph (4)(a)(i) does not apply in the case of an event mentioned in sub-paragraph (3)(e).
(8)Sub-paragraph (4)(a)(ii) does not apply in the case of—
(a)an event mentioned in sub-paragraph (3)(c) or (d) occurring in relation to a restricted relief qualifying policy (“the assigned policy”),
(b)any subsequent event relating to the assigned policy, or
(c)any event relating to—
(i)a later policy which is a new policy in relation to the assigned policy, or
(ii)any policy which is a new policy in relation to the later policy,
and so on.
(9)In the case of an event mentioned in sub-paragraph (3)(b), sub-paragraph (4)(a)(iii) applies only if the policy is a pure protection policy both before and after the variation.
(10)This paragraph is to be applied after all other provisions of this Schedule relevant to the question of whether a policy is a qualifying policy after an event have been applied.
Restricted relief qualifying policiesU.K.
A2(1)Sub-paragraph (2) applies if—U.K.
(a)an event falling within sub-paragraph (3) occurs,
(b)the policy to which the event relates is a qualifying policy after the event, and
(c)an individual who is a beneficiary under that policy is in breach of the premium limit for qualifying policies.
(2)That policy is to be a restricted relief qualifying policy after the event.
(3)The events falling within this sub-paragraph are—
(a)a premium limit event in relation to a protected policy on or after 21 March 2012;
(b)the issue of a policy as mentioned in paragraph A4(2)(b) below if, assuming that the substitution of the protected policy were instead a variation of that policy, there would be a premium limit event in relation to that policy;
(c)the assignment on or after 6 April 2013 of any rights, or any share in any rights, under a protected policy where the assignment falls within paragraph B2(3)(c) to (g) or (5) below;
(d)a deceased beneficiary event on or after 6 April 2013 where the policy in question is a protected policy;
(e)the issue of a policy in respect of an insurance made on or after 21 March 2012 but before 6 April 2013 otherwise than as mentioned in paragraph A4(2)(b) below;
(f)the variation of a policy, other than a protected policy, on or after 21 March 2012 but before 6 April 2013 where as a result of the variation—
(i)the period over which premiums are payable under the policy is or could be lengthened, or
(ii)the total amount of the premiums payable under the policy in any relevant period is or could be increased,
or both;
(g)the conditions in either sub-paragraph (3) or sub-paragraph (4) of paragraph 24 below being fulfilled for the first time in respect of a new non-resident policy where—
(i)the conditions are fulfilled for the first time on or after 21 March 2012 but before 6 April 2013, and
(ii)but for the conditions being fulfilled, the policy could not be a qualifying policy because of sub-paragraph (2) of paragraph 24.
(4)An event does not fall within sub-paragraph (3) if—
(a)the policy to which the event relates is a pure protection policy,
(b)the event is the issue of a policy which is a new policy in relation to an earlier policy where—
(i)the new policy is issued in substitution for the earlier policy (and not on its maturity), and
(ii)the life assured under the new policy is different to the life assured under the earlier policy but that is the only difference to what the position would have been had the earlier policy continued to run,
(c)paragraph 20ZA below applies to a policy and the event is the reinstatement or replacement of the policy as mentioned in paragraph 20ZA(4),
(d)the event is the issue or variation of a policy in relation to which paragraph 29 of Schedule 39 to the Finance Act 2012 applies, or
(e)the event is an assignment falling within paragraph B2(3)(e) below where the assignment is a mortgage endowment assignment.
(5)In sub-paragraph (3)(f)(ii) “relevant period” means any period of 12 months beginning at or after the time of the variation.
(6)A premium limit event or a variation is to be ignored for the purposes of sub-paragraph (3)(a) or (f) if its effect is nullified before 6 July 2013.
(7)In the case of a premium limit event which occurs on or after 6 April 2013, in sub-paragraph (6) the reference to 6 July 2013 is to be read as a reference to the end of the period of 3 months after the day on which the premium limit event occurs.
(8)In the case of an event mentioned in sub-paragraph (3)(a) or (f), sub-paragraph (4)(a) applies only if the policy is a pure protection policy both before and after the premium limit event or variation.
(9)A “premium limit event” occurs in relation to a protected policy if—
(a)the policy is varied or a relevant option is exercised so as to change the terms of the policy, and
(b)as a result of the variation or exercise of the relevant option—
(i)the period over which premiums are payable under the policy is or could be lengthened, or
(ii)the total amount of the premiums payable under the policy in any relevant period is or could be increased,
or both.
(10)A “premium limit event” also occurs in relation to a protected policy if on or after 6 April 2013—
(a)the policy is varied or a relevant option is exercised so as to change the terms of the policy, and
(b)as a result of the variation or exercise of the relevant option—
(i)the period over which premiums are payable under the policy is or could be shortened, or
(ii)the total amount of the premiums payable under the policy in any relevant period is or could be decreased,
or both.
(11)In sub-paragraphs (9)(b)(ii) and (10)(b)(ii) “relevant period” means any period of 12 months beginning at or after the time of the variation or exercise of the relevant option.
(12)The variation of, or exercise of a relevant option under, a protected policy is not a premium limit event in relation to the policy if—
(a)the policy secures a capital sum payable either—
(i)on survival for a specified term, or
(ii)on earlier death or on earlier death or disability,
(b)the policy is issued and maintained for the sole purpose of ensuring that the borrower under an interest-only mortgage will have sufficient funds to repay the principal lent under the mortgage, and
(c)the policy is varied, or the relevant option is exercised, for that sole purpose.
(13)In sub-paragraph (3)(g) references to paragraph 24 below are to that paragraph as it has effect before the appointed date for the purposes of section 55 of the Finance Act 1995.
(14)A qualifying policy which is a new policy in relation to an earlier policy is a restricted relief qualifying policy if the earlier policy is a restricted relief qualifying policy.
(15)A policy which is a restricted relief qualifying policy remains a restricted relief qualifying policy so long as it is a qualifying policy.
(16)Paragraph A1 above is to be ignored in determining for the purposes of sub-paragraph (14) or (15) if a policy is a qualifying policy. This is subject to paragraph A1(8).
(17)For further provision about restricted relief qualifying policies, see sections 463A to 463D of ITTOIA 2005.
The premium limit for qualifying policiesU.K.
A3(1)For the purposes of paragraphs A1(1)(c) and A2(1)(c) above an individual is in breach of the premium limit for qualifying policies if the total amount of the premiums payable under relevant policies in any relevant period—U.K.
(a)exceeds £3,600, or
(b)could exceed £3,600 as a result of—
(i)the exercise of any one or more relevant options conferred by one or more relevant policies, or
(ii)so far as not covered by sub-paragraph (i), the application of one or more terms of one or more relevant policies relating to increases in premiums.
(2)For the purposes of sub-paragraph (1)—
(a)so much of a premium payable under a relevant policy as is charged on the grounds that an exceptional risk of death or disability is involved is to be left out of account in determining the premiums payable under the policy,
(b)so much of the first premium payable under a relevant policy the liability for the payment of which—
(i)is discharged in accordance with paragraph 15(2) below, or
(ii)in the case of a policy in relation to which paragraph 3 below applies, is discharged under a provision of the policy falling within paragraph 3(4)(c),
is to be left out of account in determining the premiums payable under the policy (subject to sub-paragraph (3) below),
(c)in determining the premiums payable under a relevant policy any provision for the waiver of premiums by reason of a person's disability is to be ignored, and
(d)“relevant period” means any period of 12 months beginning at or after the time when the event falling within paragraph A1(3) or A2(3) above (“the relevant event”) occurs.
(3)The maximum amount that may be left out of account under sub-paragraph (2)(b) in the case of a relevant policy is—
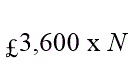
where N is the number of complete years for which ran—
a
the other policy involved, or
b
if there is more than one other policy involved, the policy which ran for the most number of complete years.
(4)For the purposes of this paragraph the following are “relevant policies”—
(a)the policy to which the relevant event relates, and
(b)any other policy—
(i)which is a qualifying policy, and
(ii)under which the individual is a beneficiary.
(5)But neither a protected policy nor a pure protection policy is to be a relevant policy by virtue of sub-paragraph (4)(b).
(6)Sub-paragraph (7) applies if this paragraph is to be applied in the case of an individual in consequence of two or more events occurring at the same time (including where one or more of the events falls within paragraph A1(3) above and one or more of the events falls within paragraph A2(3) above).
(7)For the purpose of applying this paragraph in the case of the individual in consequence of any of the events, sub-paragraph (4)(a) has effect as if the reference to the policy to which the relevant event relates were a reference to all the policies to which the events, taken together, relate.
(8)But sub-paragraph (7) does not apply, and sub-paragraph (9) applies instead, if—
(a)all the policies in question are policies issued by the same issuer, and
(b)each of them has an unique identifier in a series of unique identifiers which the issuer gives to policies issued by it.
(9)For the purpose of applying this paragraph in the case of the individual in consequence of any of the events, an event relating to a policy (“policy A”) is treated as occurring before an event relating to another policy (“policy B”) if, in the issuer's series of unique identifiers, policy A's unique identifier comes before policy B's unique identifier.
Protected policiesU.K.
A4(1)This paragraph applies for the purposes of this Part of this Schedule.U.K.
(2)A policy is “protected” if—
(a)it is issued in respect of an insurance made before 21 March 2012, or
(b)it is issued in respect of an insurance made on or after 21 March 2012 where—
(i)it is a new policy in relation to an earlier policy,
(ii)it is issued in substitution for the earlier policy (and not on its maturity), and
(iii)the earlier policy is a protected policy (whether by virtue of paragraph (a) or this paragraph).
(3)A policy which is protected ceases to be protected if it becomes a restricted relief qualifying policy.
(4)A policy issued as mentioned in sub-paragraph (2)(b) is not protected if—
(a)its issue is an event falling within paragraph A2(3) above, and
(b)after that event it is a restricted relief qualifying policy.
How to determine if an individual is a beneficiary under a policyU.K.
A5(1)This paragraph applies for the purposes of this Part of this Schedule in determining if an individual is a beneficiary under a policy.U.K.
(2)An individual is a beneficiary under a policy if the individual beneficially owns—
(a)any rights under the policy, or
(b)any share in any rights under the policy.
(3)An individual is a beneficiary under a policy if—
(a)any rights under the policy are, or any share in any rights under the policy is, held on non-charitable trusts created by the individual, and
(b)those rights are, or that share is, not beneficially owned by any individual.
(4)The following provisions of ITTOIA 2005 apply for the purposes of sub-paragraph (3)(a)—
(a)section 465(6), and
(b)the definition of “non-charitable trust” in section 545(1).
(5)An individual is a beneficiary under a policy if—
(a)any rights under the policy are, or any share in any rights under the policy is, held as security for a debt of the individual, and
(b)those rights are, or that share is, not beneficially owned by any individual.
Further definitionsU.K.
A6(1)In this Part of this Schedule—U.K.
(a)“new policy” has the meaning given in paragraph 17 below,
(b)references to the variation of a policy are to a variation in relation to which paragraph 18 below applies,
(c)“pure protection policy” means a policy—
(i)which has no surrender value and is not capable of acquiring a surrender value, or
(ii)under which the benefits payable cannot exceed the amount of the premiums paid except on death or in respect of disability, and
(d)“relevant option”, in relation to a policy, means an option conferred by the policy on the person to whom it is issued to have another policy substituted for it or to have any of its terms changed.
(2)For the purposes of this Part of this Schedule a “deceased beneficiary event” occurs if, in connection with the death of an individual (“D”) who was a beneficiary under a policy, an individual (“B”) becomes a beneficiary under that policy by reference (wholly or partly) to any rights, or to any share in any rights, by reference to which D was a beneficiary (wholly or partly).
For this purpose, it does not matter if B is already a beneficiary under the policy.
(3)For the purposes of this Part of this Schedule an assignment is a “mortgage endowment assignment” if—
(a)the policy to which the assignment relates secures a capital sum payable either—
(i)on survival for a specified term, or
(ii)on earlier death or on earlier death or disability,
(b)the policy is issued and maintained for the sole purpose of ensuring that the borrower under an interest-only mortgage will have sufficient funds to repay the principal lent under the mortgage, and
(c)when the assignment occurs, it is intended that the policy will continue to be maintained for that sole purpose.]
PART IU.K. QUALIFYING CONDITIONS
[F3097RULES FOR QUALIFYING POLICIESU.K.
Textual Amendments
F3097Sch. 15 paras. B1-B3, cross-headings and preceding heading inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 3
Rights to be beneficially owned by individuals onlyU.K.
B1(1)Sub-paragraph (2) applies in relation to a policy issued in respect of an insurance made on or after 6 April 2013.U.K.
(2)In order for the policy to be a qualifying policy, when it is issued all the rights under it must be beneficially owned by (and only by)—
(a)one individual, or
(b)two or more individuals taken together.
(This is the case notwithstanding any other provision of this Schedule.)
(3)Sub-paragraph (2) does not apply if the policy is protected.
(4)A policy is “protected” if it is a new policy (as defined in paragraph 17 below) in relation to—
(a)a policy issued in respect of an insurance made before 21 March 2012, or
(b)a policy which is protected (whether by virtue of paragraph (a) or this paragraph).
AssignmentsU.K.
B2(1)Sub-paragraph (2) applies if any rights under a qualifying policy are, or any share in any rights under a qualifying policy is, assigned on or after 6 April 2013.U.K.
(2)The policy is not to be a qualifying policy after the assignment (notwithstanding any other provision of this Schedule).
(3)Sub-paragraph (2) does not apply if—
(a)the assignment is from an individual by way of security for a debt of the individual,
(b)the assignment is to an individual on the discharge of a debt of the individual secured by the rights or share,
(c)the assignment is from an individual to the individual's spouse or civil partner,
(d)the assignment is to an individual in pursuance of an order made by a court,
(e)the assignment is to an individual in pursuance of a legally enforceable obligation relating to a divorce or the dissolution of a civil partnership,
(f)the assignment is from an individual and, as a result of the assignment, the rights assigned are, or the share assigned is, held on trusts created by the individual,
(g)the assignment is to an individual and, as a result of the assignment, the rights assigned are, or the share assigned is, no longer held on trusts, or
(h)the assignment—
(i)is to the personal representatives of a deceased individual, or
(ii)is to an individual where, as a result of the assignment, a deceased beneficiary event (see paragraph A6(2) above) occurs.
(4)Section 465(6) of ITTOIA 2005 applies for the purposes of sub-paragraph (3)(f).
(5)The Commissioners for Her Majesty's Revenue and Customs may by regulations provide that sub-paragraph (2) does not apply if prescribed conditions are met in relation to the assignment.
“Prescribed” means prescribed by the regulations.
(6)Regulations under sub-paragraph (5) may—
(a)make different provision for different cases or circumstances, and
(b)contain incidental, supplementary, consequential, transitional, transitory or saving provision.
(7)See paragraphs A1 and A2 above which may apply in consequence of an assignment falling within sub-paragraph (3) or (5).
Required statementsU.K.
B3(1)Sub-paragraph (2) applies if any of the following events occurs—U.K.
(a)the issue of a policy in respect of an insurance made on or after 6 April 2013;
(b)the variation of a policy on or after 6 April 2013 where paragraph 18 below applies in relation to the variation and as a result of the variation—
(i)the period over which premiums are payable under the policy is or could be lengthened, or
(ii)the total amount of the premiums payable under the policy in any relevant period is or could be increased,
or both;
(c)a premium limit event in relation to a protected policy on or after 6 April 2013 (see paragraph A2(9) to (12) above);
(d)an event on or after 6 April 2013 which would be a premium limit event in relation to a protected policy but for paragraph A2(12) above;
(e)the assignment on or after 6 April 2013 of any rights, or any share in any rights, under a policy where the assignment falls within paragraph B2(3)(c) to (g) or (5) above;
(f)a deceased beneficiary event (see paragraph A6(2) above) on or after 6 April 2013;
(g)the conditions in paragraph 24(3) below being fulfilled for the first time in respect of a new non-resident policy where—
(i)the conditions are fulfilled for the first time on or after 6 April 2013, and
(ii)but for the conditions being fulfilled, the policy could not be a qualifying policy because of paragraph 24(2).
(2)Each individual who is a beneficiary under the policy must, before the end of the statement period, make to the issuer of the policy a statement dealing with the prescribed matters.
(3)If an individual does not comply with sub-paragraph (2) the policy is not to be a qualifying policy after the event (notwithstanding any other provision of this Schedule).
(4)In sub-paragraph (1)(b)(ii) “relevant period” means any period of 12 months beginning at or after the time of the variation.
(5)Sub-paragraph (2)—
(a)does not apply in the case of an event mentioned in sub-paragraph (1)(a), (e), (f) or (g) if the policy is a pure protection policy, and
(b)does not apply in the case of an event mentioned in sub-paragraph (1)(b), (c) or (d) if the policy is a pure protection policy both before and after the event.
“Pure protection policy” has the meaning given by paragraph A6(1)(c) above.
(6)Sub-paragraph (2) does not apply in the case of an event mentioned in sub-paragraph (1)(e) where the assignment falls within paragraph B2(3)(e) above and is a mortgage endowment assignment.
“Mortgage endowment assignment” is to be read in accordance with paragraph A6(3) above.
(7)The Commissioners for Her Majesty's Revenue and Customs may by regulations provide that an individual is not required to comply with sub-paragraph (2) if prescribed conditions are met.
“Prescribed” means prescribed by the regulations.
(8)Accordingly, if by virtue of regulations under sub-paragraph (7) an individual is not required to comply with sub-paragraph (2), sub-paragraph (3) does not apply because that individual does not comply with sub-paragraph (2).
(9)In sub-paragraph (2)—
(a)the reference to an individual who is a beneficiary under the policy is to be read in accordance with paragraph A5 above,
(b)“the statement period” means—
(i)the period of 3 months after the day on which the event occurs, or
(ii)if the event occurs before the day on which the first regulations under paragraph (c) below come into force, the period of 3 months after that day,
or such longer period as an officer of Revenue and Customs may allow, and
(c)“prescribed” means prescribed by regulations made by the Commissioners for Her Majesty's Revenue and Customs.
(10)An officer of Revenue and Customs may allow a longer period for the purposes of sub-paragraph (9)(b) only if—
(a)the individual in question has made a request in writing to an officer of Revenue and Customs for a longer period to be allowed, and
(b)such an officer is satisfied—
(i)that there is a reasonable excuse for the required statement not having been made within the period mentioned in sub-paragraph (9)(b)(i) or (ii), and
(ii)that the request under paragraph (a) was made without unreasonable delay after the reasonable excuse ceased.
(11)Sub-paragraph (12) applies in relation to a policy if the obligations under the policy of its issuer are at any time the obligations of another person (“the transferee”) to whom there has been a transfer of the whole or any part of a business previously carried on by the issuer.
(12)In relation to that time, in sub-paragraph (2) the reference to the issuer of the policy is to be read as a reference to the transferee.
(13)Regulations under sub-paragraph (7) or (9)(c) may—
(a)make different provision for different cases or circumstances, and
(b)contain incidental, supplementary, consequential, transitional, transitory or saving provision.]
General rules applicable to whole life and term assurancesU.K.
1(1)M214 Subject to the following provisions of this Part of this Schedule, if a policy secures a capital sum which is payable only on death, or one payable either on death or on earlier disability, it is a qualifying policy if—U.K.
(a)it satisfies the conditions appropriate to it under sub-paragraphs (2) to (5) below, and
(b)except to the extent permitted by sub-paragraph (7) below, it does not secure any other benefits.
(2)If the capital sum referred to in sub-paragraph (1) above is payable whenever the event in question happens, or if it happens at any time during the life of a specified person—
(a)the premiums under the policy must be payable at yearly or shorter intervals, and either—
(i)until the happening of the event or, as the case may require, until the happening of the event or the earlier death of the specified person, or
(ii)until the time referred to in sub-paragraph (i) above or the earlier expiry of a specified period ending not earlier than ten years after the making of the insurance; and
(b)the total premiums payable in any period of 12 months must not exceed—
(i)twice the amount of the total premiums payable in any other such period, or
(ii)one-eighth of the total premiums which would be payable if the policy were to continue in force for a period of ten years from the making of the insurance, or, in a case falling within sub-paragraph (ii) of paragraph (a) above, until the end of the period referred to in that sub-paragraph.
(3)If the capital sum referred to in sub-paragraph (1) above is payable only if the event in question happens before the expiry of a specified term ending more than ten years after the making of the insurance, or only if it happens both before the expiry of such a term and during the life of a specified person—
(a)the premiums under the policy must be payable at yearly or shorter intervals, and either—
(i)until the happening of the event or the earlier expiry of that term or, as the case may require, until the happening of the event or, if earlier, the expiry of the term or the death of the specified person, or
(ii)as in sub-paragraph (i) above, but with the substitution for references to the term of references to a specified shorter period being one ending not earlier than ten years after the making of the insurance or, if sooner, the expiry of three-quarters of that term; and
(b)the total premiums payable in any period of 12 months must not exceed—
(i)twice the amount of the total premiums payable in any other such period, or
(ii)one-eighth of the total premiums which would be payable if the policy were to continue in force for the term referred to in sub-paragraph (i) of paragraph (a) above, or, as the case may require, for the shorter period referred to in sub-paragraph (ii) of that paragraph.
(4)If the capital sum referred to in sub-paragraph (1) above is payable only if the event in question happens before the expiry of a specified term ending not more than ten years after the making of the insurance, or only if it happens both before the expiry of such a term and during the life of a specified person, the policy must provide that any payment made by reason of its surrender during the period is not to exceed the total premiums previously paid under the policy.
(5)Except where—
(a)the capital sum referred to in sub-paragraph (1) above is payable only in the circumstances mentioned in sub-paragraph (3) or (4) above; and
(b)the policy does not provide for any payment on the surrender in whole or in part of the rights conferred by it; and
(c)the specified term mentioned in sub-paragraph (3) or, as the case may be, (4) above ends at or before the time when the person whose life is insured attains the age of 75 years;
the capital sum, so far as payable on death, must not be less than 75 per cent. of the total premiums that would be payable if the death occurred at the age of 75 years, the age being, if the sum is payable on the death of the first to die of two persons, that of the older of them, if on the death of the survivor of them, that of the younger of them, and in any other case, that of the person on whose death it is payable; and if the policy does not secure a capital sum in the event of death occurring before the age of 16 or some lower age, it must not provide for the payment in that event of an amount exceeding the total premiums previously paid under it.
(6)M215 In determining for the purposes of sub-paragraph (5) above whether a capital sum is less than 75 per cent. of the total premiums, any amount included in the premiums by reason of their being payable otherwise than annually shall be disregarded, [F3098and if the policy provides for payment otherwise than annually without providing for the amount of the premiums if they are paid annually,] 10 per cent. of the premiums payable under the policy shall be treated as so included.
(7)M216 Notwithstanding sub-paragraph (1)(b) above, if a policy secures a capital sum payable only on death, it may also secure benefits (including benefits of a capital nature) to be provided in the event of a person’s disability; and no policy is to be regarded for the purposes of that provision as securing other benefits by reason only of the fact that—
(a)it confers a right to participate in profits, or
(b)it provides for a payment on the surrender in whole or in part of the rights conferred by the policy, or
(c)it gives an option to receive payments by way of annuity, or
(d)it makes provision for the waiver of premiums by reason of a person’s disability, or for the effecting of a further insurance or insurances without the production of evidence of insurability.
(8)In applying sub-paragraph (2) or (3) above to any policy—
(a)no account shall be taken of any provision for the waiver of premiums by reason of a person’s disability, and
(b)if the term of the policy runs from a date earlier, but not more than three months earlier, than the making of the insurance, the insurance shall be treated as having been made on that date, and any premium paid in respect of the period before the making of the insurance, or in respect of that period and a subsequent period, as having been payable on that date.
(9)References in this paragraph to a capital sum payable on any event include references to any capital sum, or series of capital sums, payable by reason of that event but where what is so payable is either an amount consisting of one sum or an amount made up of two or more sums, the 75 per cent. mentioned in sub-paragraph (5) above shall be compared with the smaller or smallest amount so payable; and a policy secures a capital sum payable either on death or on disability notwithstanding that the amount payable may vary with the event.
(10)M217 In relation to any policy issued in respect of an insurance made before 1st April 1976 this paragraph shall have effect—
(a)with the omission of sub-paragraphs (5) and (6) and in sub-paragraph (9) the words “but where what is so payable is either an amount consisting of one sum or an amount made up of two or more sums, the 75 per cent. mentioned in sub-paragraph (5) above shall be compared with the smaller or smallest amount so payable”; and
(b)with the substitution, for sub-paragraph (7)(b), of—
“(b)it carries a guaranteed surrender value;”.
Textual Amendments
F3098Words in Sch. 15 para. 1(6) substituted (with effect as mentioned in s. 167(12) of the amending Act) by Finance Act 1996 (c. 8), s. 167(7)(a); S.I. 2001/3643, art. 2(a)
Marginal Citations
M214Source—1970 Sch.1 1(1)-(4A); 1975 Sch.2 4(2), (3)
M215Source—1975 Sch.2 4(4)
M216Source—1970 Sch.1 1(5)-(7); 1975 Sch.2 4(5), (6)
M217Source—1975 Sch.2 4(1)
General rules applicable to endowment assurancesU.K.
2(1)M218 Subject to the following provisions of this Part of this Schedule, a policy which secures a capital sum payable either on survival for a specified term or on earlier death, or earlier death or disability, including a policy securing the sum on death only if occurring after the attainment of a specified age not exceeding 16, is a qualifying policy if it satisfies the following conditions—U.K.
(a)the term must be one ending not earlier than ten years after the making of the insurance;
(b)premiums must be payable under the policy at yearly or shorter intervals, and—
(i)until the happening of the event in question; or
(ii)until the happening of that event, or the earlier expiry of a specified period shorter than the term but also ending not earlier than ten years after the making of the insurance; or
(iii)if the policy is to lapse on the death of a specified person, until one of those times or the policy’s earlier lapse;
(c)the total premiums payable under the policy in any period of 12 months must not exceed—
(i)twice the amount of the total premiums payable in any other such period, or
(ii)one-eighth of the total premiums which would be payable if the policy were to run for the specified term;
(d)the policy—
(i)must guarantee that the capital sum payable on death, or on death occurring after the attainment of a specified age not exceeding 16, will, whenever that event may happen, be equal to 75 per cent. at least of the total premiums which would be payable if the policy were to run for that term, disregarding any amounts included in those premiums by reason of their being payable otherwise than annually, except that if, at the beginning of that term, the age of the person concerned exceeds 55 years, the capital sum so guaranteed may, for each year of the excess, be less by 2 per cent. of that total than 75 per cent. thereof, the person concerned being, if the capital sum is payable on the death of the first to die of two persons, the older of them, if on the death of the survivor of them, the younger of them and in any other case the person on whose death it is payable; and
(ii)if it is a policy which does not secure a capital sum in the event of death before the attainment of a specified age not exceeding 16, must not provide for the payment in that event of an amount exceeding the total premiums previously paid thereunder; and
(e)the policy must not secure the provision (except by surrender in whole or in part of the rights conferred by the policy) at any time before the happening of the event in question of any benefit of a capital nature other than a payment falling within paragraph (d)(ii) above, or benefits attributable to a right to participate in profits or arising by reason of a person’s disability.
(2)For the purposes of sub-paragraph (1)(d)(i) above, 10 per cent. of the premiums payable under any policy [F3099that provides for the payment of premiums otherwise than annually without providing for the amount of the premiums if they are paid annually,] shall be treated as attributable to the fact that they are not paid annually.
(3)Sub-paragraphs (8) and (9) of paragraph 1 above shall, with any necessary modifications, have effect for the purposes of this paragraph as they have effect for the purposes of that paragraph.
(4)M219 In relation to any policy issued in respect of an insurance made before 1st April 1976 this paragraph shall have effect with the omission in sub-paragraph (1)(d)(i) of the words from “except that if” to the end, and in sub-paragraph (1)(e) of the words “in whole or in part of the rights conferred by the policy”.
Textual Amendments
F3099Words in Sch. 15 para. 2(2) substituted (with effect as mentioned in s. 167(12) of the amending Act) by Finance Act 1996 (c. 8), s. 167(7)(b); S.I. 2001/3643, art. 2(a)
Marginal Citations
M218Source—1970 Sch.1 2; 1975 Sch.2 4(7), (8)
M219Source—1975 Sch.2 4(1)
Special types of policyU.K.
(i)Friendly Society policiesU.K.
3(1)M220 Paragraphs 1 and 2 above do not apply to a policy issued by a [F3100friendly society] in the course of [F3101exempt BLAGAB or eligible PHI business] in respect of an insurance made or varied on or after 19th March 1985, but such a policy shall not be a qualifying policy unless—U.K.
(a)in the case of a policy for the assurance of a gross sum or annuity, the conditions in sub-paragraph (2) are fulfilled with respect to it; and
(b)in the case of a policy for the assurance of a gross sum, the conditions in sub-paragraphs (5) to (11) below are fulfilled with respect to it; F3102 . . .
F3102(c). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(2)The conditions referred to in sub-paragraph (1) above are as follows—
(a)subject to sub-paragraph (3) below, the period (the “term” of the policy) between—
(i)the making of the insurance or, where the contract provides for the term to begin on a date not more than three months earlier than the making of the insurance, that date, and
(ii)the time when the gross sum assured is payable (or, as the case may be, when the first instalment of the annuity is payable),
shall be not less than ten years, and must not, on any contingency other than the death, or retirement on grounds of ill health, of the person liable to pay the premiums or whose life is insured, become less than ten years;
(b)subject to sub-paragraph (4) below, the premiums payable under the policy shall be premiums of equal or rateable amounts payable at yearly or shorter intervals over the whole term of the policy of assurance, or over the whole term of the policy of assurance apart from any period after the person liable to pay the premiums or whose life is insured attains a specified age, being an age which he will attain at a time not less than ten years after the beginning of the term of the policy of assurance;
F3103(c). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)Notwithstanding sub-paragraph (2)(a) above, the policy—
(a)may provide for a payment to a person of an age not exceeding 18 years at any time not less than five years from the beginning of the term of the policy if the premium or premiums payable in any period of 12 months in the term of the policy do not exceed £13;
(b)may provide for a payment at any time not less than five years from the beginning of the term of the policy, if it is one of a series of payments falling due at intervals of not less than five years, and the amount of any payment, other than the final payment, does not exceed four-fifths of the premiums paid in the interval before its payment.
For the purposes of paragraph (a) above, if the term begins on a date earlier than the making of the insurance, any premium paid in respect of a period before the making of the insurance, or in respect of that period and a subsequent period, shall be treated as having been payable on that date.
(4)Notwithstanding sub-paragraph (2)(b) above, the policy—
(a)may allow a payment at any time after the expiration of one-half of the term of the policy of assurance, or of ten years from the beginning of the term, whichever is the earlier, being a payment in commutation of the liability to pay premiums falling due after that time;
(b)may allow the person liable to pay the premiums to commute any liability for premiums where he ceases to reside in the United Kingdom or gives satisfactory proof of intention to emigrate;
(c)may allow any liability for premiums to be discharged in consideration of surrendering a sum which has become payable on the maturity of any other policy of assurance issued by the same friendly society [F3104(or any predecessor of it)] to the person liable to pay the premiums, or to his parent, where that other policy of assurance is issued as part of the friendly society’s [F3101exempt BLAGAB or eligible PHI business]; and
(d)may make provision for the waiver of premiums by reason of a person’s disability.
[F3105(4A)For the purposes of sub-paragraphs (2) and (4) above—
(a)a friendly society formed on the amalgamation of two or more friendly societies is the successor of each of those societies (and each of those societies was a predecessor of the society so formed), and
(b)an incorporated friendly society that was a registered friendly society before its incorporation is the successor of the registered friendly society (and the registered friendly society was the predecessor of the incorporated friendly society).]
(5)Where the policy secures a capital sum which is payable only on death or only on death occurring after the attainment of a specified age not exceeding 16, that capital sum must be not less than 75 per cent. of the total premiums which would be payable if the death of the relevant beneficiary occurred at the age of 75.
(6)Where the policy secures a capital sum which is payable only on survival for a specified term, that capital sum must be not less than 75 per cent. of the total premiums which would be payable if the policy were to run for that term.
(7)Where the policy secures a capital sum which is payable on survival for a specified term or on earlier death, or on earlier death or disability (including a policy securing the sum on death only if occurring after the attainment of a specified age not exceeding 16), the capital sum payable on death, whenever that event occurs, must be not less than 75 per cent. of the total premiums which would be payable if the policy were to run for that term, except that if, at the beginning of that term, the age of the relevant beneficiary exceeds 55, that capital sum may, for each year of the excess, be less by 2 per cent. of that total than 75 per cent. thereof.
(8)For the purposes of sub-paragraphs (5) to (7) above—
(a)“the relevant beneficiary” means—
(i)if the capital sum concerned is payable on the death of the first to die of two persons, the older of them;
(ii)if that capital sum is payable on the death of the survivor of two persons, the younger of them; and
(iii)in any other case, the person on whose death that capital sum is payable; and
(b)in determining the total premiums payable in any circumstances—
(i)where those premiums are payable otherwise than annually, and the policy is issued by [F3106a society other than an old society], there shall be disregarded an amount equal to 10 per cent. of those premiums;
(ii)where the policy is issued by [F3107an old society], there shall be disregarded an amount equal to £10 for each year for which account is taken of those premiums [F3108or, where those premiums are payable otherwise than annually, an amount equal to 10 per cent. of those premiums if that is greater]; F3109. . .
(iii)F3109. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(c)F3109. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(9)If the policy does not secure a capital sum in the event of death occurring before the age of 16 or some lower age, it must not provide for the payment in that event of an amount exceeding the total premiums previously paid under it.
(10)References in this paragraph to a capital sum payable on any event include references to a capital sum or series of capital sums payable by reason of that event, but where what is so payable is either an amount consisting of one sum or an amount made up of two or more sums, any reference in sub-paragraphs (5) to (7) above to 75 per cent. of the total premiums payable in any circumstances shall be compared with the smaller or smallest amount so payable; and for the purposes of those sub-paragraphs a policy secures a capital sum payable either on death or on disability notwithstanding that the amount may vary with the event.
(11)For the purposes of sub-paragraphs (5) to (7) and (10) above, in the case of a policy which provides for any such payments as are referred to in sub-paragraph (3) above (“interim payments”), the amount of the capital sum which is payable on any event shall be taken to be increased—
(a)in the case of a policy which secures such a capital sum as is referred to in sub-paragraph (5) above, by the total of the interim payments which would be payable if the death of the relevant beneficiary (within the meaning of that sub-paragraph) occurred at the age of 75; and
(b)in the case of a policy which secures such a capital sum as is referred to in sub-paragraph (6) or (7) above, by the total of the interim payments which would be payable if the policy were to run for the specified term referred to in that sub-paragraph.
Textual Amendments
F3100Words in Sch. 15 para. 3(1) substituted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para. 19(2); S.I. 1993/236, art.2
F3101Words in Sch. 15 para. 3(1)(4)(c) substituted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(2)(a)
F3102Sch. 15 para. 3(1)(c) and word preceding it repealed by Finance Act 1991 (c. 31, SIF 63:1), ss. 50, 123, Sch. 9 para. 4(1)(2), Sch. 19 Pt. V, Note 7
F3103Sch. 15 para. 3(2)(c) repealed (1.5.1995) by Finance Act 1995 (c. 4), Sch. 10 para. 3, Sch. 29 Pt. 8(6)
F3104Words in Sch. 15 para. 3(2)(c)(4)(c) inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para. 19(3)(4); S.I. 1993/236, art.2
F3105Sch. 15 para. 3(4A) inserted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para. 19(5); S.I. 1993/236, art.2
F3106Words in Sch. 15 para. 3(8)(b)(i) substituted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(2)(b)
F3107Words in Sch. 15 para. 3(8)(b)(ii) substituted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(2)(c)
F3108Words in Sch. 15 para. 3(8)(b)(ii) inserted by Finance Act 1990 (c. 29), s. 49(5)
F3109Sch. 15 para. 3(8)(b)(iii)(c) and word preceding para. (b)(iii) repealed (retrospectively with effect in accordance with s. 172(6) of the repealing Act) by Finance Act 2003 (c. 14), s. 172(3), Sch. 43 Pt. 3(13), Note 3
Marginal Citations
M220Source—1970 ss.334(2)–(4), 337(5)(a), Sch.1 3, 3A; 1984 s.72(a); 1985 s.41(4), (6), Sch.10 Pt.I; 1979/1576
4(1)The provisions of this paragraph have effect notwithstanding anything in paragraph 3 above.U.K.
(2)In determining whether a policy—
(a)which affords provision for sickness or other infirmity (whether bodily or mental), and
(b)which also affords assurance for a gross sum independent of sickness or other infirmity, and
(c)under which not less than 60 per cent. of the amount of the premiums is attributable to the provision referred to in paragraph (a) above,
is a qualifying policy, the conditions referred to in paragraph 3(1)(b) above shall be deemed to be fulfilled with respect to it.
(3)A policy shall cease to be a qualifying policy—
(a)if it falls within sub-paragraph (1) of paragraph 3 above and there is such a variation of its terms that any of the conditions referred to in that sub-paragraph ceases to be fulfilled; or
(b)if—
[F3110(i)it was effected in the course of [F3111the business of effecting or carrying out contracts of insurance which fall within paragraph 1 of Part I or paragraph VI of Part II of Schedule 1 to the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001],]
(ii)it was issued by [F3112a society other than an old society], and
(iii)the rights conferred by it are surrendered in whole or in part.
Textual Amendments
F3110Sch. 15 para. 4(3)(b)(i) substituted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 paras. 19(6), 22; S.I. 1993/236, art. 2
F3111Words in Sch. 15 para. 4(3)(b)(i) substituted (1.12.2001 in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 47(2)
F3112Words in Sch. 15 para. 4(3)(b)(ii) substituted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(3)
5U.K.F3113. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3113Sch. 15 para. 5 omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 13(4)
6(1)M221 A policy which was issued by [F3114any registered friendly society F3115. . . ], or branch of [F3114such a society], in the course of [F3116exempt BLAGAB or eligible PHI business]F3115. . . in respect of insurances made before 19th March 1985 and which has not been varied on or after that date is a qualifying policy notwithstanding that it does not comply with the conditions specified in paragraph 1 or 2 above.U.K.
(2)M222 Notwithstanding paragraphs 3 to 5 or sub-paragraph (1) above, if, on or after 19th March 1985, a person becomes in breach of the limits in [F3117section 160 of the Finance Act 2012], the policy effected by that contract which causes those limits to be exceeded shall not be a qualifying policy; and in any case where—
(a)the limits in that section are exceeded as a result of the aggregation of the sums assured or premiums payable under two or more contracts, and
(b)at a time immediately before one of those contracts was entered into (but not immediately after it was entered into) the sums assured by or, as the case may be, the premiums payable under the contract or contracts which were then in existence did not exceed the limits in that section,
only those policies effected by contracts made after that time shall be treated as causing the limits to be exceeded.
Textual Amendments
F3114Words in Sch. 15 para. 6(1) substituted (19.2.1993) by Finance (No. 2) Act 1992 (c. 48), s. 56, Sch. 9 para. 19(7); S.I. 1993/236, art.2
F3115Words in Sch. 15 para. 6(1) omitted (with effect in accordance with s. 178 of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 18 para. 13(5)(a)(i)
F3116Words in Sch. 15 para. 6(1) substituted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(5)(a)(ii)
F3117Words in Sch. 15 para. 6(2) substituted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(5)(b)
Marginal Citations
M221Source—1970 Sch.1, 3; 1985 s.41(4)
M222Source—FSA 1974 s.64(2B); 1985 s.41(1); 1987 s.30(6)
[F31186AU.K.Any expression—
(a)which is used in any provision made by any of paragraphs 3 to 6, and
(b)which is used in Part 3 of the Finance Act 2012,
has the same meaning in that provision as it has in that Part.]
Textual Amendments
F3118Sch. 15 para. 6A inserted (with effect in accordance with s. 178 of the amending Act) by Finance Act 2012 (c. 14), Sch. 18 para. 13(6)
(ii) Industrial assurance policiesU.K.
7(1)M223 A policy issued in the course of an industrial assurance business, and not constituting a qualifying policy by virtue of paragraph 1 or 2 above, is nevertheless a qualifying policy if—U.K.
(a)the sums guaranteed by the policy, together with those guaranteed at the time the assurance is made by all other policies issued in the course of such a business to the same person and not constituting qualifying policies apart from this paragraph, do not exceed £1,000;
(b)it satisfies the conditions with respect to premiums specified in paragraph 1(2) above;
(c)except by reason of death or surrender, no capital sum other than one falling within paragraph (d) below can become payable under the policy earlier than ten years after the making of the assurance; and
(d)where the policy provides for the making of a series of payments during its term—
(i)the first such payment is due not earlier than five years after the making of the assurance, and the others, except the final payment, at intervals of not less than five years, and
(ii)the amount of any payment, other than the final payment, does not exceed four-fifths of the premiums paid in the interval before its payment; or
(e)the policy was issued before 6th April 1976, or was issued before 6th April 1979 and is in substantially the same form as policies so issued before 6th April 1976.
(2)For the purposes of this paragraph, the sums guaranteed by a policy do not include any bonuses, or in the case of a policy providing for a series of payments during its term, any of those payments except the first, or any sum payable on death during the term by reference to one or more of those payments except so far as that sum is referable to the first such payment.
Marginal Citations
M223Source—1970 Sch.1 4; 1976 Sch.4 12
8U.K.M224 Where a policy issued in respect of an insurance made after 1st April 1976 in the course of an industrial assurance business is not a qualifying policy by virtue of paragraph 1 or 2 above but is a policy with respect to which the conditions in paragraph 7(1)(b) and (c) above are satisfied, it shall be a qualifying policy whether or not the condition in paragraph 7(1)(a) above is satisfied with respect to it; but where that condition is not satisfied, relief under section 266 in respect of premiums paid under the policy shall be given only on such amount (if any) as would have been the amount of those premiums had that condition been satisfied.
Marginal Citations
M224Source—1975 Sch.2 7; 1976 Sch.4 19(4)
[F31198A(1)Paragraphs 7 and 8 above shall have effect in relation to any policy issued on or after the appointed day as if the references to the issue of a policy in the course of an industrial assurance business were references to the issue of a policy by any company in a case in which—U.K.
(a)the company, before that day and in the course of such a business, issued any policy which was a qualifying policy by virtue of either of those paragraphs; and
(b)the policies which on 28th November 1995 were being offered by the company as available to be issued included policies of the same description as the policy issued on or after the appointed day.
(2)In this paragraph “the appointed day” means such day as the Board may by order appoint.]
Subordinate Legislation Made
P4Sch. 15 para. 8A power exercised: 1.12.2001 appointed by S.I. 2001/3643, art. 2(c)
Textual Amendments
F3119Sch. 15 para. 8A inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 167(8)
(iii) Family income policies and mortgage protectionU.K.
9(1)M225 The following provisions apply to any policy which is not a qualifying policy apart from those provisions, and the benefits secured by which consist of or include the payment on or after a person’s death of—U.K.
(a)one capital sum which does not vary according to the date of death, plus a series of capital sums payable if the death occurs during a specified period, or
(b)a capital sum, the amount of which is less if the death occurs in a later part of a specified period than if it occurs in an earlier part of that period.
(2)A policy falling within sub-paragraph (1)(a) above is a qualifying policy if—
(a)it would be one if it did not secure the series of capital sums there referred to, and the premiums payable under the policy were such as would be chargeable if that were in fact the case, and
(b)it would also be one if it secured only that series of sums, and the premiums thereunder were the balance of those actually so payable.
(3)A policy falling within sub-paragraph (1)(b) above is a qualifying policy if—
(a)it would be one if the amount of the capital sum there referred to were equal throughout the period to its smallest amount, and the premiums payable under the policy were such as would be chargeable if that were in fact the case, and
(b)it would also be one if it secured only that capital sum so far as it from time to time exceeds its smallest amount, and the premiums payable thereunder were the balance of those actually so payable.
Marginal Citations
M225Source—1970 Sch.1 5
Other special provisionsU.K.
(i) Short-term assurancesU.K.
10U.K.M226 A policy which secures a capital sum payable only on death or payable either on death or on earlier disability shall not be a qualifying policy if the capital sum is payable only if the event in question happens before the expiry of a specified term ending less than one year after the making of the insurance.
Marginal Citations
M226Source—1976 Sch.4 2, 2A; 1978 Sch.3 4; 1982 s.35(1)
(ii) Personal accident insuranceU.K.
11(1)A policy which evidences a contract of insurance to which sub-paragraph (3) below applies shall not be a qualifying policy unless it also evidences [F3120—U.K.
(a)a contract of insurance on human life; or
(b)a contract to pay annuities on human life.]
(2)A policy which evidences a contract of insurance to which sub-paragraph (4) below applies shall not be a qualifying policy unless it also evidences a contract falling within section 83(2)(a) of the M227Insurance Companies Act 1974.
(3)This sub-paragraph applies to contracts of insurance issued in respect of insurances made on or after 25th March 1982 against risks of persons dying as a result of an accident or an accident of a specified class, not being contracts which—
(a)are expressed to be in effect for a period of not less than five years or without limit of time; and
(b)either are not expressed to be terminable by the insurer before the expiration of five years from their taking effect or are expressed to be so terminable before the expiration of that period only in special circumstances therein mentioned.
(4)This sub-paragraph applies to contracts of insurance issued in respect of insurances made before 25th March 1982 against risks of persons dying as a result of an accident or an accident of a specified class, not being contracts falling within section 83(2)(b) of the Insurance Companies Act 1974.
Textual Amendments
F3120Words in Sch. 15 para. 11(1) substituted (1.12.2001 in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 47(3)
Marginal Citations
(iii) Exceptional [F3121risk of death or disability]U.K.
Textual Amendments
F3121Words in Sch. 15 para. 12 heading substituted (retrospectively with effect in accordance with s. 172(6) of the amending Act) by Finance Act 2003 (c. 14), s. 172(2)
12U.K.M228 For the purpose of determining whether any policy is a qualifying policy, there shall be disregarded—
(a)so much of any premium thereunder as is charged on the grounds that an exceptional risk of death [F3122or disability] is involved; and
(b)any provision under which, on those grounds, any sum may become chargeable as a debt against the capital sum guaranteed by the policy on death [F3122or disability].
Textual Amendments
F3122Words in Sch. 15 para. 12 inserted (retrospectively with effect in accordance with s. 172(6) of the amending Act) by Finance Act 2003 (c. 14), s. 172(1)
Marginal Citations
M228Source—1970 Sch.1 6, 7
(iv) Connected policiesU.K.
13U.K.M229 Subject to paragraph 14 below, where the terms of any policy provide that it is to continue in force only so long as another policy does so, neither policy is a qualifying policy unless, if they had constituted together a single policy issued in respect of an insurance made at the time of the insurance in respect of which the first-mentioned policy was issued, that single policy would have been a qualifying policy.
Marginal Citations
M229Source—1980 s.30; 1984 s.74; 1982 s.35(3)
14(1)A policy shall not be a qualifying policy if the policy is connected with another policy and the terms of either policy provide benefits which are greater than would reasonably be expected if any policy connected with it were disregarded.U.K.
(2)For the purposes of this paragraph a policy is connected with another policy if they are at any time simultaneously in force and either of them is issued with reference to the other, or with a view to enabling the other to be issued on particular terms or facilitating its being issued on those terms.
(3)In this paragraph “policy” means a policy [F3123evidencing a contract of long-term insurance], and includes any such policy issued outside the United Kingdom.
[F3124(3A)In sub-paragraph (3) “contract of long-term insurance” means a contract which falls within Part II of Schedule 1 to the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001.]
(4)Where any person issues a policy—
(a)which by virtue of this paragraph is not a qualifying policy, or
(b)the issue of which causes another policy to cease by virtue of this paragraph to be a qualifying policy,
he shall within three months of issuing the policy give notice of that fact to the Board.
(5)F3125. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)This paragraph shall apply to policies issued in respect of insurances made before 23rd August 1983 in accordance with sub-paragraphs (7) and (8) below.
(7)Where—
(a)a policy is issued in respect of an insurance made before 23rd August 1983, and
(b)a policy is issued in respect of an insurance made on or after that date which is connected with it within the meaning of this paragraph,
sub-paragraphs (1) to (6) above shall apply to the policy issued in respect of an insurance made before that date.
(8)Sub-paragraphs (1) to (7) above shall apply to policies issued in respect of insurances made before 23rd August 1983 (other than policies which, disregarding this paragraph, fall within sub-paragraph (7)) with the substitution—
(a)in sub-paragraph (1) for the words “and the terms of either policy” of the words “ the terms of which ”;
(b)in sub-paragraph (3) for the words from “long term business” to “1982” of the words “ ordinary long-term insurance business within the meaning of section 83(2) of the Insurance Companies Act 1974 (as enacted) or, in relation to a policy made after 25th March 1982, section 96(1) of the Insurance Companies Act 1982 ”; and
(c)in sub-paragraphs (6) and (7) for the words “23rd August 1983” of the words “ 26th March 1980 ”.
(9)In any case where payments made—
(a)after 22nd August 1983, and
(b)by way of premium or other consideration in respect of a policy issued in respect of an insurance made before that date,
exceed £5 in any period of 12 months, the policy shall be treated for the purposes of this paragraph as if it were issued in respect of an insurance made after 22nd August 1983; but nothing in this paragraph shall apply with respect to any premium paid in respect of it before that date.
(10)Sub-paragraphs (8) and (9) above do not apply in relation to policies issued in the course of industrial assurance business.
Textual Amendments
F3123Words in Sch. 15 para. 14(3) substituted (1.12.2001 in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 47(4)
F3124Sch. 15 para. 14(3A) inserted (1.12.2001 in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2001/3629), art. 47(5)
F3125Sch. 15 para. 14(5) omitted (13.8.2009) by virtue of The Finance Act 2009, Schedule 47 (Consequential Amendments) Order 2009 (S.I. 2009/2035), art. 1, Sch. para. 24
(v) Premiums paid out of sums due under previous policiesU.K.
15(1)M230 Where, in the case of a policy under which a single premium only is payable, liability for the payment of that premium is discharged in accordance with sub-paragraph (2) below, the policy is a qualifying policy notwithstanding anything in paragraph 1(2) or (3) or paragraph 2(1)(b) or (c) above; and where, in the case of any other policy, liability for the payment of the first premium thereunder, or of any part of that premium, is so discharged, the premium or part shall be disregarded for the purposes of paragraphs 1(2)(b) and (3)(b) and 2(1)(c) above.U.K.
(2)Liability for the payment of a premium is discharged in accordance with this sub-paragraph if it is discharged by the retention by the company with which the insurance is made of the whole or a part of any sum which has become payable on the maturity of, or on the surrender more than ten years after its issue of the rights conferred by, a policy—
(a)previously issued by the company to the person making the insurance, or, if it is made by trustees, to them or any predecessors in office; or
(b)issued by the company when the person making the insurance was an infant, and securing a capital sum payable either on a specified date falling not more than one month after his attaining 25, or on the anniversary of the policy immediately following his attainment of that age,
being, unless it is a policy falling within paragraph (b) above and the premium in question is a first premium only, a policy which was itself a qualifying policy, or which would have been a qualifying policy had it been issued in respect of an insurance made after 19th March 1968.
Marginal Citations
M230Source—1970 Sch.1 8
(vi) Additional premiums under section 72(9) of the Ginance Act 1984U.K.
16U.K.M231 In determining whether a policy is a qualifying policy, no account shall be taken of any amount recovered, as if it were an additional premium, in pursuance of section 72(9) of the Finance Act 1984.
Marginal Citations
M231Source—1984 s.72(9)(a)
(viii) Substituitions and variationsU.K.
17(1)M232 Subject to paragraph 19 below, where one policy (“the new policy”) is issued in substitution for, or on the maturity of and in consequence of an option conferred by, another policy (“the old policy”), the question whether the new policy is a qualifying policy shall, to the extent provided by the rules in sub-paragraph (2) below, be determined by reference to both policies.U.K.
(2)The rules (for the purposes of which, the question whether the old policy was a qualifying policy shall be determined in accordance with this Part of this Schedule, whatever the date of the insurance in respect of which it was issued), are as follows—
[F3126(za)the new policy cannot be a qualifying policy if the old policy was not a qualifying policy by virtue of—
(i)paragraph A1(2), B1(2), B2(2) or B3(3) above, or
(ii)sub-paragraph (i) above or this sub-paragraph;]
(a)if the new policy would apart from this paragraph be a qualifying policy but the old policy was [F3127not [F3128and paragraph (za) above does not apply],] the new policy is not a qualifying policy unless the person making the insurance in respect of which it is issued was an infant when the old policy was issued, and the old policy was one securing a capital sum payable either on a specified date falling not later than one month after his attaining 25 or on the anniversary of the policy immediately following his attainment of that age;
(b)if the new policy would apart from this paragraph be a qualifying policy, and the old policy was also a qualifying policy, the new policy is a qualifying policy unless—
(i)it takes effect before the expiry of ten years from the making of the insurance in respect of which the old policy was issued, and
(ii)subject to sub-paragraph (4) below, the highest total of premiums payable thereunder for any period of 12 months expiring before that time is less than one half of the highest total paid for any period of 12 months under the old policy, or under any related policy issued less than ten years before the issue of the new policy (“” meaning any policy in relation to which the old policy was a new policy within the meaning of this paragraph, any policy in relation to which that policy was such a policy, and so on);
(c)if the new policy would not apart from this paragraph be a qualifying policy, and would fail to be so by reason only of paragraph 1(2) or (3) or 2(1)(a), (b) or (c) above, it is nevertheless a qualifying policy if the old policy was a qualifying policy and—
(i)the old policy was issued in respect of an insurance made more than ten years before the taking effect of the new policy, and, subject to sub-paragraph (4) below, the premiums payable for any period of 12 months under the new policy do not exceed the smallest total paid for any such period under the old policy; or
(ii)the old policy was issued outside the United Kingdom, and the circumstances are as specified in sub-paragraph (3) below.
(3)M233 The circumstances are—
(a)where the new policy referred to in sub-paragraph (2)(c) above is issued after 22nd February 1984, that the policy holder under the new policy became resident in the United Kingdom during the 12 months ending with the date of its issue;
(b)where paragraph (a) above does not apply, that the person in respect of whom the new insurance is made became resident in the United Kingdom during the 12 months ending with the date of its issue;
(c)that the issuing company certify that the new policy is in substitution for the old, and that the old was issued either by a [F3129permanent establishment] of theirs outside the United Kingdom or by a company outside the United Kingdom with whom they have arrangements for the issue of policies in substitution for ones held by persons coming to the United Kingdom; and
(d)that the new policy confers on the holder benefits which are substantially equivalent to those which he would have enjoyed if the old policy had continued in force.
(4)M234 Where the new policy is one issued on or after 1st April 1976 then, in determining under sub-paragraph [F3130(2)(a) to (c)] above whether that policy would or would not (apart from sub-paragraphs (1) to (3) above) be a qualifying policy, there shall be left out of account so much of the first premium payable thereunder as is accounted for by the value of the old policy.
[F3131(5)In determining under sub-paragraph (2)(a) to (c) above whether the new policy would apart from this paragraph be a qualifying policy, paragraph A1 above is not to be applied in relation to the issue of the new policy; but this does not stop that paragraph being applied in relation to the issue of the new policy after this paragraph has been applied.]
Textual Amendments
F3126Sch. 15 para. 17(2)(za) inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 4(2)
F3127Word in Sch. 15 para. 17(2)(a) inserted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 10
F3128Words in Sch. 15 para. 17(2)(a) inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 4(3)
F3129Words in Sch. 15 para. 17(3)(c) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
F3130Words in Sch. 15 para. 17(4) substituted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 4(4)
F3131Sch. 15 para. 17(5) inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 4(5)
Marginal Citations
M232Source—1970 Sch.1 9(1), (2)
M233Source—1970 Sch.1 9(3); 1984 s.76(3), (6)
M234Source—1975 Sch.2 5
18(1)M235 Subject to paragraph 19 below and to the provisions of this paragraph, where the terms of a policy are varied, the question whether the policy after the variation is a qualifying policy shall be determined in accordance with the rules in paragraph 17 above, with references in those rules to the new policy and the old policy construed for that purpose as references respectively to the policy after the variation and the policy before the variation, and with any other necessary modifications.U.K.
(2)In applying any of those rules by virtue of this paragraph, the question whether a policy after a variation would be a qualifying policy apart from the rule shall be determined as if any reference in paragraphs [F31321, 2, 3(5) to (11), 4 to 9], 12 and 13 above to the making of an insurance, or to a policy’s term, were a reference to the taking effect of the variation or, as the case may be, to the term of the policy as from the variation.
(3)This paragraph does not apply by reason of—
(a)any variation which, whether or not of a purely formal character, does not affect the terms of a policy in any significant respect, or
(b)any variation effected before the end of the year 1968 for the sole purpose of converting into a qualifying policy any policy issued (but not one treated, by virtue of paragraph 8(1) and (2) of Schedule 14, as issued) in respect of an insurance made after 19th March 1968,[F3133 or
(c)any variation so as to increase the benefits secured or reduce the premiums payable which is effected—
(i)on or after such day as the Board may by order appoint, and
(ii)in consideration of a change in the method of payment of premiums from collection by a person collecting premiums from house to house to payment by a different method][F3134, or
(d)any variation which alters the method for calculating the benefits secured by the policy.]
[F3135(4)For the purposes of this paragraph there is no variation in the terms of a policy where—
(a)an amount of premium chargeable on the grounds that an exceptional risk of death or disability is involved becomes or ceases to be payable, or
(b)the policy is amended by the insertion, variation or removal of a provision under which, on those grounds, any sum may become chargeable as a debt against the capital sum guaranteed by the policy on death or disability.]
Subordinate Legislation Made
P5Sch. 15 para. 18(3)(c)(i) power exercised: 1.12.2001 appointed by S.I. 2001/3643, art. 2(c)
Textual Amendments
F3132Word in Sch. 15 para. 18(2) substituted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 11
F3133Sch. 15 para. 18(3)(c) and preceding word inserted (29.4.1996) by Finance Act 1996 (c. 8), s. 167(9)
F3134Sch. 15 para. 18(3)(d) and preceding word inserted (partly retrospective, and otherwise with effect in accordance with s. 87(5) of the amending Act) by Finance Act 2006 (c. 25), s. 87(2)(4)(6)
F3135Sch. 15 para. 18(4) inserted (retrospectively with effect in accordance with s. 172(6) of the amending Act) by Finance Act 2003 (c. 14), s. 172(4)
Marginal Citations
M235Source—1970 Sch.1 10
19(1)M236 The following provisions of this paragraph shall have effect for determining for the purposes of this Schedule whether a policy has been varied or whether a policy which confers on the person to whom it is issued an option to have another policy substituted for it or to have any of its terms changed is a qualifying policy.U.K.
(2)If the policy is one issued in respect of an insurance made before 1st April 1976—
(a)any such option shall, until it is exercised, be disregarded in determining whether the policy is a qualifying policy; and
(b)any change in the terms of the policy which is made in pursuance of such an option shall be deemed to be a variation of the policy.
(3)If the policy is one issued in respect of an insurance made on or after 1st April 1976, the policy shall not be a qualifying policy unless it satisfies the conditions applicable to it under this Schedule before any such option is exercised and—
(a)each policy that might be substituted for it in pursuance of such an option would satisfy those conditions under the rules of paragraph 17 above; and
(b)the policy would continue to satisfy those conditions under the rules of that paragraph as applied by paragraph 18 above if each or any of the changes capable of being made in pursuance of such an option had been made and were treated as a variation;
and it shall not be treated as being varied by reason only of any change made in pursuance of such an option.
Marginal Citations
M236Source—1975 Sch.2 3
20(1)M237 Where, as a result of a variation in the life or lives for the time being assured, a qualifying policy (“the earlier policy”) is replaced by a new policy (“the later policy”) which in accordance with the rules in paragraph 17 above is also a qualifying policy, then, subject to sub-paragraph (2) below, for the purposes of—U.K.
(a)sections 268 to 270 F3136. . . ; and
(b)any second or subsequent application of this paragraph;
the later policy and the earlier policy shall be treated as a single policy issued in respect of an insurance made at the time of the making of the insurance in respect of which the earlier policy was issued; and, accordingly, so long as the later policy continues to be a qualifying policy, the single policy shall also be treated as a qualifying policy for those purposes.
(2)Sub-paragraph (1) above does not apply unless—
(a)any sum which would otherwise become payable by the insurer on or in connection with the coming to an end of the earlier policy is retained by the insurer and applied in the discharge of some or all of the liability for any premium becoming due under the later policy; and
(b)no consideration in money or money’s worth (other than the benefits for which provision is made by the later policy) is receivable by any person on or in connection with the coming to an end of the earlier policy or the coming into existence of the later policy.
(3)Any sum which is applied as mentioned in sub-paragraph (2)(a) above—
(a)shall be left out of account in determining, for the purposes of sections 268 to 270 F3137. . . , the total amount which at any time has been paid by way of premiums under the single policy referred to in sub-paragraph (1) above; F3138. . .
(b)F3138. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(4)This paragraph applies where the later policy comes into existence on or after 25th March 1982.
Textual Amendments
F3136Words in Sch. 15 para. 20(1)(a) omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 9(a)
F3137Words in Sch. 15 para. 20(3)(a) omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 9(b)(i)
F3138Sch. 15 para. 20(3)(b) and preceding word omitted (with effect in accordance with Sch. 14 para. 18(1) of the repealing Act) by virtue of Finance Act 2008 (c. 9), Sch. 14 para. 9(b)(ii)
Marginal Citations
M237Source—1982 s.34
[F3139(viii) Policy reinstated after non-payment of premiumU.K.
Textual Amendments
F3139Sch. 15 para. 20ZA and preceding cross-heading inserted (1.4.2011 with effect in accordance with art. 15(2) of the amending S.I.) by The Enactment of Extra-Statutory Concessions Order 2011 (S.I. 2011/1037), arts. 1, 15(1)
20ZA(1)This paragraph applies to a qualifying policy (“the original policy”) if conditions A to D are satisfied.U.K.
(2)Condition A is that one or more premiums due under the original policy are not paid on or before the date on which they become due.
(3)Condition B is that the original policy, in accordance with its terms, is treated as having lapsed or is converted into a paid-up policy—
(a)by reason only of the failure to pay that premium or those premiums, and
(b)within the period of 12 months beginning with the day following the day on which the earliest unpaid premium becomes due.
(4)Condition C is that the original policy—
(a)is reinstated on the same terms, or
(b)is replaced by another policy in the same terms (“the replacement policy”),
on or before the thirtieth day after the first anniversary of the day following the day on which the earliest unpaid premium becomes due.
(5)Condition D is that all unpaid premiums due under the original policy are paid on or before the date on which the policy is reinstated or replaced.
(6)Where condition C is satisfied by virtue of sub-paragraph (4)(b) the replacement policy is to be treated for the purposes of this Schedule as if it were the original policy.
(7)The policy is to be treated for the purposes of this Schedule as if the premiums payable under it had been paid on their due dates.]
[F3140Meaning of “industrial assurance business”U.K.
Textual Amendments
F3140Sch. 15 para. 20A and preceding cross-heading inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 233 (with Sch. 2)
20AU.K.In this Part of this Schedule “industrial assurance business” means any industrial assurance business within the meaning given by—
(a)section 1(2) of the Industrial Assurance Act 1923, or
(b)Article 3(1) of the Industrial Assurance (Northern Ireland) Order 1979,
which was carried on before 1 December 2001.]
PART IIU.K. CERTIFICATION OF QUALIFYING POLICIES
Policies issued in respect of insurances made on or after 1st April 1976 or varied on or after that dateU.K.
21U.K.F3141. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3141Sch. 15 para. 21 repealed (with effect in accordance with s. 55(1)-(5) of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(7), Note (as s. 55 of that repealing Act is amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
22U.K.F3142. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3142Sch. 15 para. 22 repealed (with effect in accordance with s. 55(1)-(5) of the repealing Act) by Finance Act 1995 (c. 4), s. 55(4)(9), Sch. 29 Pt. 8(7), Note (as s. 55 of that repealing Act is amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
PART IIIU.K. POLICIES ISSUED BY NON-RESIDENT COMPANIES
23U.K.M238 In this Part—
(a)any reference to a paragraph is a reference to that paragraph of this Schedule; and
(b)“the old policy” and “the new policy” have the same meanings as in paragraph 17.
Marginal Citations
M238Source—1984 Sch.15 Pt.II 1
24(1)M239 This paragraph applies to a policy of life insurance—U.K.
(a)which is issued in respect of an insurance made after 17th November 1983; and
(b)which is so issued by a company resident outside the United Kingdom;
and in the following provisions of this paragraph such a policy is referred to as “a new non-resident policy” and the company by which it is issued is referred to as “the issuing company”.
[F3143(2)Subject to section 55(3) of the Finance Act 1995 (transitional provision for the certification of certain policies), a new non-resident policy that falls outside sub-paragraph (2A) below shall not be a qualifying policy until such time as the conditions in sub-paragraph (3) are fulfilled with respect to it.
(2A)A policy falls outside this sub-paragraph unless, at the time immediately before [F3144the appointed date for the purposes of section 55 of the Finance Act 1995 (removal of certification requirements)], it was a qualifying policy by virtue of sub-paragraphs (2)(b) and (4) of this paragraph, as they had effect in relation to that time.]
(3)The conditions F3145. . . referred to in sub-paragraph (2) above are—
(a)that the issuing company is lawfully carrying on in the United Kingdom life assurance business (as defined in [F3146section 56 of the Finance Act 2012]); and
(b)that the premiums under the policy are payable to a [F3147permanent establishment] in the United Kingdom of the issuing company, being a [F3147permanent establishment] through which the issuing company carries on its life assurance business; and
(c)the premiums under the policy form part of those business receipts of the issuing company which arise through that [F3147permanent establishment].
(4)F3148. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3143Sch. 15 para. 24(2)(2A) substituted for para. 24(2) by Finance Act 1995 (c. 4), s. 55(5)(a)(9) (as amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
F3144Words in Sch. 15 para. 24(2A) substituted (29.4.1996) by Finance Act 1996 (c. 8), s. 162(2)
F3145Words in Sch. 15 para. 24(3) repealed (with effect in accordance with s. 55(1)-(5) of the repealing Act) by Finance Act 1995 (c. 4), s. 55(5)(b)(9), Sch. 29 Pt. 8(7), Note (as s. 55 of that repealing Act is amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
F3146Words in Sch. 15 para. 24(3)(a) substituted (with effect in accordance with s. 148(1) of the amending Act) by Finance Act 2012 (c. 14), Sch. 16 para. 45 (with Sch. 17)
F3147Words in Sch. 15 para. 24(3)(b)(c) substituted (with effect in accordance with s. 155(2) of the amending Act) by Finance Act 2003 (c. 14), Sch. 27 para. 1(4)
F3148Sch. 15 para. 24(4) repealed (with effect in accordance with s. 55(1)-(5) of the repealing Act) by Finance Act 1995 (c. 4), s. 55(5)(b)(9), Sch. 29 Pt. 8(7), Note (as s. 55 of that repealing Act is amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
Marginal Citations
M239Source—1975 Sch.2 1A; 1984 Sch.5 Pt.I
25(1)M240 In the application of paragraph 17 in any case where—U.K.
(a)the old policy was issued in respect of an insurance made after 17th November 1983 and could not be a qualifying policy by virtue of paragraph 24, and
(b)the new policy is not a new non-resident policy as defined in that paragraph,
the rules for the determination of the question whether the new policy is a qualifying policy shall apply with the modifications in sub-paragraph (2) below.
[F3149(2)The modifications are the following—
(a)if, apart from paragraph 24, the old policy or any related policy (within the meaning of paragraph 17(2)(b)) of which account falls to be taken would have been a qualifying policy, that policy shall be assumed to have been a qualifying policy for the purposes of paragraph 17(2); and
(b)if, apart from this paragraph, the new policy would be a qualifying policy, it shall not be such a policy unless the circumstances are as specified in paragraph 17(3); and
(c)in paragraph 17(3)(c) the words “either by a [F3150permanent establishment] of theirs outside the United Kingdom or” shall be omitted;
and references in this sub-paragraph to being a qualifying policy shall have effect, in relation to any time before [F3151the appointed date for the purposes of section 55 of the Finance Act 1995 (removal of certification requirements)], as including a reference to being capable of being certified as such a policy.]
[F3152(2A)In determining for the purposes of sub-paragraph (2)(a) above whether a policy would, apart from paragraph 24, have been a qualifying policy, paragraphs A1 and B1 to B3 above are to be ignored.
(But this does not affect the application of any of those paragraphs in relation to the new policy.)]
(3)In the application of paragraph 17 in any case where—
(a)the old policy is a qualifying policy which was issued in respect of an insurance made on or before 17th November 1983 but, if the insurance had been made after that date, the policy could not have been a qualifying policy by virtue of paragraph 24, and
(b)the new policy is issued after that date and is not a new non-resident policy, as defined in paragraph 24,
the rules for the determination of the question whether the new policy is a qualifying policy shall apply with the modification in sub-paragraph (2)(c) above.
Textual Amendments
F3149Sch. 15 para. 25(2) substituted by Finance Act 1995 (c. 4), s. 55(6)(9) (as amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
F3150Words in Sch. 15 para. 25(2)(c) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
F3151Words in Sch. 15 para. 25(2) substituted (29.4.1996) by Finance Act 1996 (c. 8), s. 162(2)
F3152Sch. 15 para. 25(2A) inserted (17.7.2013) by Finance Act 2013 (c. 29), Sch. 9 para. 5
Marginal Citations
M240Source—1984 Sch.15 Pt.II 2-4
26U.K.If, in the case of a substitution of policies falling within paragraph 25(1) or (3), the new policy confers such an option as results in the application to it of paragraph 19(3), the new policy shall be treated for the purposes of paragraph 19(3) as having been issued in respect of an insurance made on the same day as that on which was made the insurance in respect of which the old policy was issued.
27(1)For the purposes of Part I and [F3153paragraph] 24, a policy of life insurance which was issued—U.K.
(a)in respect of an insurance made on or before 17th November 1983, and
(b)by a company resident outside the United Kingdom,
shall be treated as issued in respect of an insurance made after that date if the policy is varied after that date so as to increase the benefits secured or to extend the term of the insurance.
(2)If a policy of life insurance which was issued as mentioned in sub-paragraph (1)(a) and (b) above confers on the person to whom it is issued an option to have another policy substituted for it or to have any of its terms changed, then for the purposes of that sub-paragraph any change in the terms of the policy which is made in pursuance of the option shall be deemed to be a variation of the policy.
Textual Amendments
F3153Word in Sch. 15 para. 27(1) substituted (except for specified purposes) by Finance Act 1995 (c. 4), s. 55(7)(9) (as amended (29.4.1996) by Finance Act 1996 (c. 8), s. 162(1)); S.I. 2013/759, art. 2
F3154F3154[F3155SCHEDULE 15AU.K. CONTRACTUAL SAVINGS SCHEMES]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3154Sch. 15A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 345, Sch. 3 (with Sch. 2)
F3155Sch. 15A inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 12 para. 6(2)
[F3159SCHEDULE 15BU.K. Venture Capital Trusts: Relief from Income Tax
Textual Amendments
F3160F3160Part IU.K. Relief on investment
Textual Amendments
F3160Sch. 15B Pt. 1 (paras. 1-6) repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 234, Sch. 3 Pt. 1 (with Sch. 2)
Entitlement to claim reliefU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Loan-linked investmentsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Loss of investment reliefU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Assessment on withdrawal or reduction of reliefU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Provision of informationU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Interpretation of Part IU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Part IIU.K. Relief on distributions
Modifications etc. (not altering text)
C144Sch. 15B Pt. 2 applied (1.5.1995) by Taxation of Chargeable Gains Act 1992 (c. 12), s. 151A(6) (as inserted by Finance Act 1995 (c. 4), s. 72(3))
7U.K.F3175. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3175Sch. 15B paras. 7-9 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 346(3), Sch. 3 (with Sch. 2)
Meaning of “permitted maximum”U.K.
8U.K.F3176. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3176Sch. 15B paras. 7-9 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 346(3), Sch. 3 (with Sch. 2)
Interpretation of Part IIU.K.
9U.K.F3177. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3177Sch. 15B paras. 7-9 repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 346(3), Sch. 3 (with Sch. 2)
F3178F3178 SCHEDULE 16U.K.
Textual Amendments
F3178Sch. 16 repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 235, Sch. 3 Pt. 1 (with Sch. 2)
InterpretationU.K.
1In this Schedule “relevant payment” means any payment to which section 350(4)(a) applies.
Duty to make returnsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Contents of returnsU.K.
3The return made by a company for any period shall show—
(a)the amount of any relevant payments made by the company in that period; and
(b)the income tax in respect of those payments for which the company is accountable.
Payment of taxU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Set-off of income tax borne on company income against tax payableU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .7Income tax set against other tax under paragraph 5 above shall be treated as paid or repaid, as the case may be, and the same tax shall not be taken into account both under this Schedule and under section 7(2).
Amended return where company becomes aware of an errorU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Items included in errorU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Relevant payment made otherwise than in accounting periodU.K.
9Where a company makes a relevant payment on a date which does not fall within an accounting period the company shall make a return of that payment within 14 days from that date, and the income tax for which the company is accountable in respect of that payment shall be due at the time by which the return is to be made.
Assessments and due date of taxU.K.
10(1)All the provisions of the Income Tax Acts as to the time within which an assessment may be made, so far as they refer or relate to the year of assessment for which an assessment is made, or the year to which an assessment relates, shall apply in relation to any assessment under this Schedule notwithstanding that, under this Schedule, the assessment may be said to relate to a quarter or other period which is not a year of assessment, and the provisions of [F3187section 36] of the Management Act as to the circumstances in which an assessment may be made out of time shall apply accordingly on the footing that any such assessment relates to the year of assessment in which the quarter or other period ends.
(2)Income tax assessed on a company under this Schedule shall be due within 14 days after the issue of the notice of assessment (unless due earlier under paragraph 4(1) or 9 above).
(3)Sub-paragraph (2) above has effect subject to any appeal against the assessment, but no such appeal shall affect the date when tax is due under paragraph 4(1) or 9 above.
(4)On the determination of an appeal against an assessment under this Schedule any tax overpaid shall be repaid.
(5)Any tax assessable under any one or more of the provisions of this Schedule may be included in one assessment if the tax so included is all due on the same date.
SavingU.K.
11Nothing in paragraphs 1 to 10 above shall be taken to prejudice any powers conferred by the Income Tax Acts for the recovery of income tax by means of an assessment or otherwise; and any assessment in respect of tax payable under paragraph 9 above shall be treated for the purposes of the provisions mentioned in paragraph 10(1) above as relating to the year of assessment in which the payment is made.
F3188F3188SCHEDULE 17U.K.
Textual Amendments
F3188Sch. 17 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 139, Sch. 3 Pt. 1 (with Sch. 2)
PART IU.K. DIVISION OF ACCOUNTING PERIODS COVERING 1st APRIL 1987
1(1)This Part of this Schedule has effect in the circumstances set out in section 404(3)(a).
(2)In this Part of this Schedule—
(a)“the straddling period” means the accounting period of the dual resident investing company which begins before and ends on or after 1st April 1987; and
(b)“dual resident investing company” has the same meaning as in section 404.
(3)It shall be assumed for the purposes of this Chapter (except section 404(3) to (6)) and Part II of this Schedule—
(a)that an accounting period of the company ends on 31st March 1987; and
(b)that a new accounting period begins on 1st April 1987, the new accounting period to end with the end of the straddling period.
(4)In this Part of this Schedule “the component accounting periods” means the two accounting periods referred to in sub-paragraph (3) above.
2Subject to paragraph 5 below, for the purposes referred to in paragraph 1(3) above, the losses and other amounts of the straddling period of a dual resident investing company, excluding any such excess of charges on income as is referred to in section 403(7), shall be apportioned to the component accounting periods on a time basis according to their lengths.
3If, in the straddling period of a dual resident investing company, the company has paid any amount by way of charges on income, then, for the purposes referred to in paragraph 1(3) above, the excess of that amount referred to in section 403(7) shall be apportioned to the component accounting periods—
(a)according to the dates on which, subject to paragraph 6 below, the interest or other payments giving rise to those charges were paid (or were treated as paid for the purposes of section 338); and
(b)in proportion to the amounts of interest or other payments paid (or treated as paid) on those dates.
PART IIU.K. EARLY PAYMENTS OF INTEREST ETC. AND CHARGES ON INCOME
InterpretationU.K.
4In this Part of this Schedule—
(a)a “1986 accounting period” means an accounting period which begins or ends (or begins and ends) in the financial year 1986;
(b)a “post-1986 accounting period” means an accounting period which begins on or after 1st April 1987; and
(c)“dual resident investing company” has the same meaning as in section 404.
Early payment of interest etc.U.K.
5(1)If the conditions in sub-paragraph (2) or (3) below are fulfilled and if the Board so direct, this paragraph applies in relation to a 1986 accounting period of a dual resident investing company.
(2)The conditions in this sub-paragraph are applicable only if the company is carrying on a trade in the 1986 accounting period, and those conditions are—
(a)that in that accounting period the company has incurred a loss, computed as for the purposes of section 393(2), in carrying on that trade; and
(b)that in that period the company has made a payment falling within section 404(6)(a)(iii); and
(c)that the payment referred to in paragraph (b) above either did not fall due in that period or would not have fallen due in that period but for the making, on or after 5th December 1986, of arrangements varying the due date for payment.
(3)The conditions in this sub-paragraph are applicable only if the company is an investment company in the 1986 accounting period, and those conditions are—
(a)that for that accounting period the company has (apart from this paragraph) such an excess as is referred to in section 403(4); and
(b)that one or more of the sums which for that accounting period may be deducted as expenses of management under section 75(1) either did not fall due in that period or would not have fallen due in that period but for the making, on or after 5th December 1986, of arrangements varying the due date for payment.
(4)The Board shall not give a direction under this paragraph with respect to a 1986 accounting period of a dual resident investing company unless it appears to the Board that the sole or main benefit that might be expected to accrue from the early payment or, as the case may be, from the arrangements was that (apart from this paragraph) the company would, for that period, have an amount or, as the case may be, a larger amount available for surrender by way of group relief.
(5)If this paragraph applies in relation to a 1986 accounting period of a dual resident investing company which is carrying on a trade then, for the purposes of this Chapter and, where appropriate, any apportionment under paragraph 2 above—
(a)the loss (if any) of the company for that period shall be computed (as mentioned in section 403(1)) as if any payment falling within sub-paragraph (2)(b) above had not been made in that period; and
(b)the loss (if any) of the company for its first post-1986 accounting period shall be computed as if any such payment were made in that period.
(6)If this paragraph applies in relation to a 1986 accounting period of a dual resident investing company which is an investment company, then, for the purposes referred to in sub-paragraph (5) above—
(a)the amount which may be deducted as expenses of management for that period, as mentioned in section 403(4), shall be computed as if any sum falling within sub-paragraph (3)(b) above had not been disbursed; and
(b)the amount which may be so deducted as expenses of management for the first of the company’s post-1986 accounting periods shall be computed as if any such sum were disbursed in that period.
Early payment of charges on incomeU.K.
6(1)If, in the case of a dual resident investing company, either of the following conditions is fulfilled—
(a)that any interest or other payment which is, or is treated as, a charge on income falls due in a post-1986 accounting period but is paid (or treated for the purposes of section 338 as paid) in a 1986 accounting period, or
(b)that, on or after 5th December 1986, arrangements have been made such that any such interest or other payment which, but for the arrangements, would have fallen due in a post-1986 accounting period, fell due in a 1986 accounting period,
the interest or other payment shall, if the Board so direct, be treated for the purposes of this Chapter and, where appropriate, paragraph 3 above as paid in the post-1986 accounting period referred to in paragraph (a) or, as the case may be, paragraph (b) above.
(2)The Board shall not give a direction under this paragraph unless it appears to them that the sole or main benefit that might be expected to accrue from the early payment or, as the case may be, from the arrangements was that (apart from the direction) the interest or other payment would be attributed or apportioned to a 1986 accounting period rather than a post-1986 accounting period, so that, for the 1986 accounting period, the dual resident investing company would have an amount or, as the case may be, a larger amount available for surrender by way of group relief.
AppealsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IIIU.K. GENERAL
8(1)Parts I and II of this Schedule have effect in priority to section 409 and, accordingly, each of the component accounting periods resulting from the operation of Part I of this Schedule shall be regarded as a true accounting period for the purposes of that section.
(2)References in this Schedule to this Chapter do not include any provision of this Schedule.
F3190F3190[F3191Schedule 17A]U.K.
Textual Amendments
F3190Sch. 17A repealed and replaced (with effect in accordance with Sch. 27 Pt. 3(28) Note of the repealing Act) by Finance Act 1998 (c. 36), s. 117(1)(c), Sch. 18, Sch. 27 Pt. 3(28)
F3191Sch. 17A inserted (with effect in accordance with s. 100(4) of the amending Act) by Finance Act 1990 (c. 29), s. 100(3), Sch. 15; S.I. 1992/3066, art. 2(2)(b)
IntroductoryU.K.
1(1)This Schedule has effect as respects claims for group relief.
(2)Section 42 of the Management Act (procedure for making claims) shall not apply to such claims.
Time limitsU.K.
2(1)No claim for an accounting period of a company may be made if—
(a)the company has been assessed to corporation tax for the period, and
(b)the assessment has become final and conclusive.
(2)Sub-paragraph (1) above shall not apply in the case of a claim made before the end of 2 years from the end of the period.
(3)This paragraph applies to the withdrawal of a claim as it applies to the making of a claim.
3(1)No claim for an accounting period of a company may be made after the end of 6 years from the end of the period, except under paragraph 5 below.
(2)This paragraph applies to the withdrawal of a claim as it applies to the making of a claim.
4Where under paragraph 2 or 3 above a claim may not be made after a certain time, it may be made within such further time as the Board may allow.
5(1)A claim for an accounting period of a company may be made after the end of 6 years from the end of the period if—
(a)the company has been assessed to corporation tax for the period before the end of 6 years from the end of the period,
(b)the company has appealed against the assessment, and
(c)the assessment has not become final and conclusive.
(2)No claim for an accounting period of a company may be made under this paragraph after the end of 6 years and 3 months from the end of the period.
Method of making claimU.K.
6(1)A claim shall be made by being included in a return under section 11 of the Management Act (corporation tax return) for the period for which the claim is made.
(2)In sub-paragraph (1) above the reference to a claim being included in a return includes a reference to a claim being included by virtue of an amendment of the return.
(3)This paragraph applies to the withdrawal of a claim as it applies to the making of a claim.
Nature of claimU.K.
7A claim may be made for less than the full amount available.
8A claim, other than one under paragraph 5 above, shall be for an amount which is quantified at the time the claim is made.
9(1)A claim under paragraph 5 above shall be expressed to be conditional, as to the amount claimed, on, and only on, the outcome of one or more relevant matters specified in the claim.
(2)For the purposes of this paragraph a matter is relevant if it is relevant to the determination of the assessment of the claimant company to corporation tax for the period for which the claim is made.
Consent to surrenderU.K.
10(1)A claim shall require the consent of the surrendering company.
(2)A consortium claim shall require the consent of each member of the consortium in addition to the consent of the surrendering company.
(3)Consent to surrender shall be of no effect unless, at or before the time the claim is made, notice of consent is given by the consenting company to the inspector to whom the surrendering company makes its returns under section 11 of the Management Act.
(4)Notice of consent to surrender, in the case of consent by the surrendering company, shall be of no effect unless it contains the following particulars—
(a)the name of the surrendering company;
(b)the name of the company to which relief is being surrendered;
(c)the amount of relief being surrendered;
(d)the accounting period of the surrendering company to which the surrender relates;
(e)the tax district references of the surrendering company and the company to which relief is being surrendered.
(5)Where notice of the surrendering company’s consent to surrender is given to the inspector after the surrendering company has made a return under section 11 of the Management Act for the period to which the relief being surrendered relates, the notice shall be of no effect unless the surrendering company at the same time amends the return.
(6)Where consent to surrender relates to a loss in respect of which relief has been given under section 393(1), notice of consent to surrender, in the case of the surrendering company, shall be of no effect unless, at the same time as giving the notice to the inspector, the company amends its return under section 11 of the Management Act for the period, or, if more than one, each of the periods, in which relief for the loss has been given under section 393(1).
(7)For the purposes of sub-paragraph (6) above relief under section 393(1) shall be treated as given for losses incurred in earlier accounting periods before losses incurred in later accounting periods.
(8)A claim shall require to be accompanied by a copy of the notice of consent to surrender given for the purposes of this paragraph by the surrendering company.
(9)A consortium claim shall in addition require to be accompanied by a copy of the notice of consent to surrender given for the purposes of this paragraph by each member of the consortium.
11(1)This paragraph applies in relation to claims under paragraph 5 above.
(2)In the case of consent to surrender by the surrendering company, consent which relates to relief which is the subject of more than one claim under paragraph 5 above shall be of no effect unless it specifies an order of priority in relation to the claims.
AdjustmentsU.K.
12(1)All such assessments or adjustments of assessments shall be made as may be necessary to give effect to a claim or the withdrawal of a claim.
(2)An assessment under this paragraph shall not be out of time if it is made—
(a)in the case of a claim, within one year from the date on which an assessment of the claimant company to corporation tax for the period for which the claim is made becomes final and conclusive, and
(b)in the case of the withdrawal of a claim, within one year from the date on which the claim is withdrawn.
F3192F3192 SCHEDULE 18U.K.
Textual Amendments
F3192Sch. 18 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 140, Sch. 3 Pt. 1 (with Sch. 2)
3(1)Subject to the following provisions of this Schedule, for the purposes of [F3212sections 403C and 413(7)] the percentage to which one company would be beneficially entitled of any assets of another company available for distribution to its equity holders on a winding-up means the percentage to which the first company would be so entitled if the other company were to be wound up and on that winding-up the value of the assets available for distribution to its equity holders (that is to say, after deducting any liabilities to other persons) were equal to—
(a)the excess, if any, of the total amount of the assets of the company, as shown in the balance sheet relating to its affairs as at the end of the relevant accounting period, over the total amount of those of its liabilities as so shown which are not liabilities to equity holders as such; or
(b)if there is no such excess or if the company’s balance sheet is prepared to a date other than the end of the relevant accounting period, £100.
(2)In the following provisions of this Schedule a winding-up on the basis specified in sub-paragraph (1) above is referred to as “the notional winding-up”.
(3)If, on the notional winding-up, an equity holder would be entitled as such to an amount of assets of any description which, apart from this sub-paragraph, would not be treated as a distribution of assets, it shall nevertheless be treated, subject to sub-paragraph (4) below, as an amount to which the equity holder is entitled on the distribution of assets on the notional winding up.
(4)If an amount (“the returned amount”) which corresponds to the whole or any part of the new consideration provided by an equity holder of a company for any shares or securities in respect of which he is an equity holder is applied by the company, directly or indirectly, in the making of a loan to, or in the acquisition of any shares or securities in, the equity holder or any person connected with him, then, for the purposes of this Schedule—
(a)the total amount referred to in sub-paragraph (1)(a) above shall be taken to be reduced by a sum equal to the returned amount; and
(b)the amount of assets to which the equity holder is beneficially entitled on the notional winding-up shall be taken to be reduced by a sum equal to the returned amount.
(5)In sub-paragraph (4) above “new consideration” has the same meaning as in section 254 and any question whether one person is connected with another shall be determined in accordance with section 839 .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F3234F3234[F3235SCHEDULE 18A]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3234Sch. 18A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 141, Sch. 3 Pt. 1 (with Sch. 2)
F3235Sch. 18A inserted (with effect in accordance with Sch. 1 para. 9 of the amending Act) by Finance Act 2006 (c. 25), Sch. 1 para. 7
F3237F3237SCHEDULE 19U.K.
Textual Amendments
F3237Sch. 19 repealed by Finance Act 1989 (c. 26), ss. 103, 187, Sch. 17 Pt. V, Notes 1, 3
PART IU.K. DETERMINATION OF RELEVANT INCOME AND DISTRIBUTIONS
Relevant incomeU.K.
1M242(1)Subject to the provisions of this Part of this Schedule, the relevant income of a company for an accounting period is—
(a)in the case of a company which is a trading company or a member of a trading group, so much of its distributable income, other than trading income, for that period as can be distributed without prejudice to the requirements of the company’s business;
(b)in the case of a company not within paragraph (a)above whose distributable income for that period consists of or includes estate or trading income—
(i)so much of the estate or trading income as can be distributed without prejudice to the requirements of the company’s business so far as concerned with the activities or assets giving rise to estate or trading income; and
(ii)its distributable income, if any, other than estate or trading income;
(c)in the case of any other company, its distributable income for that period .
(2)M243In arriving at the relevant income for any accounting period—
(a)where under sub-paragraph (1)above regard is to be had to the requirements of a company’s business, regard shall be had not only to the current requirements of the business but also to such other requirements as may be necessary or advisable for the maintenance and development of that business but, for this purpose, the provisions of paragraph 8below shall apply;
(b)the amount of the estate or trading income shall be taken as the amount included in respect of it in the distributable income.
(3)M244In arriving at the relevant income for any accounting period of a company which is a trading company or a member of a trading group, regard shall be had not only to the current requirements of the company’s business and to such requirements as may be necessary or advisable for the maintenance and development of that business as fall within sub-paragraph (2)(a)above, but also to any other requirements necessary or advisable for the acquisition of a trade or of a controlling interest in a trading company or in a company which is a member of a trading group by virtue of paragraph 7(2)(a)below; but, for this purpose, paragraph 9below shall apply.
(4)For the purposes of sub-paragraph (3)above, the acquisition of a controlling interest in a company means the acquisition, whether on a single occasion or otherwise, of such ordinary share capital of that company as enables the acquiring company to exercise the greater part of the voting power in that company.
(5)For the purposes of sub-paragraph (3)above, the requirements of a company’s business which are necessary or advisable for such an acquisition as is mentioned in that sub-paragraph include such requirements as are necessary or advisable for—
(a)the redemption or repayment of any share or loan capital or debt (including any premium thereon)issued or incurred in or towards payment for that acquisition, or issued or incurred for the purpose of raising money to be applied in or towards payment therefor, or
(b)meeting any obligation of the company in respect of that acquisition,
so far as any sum so expended or applied, or intended to be expended or applied, does not fall to be treated for the purposes of this Chapter as a distribution by the company.
Maximum amount of relevant incomeU.K.
2(1)M245Subject to paragraphs 10and 12below, the relevant income of a company shall in no case be taken to exceed the company’s distributable investment income for the accounting period plus 50per cent. of the estate or trading income for the period.
(2)M246In the application of sub-paragraph (1)above to a company which is a trading company or a member of a trading group, the trading income shall be disregarded; and in the application of that sub-paragraph to a trading company, the estate income—
(a)if it is less than the appropriate fraction of the relevant maximum amount, shall be treated as reduced by one-half of the amount required to make it up to that fraction of the relevant maximum amount; or
(b)if it is less than the appropriate fraction of the relevant minimum amount, shall be disregarded;
and in this sub-paragraph the appropriate fraction is—

where—
Ais the amount of the estate income, and
Bis the amount of the trading income.
(3)M247The relevant maximum and minimum amounts referred to above shall be determined as follows—
(a)where the company has no associated company in the accounting period, those amounts are £75,000and £25,000respectively;
(b)where the company has one or more associated companies in the accounting period—
(i)the relevant maximum amount is—

(ii)the relevant minimum amount is—

where Xis the number of those associated companies.
(4)M248In applying sub-paragraphs (2)and (3)above to any accounting period of a trading company, an associated company shall be disregarded if—
(a)it was not a trading company, or has not carried on any trade, at any time in that accounting period; or
(b)where it was an associated company during part only of that accounting period, it was not a trading company, or has not carried on any trade, at any time in that part of that accounting period;
and for the purposes of this paragraph a company is to be treated as an associated company of another at a given time if at that time one of the two has control of the other or both are under the control of the same person or persons.
(5)M249In determining how many associated companies a trading company has in an accounting period or whether a trading company has an associated company in an accounting period, an associated company shall be counted even if it was an associated company for part only of the accounting period, and two or more associated companies shall be counted even if they were associated companies for different parts of the accounting period.
(6)For an accounting period of less than 12months the relevant maximum and minimum amounts determined in accordance with sub-paragraphs (1)to (5)above shall be proportionately reduced.
DistributionsU.K.
3(1)M250For the purposes of this Chapter the distributions of a company for an accounting period shall, subject to sub-paragraphs (2)to (4)and paragraph 12below, be taken to consist of—
(a)any dividends which are declared in respect of the period and are paid during the period or within a reasonable time thereafter;
(b)all distributions made in the period except dividends which, in relation to any previous period, would fall under paragraph (a)above; and
(c)M251anything that would be a distribution but for section 213or 219 (or both).
(2)M252Where a period of account is not an accounting period, dividends which, if it were an accounting period, would be treated under sub-paragraph (1)(a)above as distributions for that accounting period shall be apportioned to any accounting period or part of an accounting period falling within the period of account in proportion to the distributable income of each such period or part.
(3)M253For the purposes of determining whether there is any such excess as is referred to in section 424(1),no account shall be taken of a distribution which, in relation to the company making it, is a bonus distribution unless—
(a)it is made to a person other than a close company, or
(b)it is made to a close company and the share capital or security of which it consists is subsequently distributed, by that or any other close company, by a distribution falling within section 14(2)(b)to a person other than a close company.
(4)Where a bonus distribution has occurred and, by virtue of paragraph (a)or paragraph (b)of sub-paragraph (3)above, it falls to be taken into account for the purpose of determining whether there is any such excess as is referred to in section 424(1),no account shall be taken for that purpose of a qualifying distribution which consists of the repayment of the share capital or, as the case may be, the principal of the security, which constituted the bonus distribution.
(5)In sub-paragraphs (3)and (4)above “bonus distribution” means a distribution which in relation to the company making it is a distribution by virtue only of paragraph (c)of section 209(2).
Distributable income and estate or trading incomeU.K.
4(1)M254For the purposes of this Chapter, the distributable income of a company for an accounting period shall be the amount of its distributable profits for the period exclusive of the part attributable to chargeable gains; and for the purposes of this sub-paragraph—
(a)the distributable profits of a company for an accounting period shall be the aggregate of the following amounts, that is to say—
(i)the amount of any profits on which corporation tax falls finally to be borne, less the amount of that tax;
(ii)an amount equal to the qualifying distributions comprised in any franked investment income, other than franked investment income against which relief is given under section 242or 243;and
(iii)an amount equal to any group income ;
(b)the part of a company’s distributable profits attributable to chargeable gains shall be taken to be the amount of the chargeable gains on which corporation tax is finally borne less the amount of that tax; and
(c)the amount on which corporation tax falls finally to be borne (but not the amount of that tax)shall be computed as if section 242did not include subsection (5)or (6)of that section (and as if section 243did not apply section 242(5)) ;
and for the purposes of sub-paragraph (a)(ii)above relief under section 242or 243shall be treated as having been given first against franked investment income which is not trading income and secondly, so far as it cannot be so given, against franked investment income which is trading income.
(2)M255For the purposes of this Chapter, the distributable investment income of a company for an accounting period shall be the amount of the distributable income, exclusive of the part attributable to estate or trading income, and less whichever is the smaller of—
(a)10per cent. of the estate or trading income; and
(b)£1,000or, if the company is a trading company or a member of a trading group, £3,000or (in either case)if the accounting period is of less than 12months, a proportionately reduced amount.
5(1)M256For the purposes of this Chapter, “estate or trading income” means estate income and trading income.
(2)For those purposes “estate income” means income which is chargeable to tax under Schedule A or Schedule B, and income (other than yearly or other interest)which is chargeable to tax under Schedule D, and which arises from the ownership or occupation of land (including any interest in or right over land)or from the letting furnished of any building or part of a building, but does not include trading income.
(3)M257For those purposes “trading income” means income which is not investment income for the purposes of paragraph 7(1)below; and, where the following conditions are satisfied with respect to a close company, that is to say—
(a)that its activities consist wholly or mainly of the carrying on of a trade; and
(b)that the trade consists wholly or mainly of one or more of the following, that is to say, life assurance business (within the meaning of section 431),insurance business of any other class, banking, money lending, financing of hire-purchase or similar transactions, or dealing in securities;
its income incidental to that trade shall also be trading income.
(4)M258For the purposes of sub-paragraph (3)above income of a company is incidental to its trade if, and only if—
(a)it is derived from investments (other than investments in a 51per cent. subsidiary)or is interest on a debt; and
(b)any profit on the sale of the investments would be a trading receipt, and the debt, if proved to be a bad debt, would be allowed as a deduction in computing the company’s trading income for the purposes of corporation tax.
6(1)The amount for part of an accounting period of any description of income referred to in paragraph 4or 5above shall be a proportionate part of the amount for the whole period.
M259(2)M260In determining the amount for any period of any description of income referred to in paragraph 4or 5above, any deduction from the company’s profits for charges on income, expenses of management or other amounts which can be deducted from or set against or treated as reducing profits of more than one description shall be treated as made—
(a)first, from the company’s income charged to corporation tax other than estate or trading income;
(b)M261secondly, so far as it cannot be made under paragraph (a)above, from the company’s estate or trading income so charged;
(c)thirdly, so far as it cannot be made under paragraph (a)or (b)above, from the amount included in the company’s profits in respect of chargeable gains.
(3)M262In the application of sub-paragraph (2)above to a company which is a trading company or a member of a trading group there shall be substituted for paragraph (b)the following paragraphs—
“(b)secondly, so far as it cannot be made under (a)above, from the company’s estate income so charged;
(bb)thirdly, so far as it cannot be made under (a)or (b)above, from the company’s trading income so charged;”and in paragraph (c)for “thirdly” there shall be substituted “ fourthly ”, and for “(a) or (b)” there shall be substituted “ (a), (b) or (bb) ”.
Meaning of “trading company” and “member of a trading group”U.K.
7(1)M263For the purposes of this Chapter, a “trading company” is any company which exists wholly or mainly for the purpose of carrying on a trade, and any other company whose income does not consist wholly or mainly of investment income, that is to say, income which, if the company were an individual, would not be earned income ;but for this purpose any amount which is apportioned to a company under section 423(1)shall be deemed to be income of the company and to be investment income.
(2)Subject to sub-paragraph (3)below, for the purposes of this Chapter, a company is to be treated as a member of a trading group if, but only if—
(a)it exists wholly or mainly for the purpose of co-ordinating the administration of a group of two or more companies each of which is under its control and exists wholly or mainly for the purpose of carrying on a trade; or
(b)it is under the control of another company resident in the United Kingdom and not itself under the control of a third company, and it exists wholly or mainly for the purpose of a trade or trades carried on by that other company or by a group which, consisting of that other company and a company or companies also under its control and resident in the United Kingdom, exists wholly or mainly for the purpose of carrying on that trade or trades.
(3)A company shall not be treated as a member of a trading group by reason only of any company having the control of another if that control is exercised through a company which is not resident in the United Kingdom or through a company whose control depends on a holding a profit on the sale of which would be treated as a trading receipt of the company.
Requirements of a company’s businessU.K.
8(1)M264For the purposes of paragraph 1(2)above there shall be regarded as income available for distribution and not as having been applied, or as being applicable, to the current requirements of a company’s business, or to such other requirements as may be necessary or advisable for the maintenance and development of that business—
(a)any sum expended or applied, or intended to be expended or applied, out of the income of the company—
(i)in or towards payment for the business, undertaking or property which the company was formed to acquire or which was the first business, undertaking or property of a substantial character in fact acquired by the company, or
(ii)in redemption or repayment of any share or loan capital or debt (including any premium thereon)issued or incurred in or towards payment for any such business, undertaking or property, or issued or incurred for the purpose of raising money applied or to be applied in or towards payment therefor, or
(iii)in meeting any obligations of the company in respect of the acquisition of any such business, undertaking or property, or
(iv)in redemption or repayment of any share or loan capital or debt (including any premium thereon)issued or incurred otherwise than for adequate consideration; and
(b)any sum expended or applied, or intended to be expended or applied, in pursuance or in consequence of any fictitious or artificial transactions; and
(c)in the case of a company which is neither a trading company nor a member of a trading group, any sum expended or applied, or available to be expended or applied, out of the income of the company in or towards the redemption, repayment or discharge of any loan capital or debt (including any premium thereon)in respect of which any person is a loan creditor of the company; and
(d)in the case of a company which is neither a trading company nor a member of a trading group, any sum expended or applied, or available to be expended or applied, out of the income of the company in or towards the acquisition of an estate or interest in land or the construction or extension of a building, not being a construction or extension which constitutes an improvement or development of farm land or market garden land.
Sub-paragraph (d)above does not apply where the acquisition, construction or extension concerned was made in pursuance of a contract entered into before 24thMarch 1973.
(2)M265For the purposes of sub-paragraph (1)(a)(iv)above, share or loan capital or debt shall be deemed to be issued or incurred otherwise than for adequate consideration if—
(a)it is issued or incurred for consideration the value of which to the company is substantially less than the amount of the capital or debt (including any premium thereon);or
(b)it is issued or incurred in or towards, or for the purpose of raising money applied or to be applied in or towards, the redemption or repayment of any share or loan capital or debt which itself was issued or incurred for such consideration as is mentioned in paragraph (a)above or which represents, directly or indirectly, any share or loan capital or debt which itself was issued or incurred for such consideration.
(3)M266In relation to any loan capital or debt mentioned in sub-paragraph (1)(c)above which was issued or incurred by the company for money borrowed by it for the purpose of financing expenditure on any acquisition, construction or extension falling within sub-paragraph (1)(d)above, the expression “loan creditor” in sub-paragraph (1)(c)above shall be construed as if, in the definition of that expression in subsections (7)to (9)of section 417,subsection (9)were omitted.
(4)M267References in sub-paragraphs (1)(a)and (2)(b)above to the redemption or repayment of a company’s share capital shall be construed as including references to the purchase by the company of its own shares.
(5)M268References in sub-paragraphs (1)to (4)above to money applied or to be applied for any purpose shall be deemed to include references to money applied or to be applied in or towards the replacement of that money.
9(1)M269Paragraph 1(3)above shall not apply to—
(a)the acquisition of a trade, or of an asset to be used in a trade, or of an interest in any such asset, which at the date of the acquisition or at any time within one year previously was owned by an associated company of the acquiring company; or
(b)the intended acquisition of a trade, or of such an asset or interest as is referred to in paragraph (a) above, which, at the end of the accounting period for which the acquiring company’s relevant income is to be ascertained, is owned by a company which is then an associated company of the acquiring company;
and, where the trade, asset or interest was, or is, in part owned as mentioned above, paragraph 1(3)above shall not apply with respect to that part.
(2)Paragraph 1(3)above shall not apply to—
(a)the acquisition of shares which at the date of the acquisition or at any time within one year previously were owned by an associated company of the acquiring company or by a person who then had control of the acquiring company; or
(b)the intended acquisition of shares which at the end of the accounting period for which the acquiring company’s relevant income is to be ascertained are owned by a company which is then an associated company of the acquiring company or by a person who has control of the acquiring company;
and where shares were, or are, in part owned as mentioned above, paragraph 1(3)above shall not apply with respect to that part.
(3)Paragraph 1(3)above shall not apply to—
(a)the acquisition of shares in a company which immediately before the acquisition or at any time within one year previously was an associated company of the acquiring company; or
(b)the intended acquisition of shares in a company which, at the end of the accounting period for which the acquiring company’s relevant income is to be ascertained, is an associated company of the acquiring company.
(4)Section 416(1)—
(a)shall not apply for the purposes of paragraph (a)of sub-paragraphs (1), (2)and (3)above; and
(b)shall apply for the purposes of paragraph (b)of each of those sub-paragraphs with the omission of the words “or at any time within one year previously”.
(5)For the purposes of paragraph (a)of sub-paragraphs (1), (2)and (3)above, another company is an associated company of the acquiring company if—
(a)the acquiring company controlled that other company or that other company controlled the acquiring company either at the date of the acquisition of the trade, asset or interest or at any time within one year previously; or
(b)a person who had control of the acquiring company at that date also controlled that other company either at that date or at any time within one year previously.
(6)In ascertaining for the purposes of sub-paragraphs (2)and (5)above or for the purposes of section 416(1)as it applies for the purposes of paragraph (b)of sub-paragraphs (1), (2)and (3)above, whether any person has control of a company—
(a)there shall be left out of account for the purposes of section 416(2)(c)the rights of another company as loan creditor in respect of a debt incurred or redeemable loan capital issued in connection with the acquisition from that company of any trade, any asset to be used in a trade, or any interest in any such asset;
(b)section 417(3)(a)shall have effect as if the reference to a partner of a participator were omitted;
(c)section 417(3)(a)and (b)shall have effect as if the expression “relative” did not have the meaning assigned to it by section 417(4)but meant husband or wife or, in the case of a director of the company, husband or wife or any child or remoter issue who is an infant; and
(d)section 417(3)(c)shall have effect as if the reference to any other person interested were a reference (and a reference only)to the trustees or to the personal representatives as defined in section 701.
(7)For the purposes of this paragraph the time of acquisition of a trade, asset or interest, or shares, acquired under a contract shall be—
(a)the time at which the contract is made, or
(b)if it is conditional (and in particular if it is conditional on the exercise of an option),the time at which the condition is satisfied,
and not, if different, the time at which the trade, asset, interest or shares is or are conveyed or transferred.
(8)For the purposes of paragraph 1(3)above there shall be regarded as income available for distribution and not as having been applied, or as being applicable, to such requirements of a company’s business as may be necessary or advisable for such an acquisition as is mentioned in paragraph 1(3)above any sum expended or applied, or intended to be expended or applied, as mentioned in paragraph 8(1)(a)(iv)or (b)above; and paragraph 8(2)and (5)above shall apply for the purposes of this sub-paragraph as they apply for the purposes of paragraph 8.
Cessations and liquidationsU.K.
10(1)M270Where a close company ceases to carry on the trade, or the business of holding investments, in which its activities wholly or mainly consisted, the relevant income of the company for any accounting period in which that event occurs, or which ends in or within the 12months ending with that event, shall be calculated as if—
(a)paragraph 1(1)(a)and (b)(i)above referred respectively to the whole of the company’s distributable income other than trading income and to the whole of the estate or trading income and not to so much thereof as can be distributed without prejudice to the requirements there mentioned, and paragraphs 1(2)(a)and 8above were omitted;
(b)in paragraph 2(1)above the words “50 per cent. of” were omitted.
(2)M271Where sub-paragraph (1)above applies for an accounting period and the company could not make distributions without prejudice to the claims of creditors (excluding those mentioned in sub-paragraph (3)below),the excess mentioned in section 424(1)shall be disregarded to the extent to which the company could not make distributions up to the amount of its relevant income without prejudice to those claims.
(3)M272Subject to sub-paragraph (4)below, the creditors to be excluded for the purposes of sub-paragraph (2)above are all participators and associates of participators, and all creditors in respect of debts originally created in favour of or due to a person who was then a participator or associate of a participator.
(4)A creditor is not to be excluded in respect of any debt which either—
(a)arose in the ordinary course of the company’s trade or the company’s business of holding investments and also in the ordinary course of a trade or profession of the creditor or, as the case may be, of the participator or associate who was the original creditor; or
(b)is a debt for remuneration chargeable to income tax under Schedule E; or
(c)is a debt for any rent or other payment due for the use of
[F3238(i)tangible property,
(ii)M273copyright in a literary, dramatic, musical or artistic work within the meaning of Part Iof the Copyright, Designs and Patents Act 1988 (or any similar right under the law of a country to which that Part does not extend),or
(iii)design right,] , M274and not representing more than a reasonable commercial consideration for that use.
(5)M275Where sub-paragraph (1)above applies for any accounting period, there shall be disregarded for the purposes of any apportionment made by virtue of section 424(2)so much of the relevant income of the company for that period as is equal to the amount which would be disregarded under sub-paragraph (2)above.
(6)Where a resolution is passed or an order is made for the winding up of a close company, or where any other act is done for a like purpose in the case of a winding up otherwise than under the M276Insolvency Act 1986,sub-paragraphs (1)to (5)above shall apply for any accounting period ending in or with the 12months ending with the passing of the resolution or other event, or for any later accounting period, as they apply, in a case falling within sub-paragraph (1)above, for an accounting period in which a close company ceases to carry on a trade.
Legal restrictions on distributionsU.K.
11(1)M277Subject to paragraph 12below, where a company is subject to any restriction imposed by law as regards the making of distributions, the excess mentioned in section 424(1)shall be disregarded to the extent to which the company could not make distributions up to the amount of its relevant income without contravening that restriction.
(2)Except where paragraph 10(1)above applies, there shall be disregarded for the purposes of any apportionment made by virtue of section 424(2)so much of the relevant income of the company as is equal to any amount which would be disregarded under sub-paragraph (1)above.
Stock dividendsU.K.
12(1)M278Where a company issues to a close company any relevant share capital, sub-paragraphs (2)and (3)below shall apply as regards that share capital, and in this paragraph—
“the relevant accounting period” means the accounting period of the close company in which the due date of issue falls;
“” means share capital to which section 249applies; and
“appropriate amount in cash” has the meaning given by section 251(2).
(2)The relevant income of the close company for the relevant accounting period, as determined under paragraph 1above, and the amount which, under paragraph 2above (read, where appropriate, with paragraph 10above)the relevant income of the close company for that period cannot exceed, shall each be increased by an amount equal to the appropriate amount in cash (or, if it would otherwise be nil, be treated as equal to the appropriate amount in cash).
(3)The amount, if any, which would otherwise be disregarded under paragraph 11(1)above shall be reduced by an amount equal to the appropriate amount in cash.
(4)Where a close company issues any relevant share capital in a case falling within section 249(4), (5)or (6)or sub-paragraph (1)above (read in each case with section 249(3)),the company shall be treated for the purposes of paragraph 3(1)and (2)above—
(a)as if a dividend of an amount equal to the appropriate amount in cash had been paid on the due date of issue; and
(b)where, in relation to that share capital, “the appropriate amount in cash” has the meaning given by section 251(2)(a),as if that dividend had been declared in respect of the accounting period (if any)in respect of which the relevant cash dividend (as defined in section 251(3))was declaredF3239.
PART IIU.K.PROCEDURE
Notice of amount to be apportionedU.K.
13(1)M279Where in the case of any company the inspector proposes to apportion an amount under section 423he shall serve on the company a notice showing the amount to be apportioned and, subject to any appeal under this paragraph and to paragraph 15below, that notice shall be treated as conclusively establishing, both in relation to the company and for the purposes of any assessment under section 426,that an apportionment can be made in respect of that amount.
(2)After a notice under sub-paragraph (1)above has been served on the company it shall not be altered except on appeal or in accordance with paragraph 15below.
(3)The company may by giving notice of appeal to the inspector within 30days of the date of any notice under sub-paragraph (1)above appeal against that notice; and any notice under that sub-paragraph shall state the time within which notice of appeal may be given under this sub-paragraph.
(4)Subject to paragraph 18(2)below, any appeal under this paragraph shall be to the General Commissioners except that the company may elect (in accordance with section 46(1)of the Management Act)to bring the appeal before the Special Commissioners instead of the General Commissioners.
(5)The notice of appeal shall specify the grounds of appeal, but on the hearing of the appeal the Commissioners may allow the appellant to put forward any ground not specified in the notice, and take it into consideration if satisfied that the omission was not wilful or unreasonable.
(6)If a company fails or refuses, on being required to do so under paragraph 17below, to furnish a statement of any amount which in the case of that company could be apportioned under section 423,or renders a statement with which the inspector is not satisfied, the inspector may make an estimate of that amount to the best of his judgment, and any relevant decision taken by the inspector under this sub-paragraph may be reviewed on appeal under this paragraph.
(7)Sections 113(1B)and (3)and 114(2)of the Management Act (supplementary provisions as to assessments and notices of assessment)shall apply to any notice under sub-paragraph (1)above as if the determination of the amount to be shown therein were the making of an assessment and the notice were a notice of assessment.
Notice of manner of apportionmentU.K.
14(1)Where notice has been served on a company under paragraph 13above showing an amount to be apportioned, the inspector shall serve on the company a notice showing the manner in which that amount is apportioned, (that is to say, the sum apportioned or sub-apportioned to each participator or, if the inspector thinks fit, to each class of share)and, subject to any appeal under this paragraph and to paragraph 15below, that notice shall be treated, in relation to the company, as conclusively establishing the manner of apportionment.
(2)Paragraph 13(2)to (5)and (7)above shall apply also to a notice under this paragraph, but any appeal against such a notice by virtue of this sub-paragraph shall be to the Special Commissioners.
(3)The manner of apportionment shown in a notice under this paragraph may also be questioned on an appeal against any assessment made under section 426;and any relevant decision taken by the inspector under section 425(2)or (3)may be reviewed on an appeal under this paragraph or on an appeal against any such assessment.
Revision of apportionmentU.K.
15(1)If the inspector discovers that the amount apportioned in the case of any company is or has become insufficient, he shall serve on the company a further notice under paragraph 13(1)above showing the further amount which ought in his opinion to be apportioned, and a further notice relating to that amount shall then be served under paragraph 14above.
(2)Where the amount shown in a notice under sub-paragraph (1)of paragraph 13above is excessive because the company’s distributable income is smaller than it was taken to be for the purposes of that notice or because the company’s distributions were greater than they were taken to be for those purposes, the inspector shall serve on the company a further notice under that sub-paragraph showing a reduced amount; and where such a notice is served—
(a)a further notice shall also be served under paragraph 14above making such amendments in any previous notice under that paragraph as may be required to take account of the reduction in the amount apportioned; and
(b)there shall be made such adjustments by repayment or discharge of tax as may be required to secure that liabilities to tax under sections 426to 430are what they would have been if the notices originally served under paragraphs 13and 14above had been as amended by further notices served by virtue of this paragraph.
Protection by transmission of accountsU.K.
16(1)A close company may, at any time after the general meeting at which the accounts for any period of account are adopted, forward to the inspector a copy of those accounts, together with a copy of the report (if any)of the directors for that period and such further information (if any)as it may think fit, and may request the inspector to proceed under this paragraph in relation to any accounting period comprised in that period of account.
(2)Sub-paragraph (1)above shall not apply if the company is neither a trading company nor a member of a trading group and has no estate or trading income.
(3)Where the inspector receives a request made in accordance with sub-paragraph (1)above in relation to any accounting period, then, subject to sub-paragraph (4)below, he shall, within three months after receipt of the request, intimate to the company whether or not he proposes to make an apportionment in respect of the company for the accounting period under section 423.
(4)On receiving a request made in accordance with sub-paragraph (1)above the inspector may, not later than three months after the receipt of the request, call on the company to furnish him with such further particulars as he may reasonably require; and, if the inspector does so, the time for giving the intimation required by sub-paragraph (3)above shall not expire before three months after he has been furnished with those particulars.
(5)Where the inspector receives a request made in accordance with sub-paragraph (1)above in relation to any accounting period, and does not within the time limited by sub-paragraphs (3)and (4)above intimate his intention to make an apportionment in respect of the period, no such apportionment shall be made unless either—
(a)the information accompanying the request, and any further particulars furnished to the inspector in connection therewith, are not such as to make full and accurate disclosure of all facts and considerations which are material to be known to him, or
(b)within 12months of the end of the period any of the provisions of paragraph 10above have effect in relation to the company.
InformationU.K.
17(1)The inspector may, by notice, require any company which is, or appears to him to be, a close company to furnish him within such time (not being less than 30days)as may be specified in the notice with such particulars as he thinks necessary for the purposes of this Chapter.
(2)If for those purposes any person in whose name any shares are registered is so required by notice by the inspector, he shall state whether or not he is the beneficial owner of the shares and, if not the beneficial owner of the shares or any of them, shall furnish the name and address of the person or persons on whose behalf the shares are registered in his name.
(3)Sub-paragraph (2)above shall apply in relation to loan capital as it applies in relation to shares.
(4)The inspector may, for the purposes of this Chapter, by notice require—
(a)any company which appears to him to be a close company to furnish him with particulars of any bearer securities issued by the company, and the names and addresses of the persons to whom the securities were issued and the respective amounts issued to each person; and
(b)any person to whom securities were so issued, or to or through whom such securities were subsequently sold or transferred, to furnish him with such further information as he may require with a view to enabling him to ascertain the names and addresses of the persons beneficially interested in the securities.
In this sub-paragraph “securities” includes shares, stocks, bonds, debentures and debenture stock and also any promissory note or other instrument evidencing indebtedness to a loan creditor of the company.
(5)Any power which the inspector may exercise under this paragraph for the purposes of this Chapter may also be exercised for the purposes of sections 419to 422 F3240.
Exercise of functions by the BoardU.K.
18(1)Any functions conferred by this Chapter on the inspector may also be exercised by the Board; and references in this Chapter to the inspector shall be construed accordingly.
(2)Where by virtue of this paragraph a notice is served by the Board under paragraph 13(1)above any appeal under that paragraph shall be to the Special CommissionersF3241.
F3242F3242[F3243SCHEDULE 19AA]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3242Sch. 19AA repealed (with effect in accordance with s. 38(2) of the repealing Act) by Finance Act 2007 (c. 11), Sch. 7 para. 55, Sch. 27 Pt. 2(7), Note (with Sch. 7 Pt. 2)
F3243Sch. 19AA inserted (for accounting periods beginning on or after 1 January 1990) by Finance Act 1990 (c. 29), Sch.7 paras. 6, 10
F3273F3273[F3274 Schedule 19AB]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3273Sch. 19AB repealed (with effect in accordance with s. 87(2)-(5) of the repealing Act) by Finance Act 2001 (c. 9), s. 87(1), Sch. 33 Pt. 2(12), Note (the provisions of Sch. 19AB not applying in relation to tax credits in respect of distributions made on or after 6th April 2004)
F3274Sch. 19AB inserted (with effect in relation to accounting periods beginning on or after 2.10.1992) by Finance Act 1991 (c. 31, SIF 63:1), s. 49, Sch. 8; S.I. 1992/1746, art. 2
F3337F3337[F3338SCHEDULE 19ABA]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3337Sch. 19ABA omitted (with effect in accordance with s. 148(1) of the repealing Act) by virtue of Finance Act 2012 (c. 14), Sch. 16 para. 46 (with Sch. 17)
F3338Sch. 19ABA inserted (27.12.2007 with effect in accordance with art. 1(2) of the amending S.I.) by The Insurance Companies (Taxation of Reinsurance Business) (Corporation Tax Acts) (Amendment) Order 2007 (S.I. 2007/3430), arts. 1(1), 3(3)
F3348F3348 [F3349SCHEDULE 19AC]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3348Sch. 19AC repealed (31.12.2006 with effect in accordance with reg. 1 of the repealing S.I.) by The Overseas Life Insurance Companies Regulations 2006 (S.I. 2006/3271), reg. 43(1), Sch. Pt. 1
F3349Sch. 19AC inserted (27.7.1993) by 1993 c. 34, s. 97, Sch. 9 para.1
Section 450.]
[F3426F3427SCHEDULE 19AU.K. UNDERWRITERS: ASSESSMENT AND COLLECTION OF TAX
Textual Amendments
F3426Sch. 19A inserted (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 58(4)(a)(5), Sch. 5
F3427Sch. 19A repealed and superseded (with Sch. 19 of the amending Act) (27.7.1993 with effect for the year 1992-93 and subsequent years of assessment) by 1993 c. 34, ss. 173(2), 213, Sch. 23 Pt. III(12) Note 5
PreliminaryU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .[F3430 Returns by managing agent]U.K.
2(1)An inspector may, at any time after the end of the closing year for a year of assessment, by notice in writing to the managing agent require him to deliver to the inspector, on or before the final day determined under sub-paragraph (2) below, a return of the syndicate profit or loss for the year of assessment—
(a)containing such information as may be required in pursuance of the notice; and
(b)accompanied by such accounts, statements and reports as may be so required.
(2)The final day for the delivery of any return required by a notice under sub-paragraph (1) above is whichever is the later of—
(a)the 1st September next following the end of the closing year for the year of assessment; and
(b)the end of the period of three months beginning on the day following that on which the notice was served.
(3)If the managing agent, having been required by a notice under sub-paragraph (1) above to deliver a return, fails to deliver the return on or before the final date for its delivery, he shall be liable to a penalty equal to the prescribed amount multiplied by the number of days on which the failure continues; and in this sub-paragraph “the prescribed amount” means £60 for each fifty members of the syndicate (counting any number of members less than fifty, and any number left over, as fifty).
(4)If the managing agent fraudulently or negligently delivers an incorrect return under sub-paragraph (1) above, he shall be liable to a penalty not exceeding the prescribed amount multiplied by the number of members of the syndicate; and in this sub-paragraph “the prescribed amount” means £3,000.
(5)In relation to a return required by a notice under sub-paragraph (1) above—
(a)any reference in sub-paragraph (2) or (3) above to the delivery of the return is a reference to its delivery together with the accompanying documents referred to in sub-paragraph (1) above; and
(b)the reference in sub-paragraph (4) above to the return being incorrect includes a reference to any of those documents being incorrect.
[F3431 Repayment claims by managing agent]U.K.
2A(1)In relation to an underwriting year a managing agent may, by notice in writing at any time during the period of six years beginning with 1st March in the closing year for that year, make a claim to the inspector for the repayment of tax suffered by way of deduction on the syndicate investment income allocated to that year in accordance with the rules or practice of Lloyd’s.
(2)The managing agent shall provide such information in support of the claim as the inspector may reasonably require.
(3)Where an amount is repaid to the managing agent under this paragraph, he shall apportion the amount repaid between the members of the syndicate in proportion to their interests in that part of the syndicate investment income which has suffered tax by way of deduction and, where there is a syndicate profit available for distribution to the members, shall pay the amount so apportioned to the members’ agent in relation to each member within 90 days of receipt.
(4)The provisions of section 824 shall not apply to any repayment of tax made under this paragraph.
Returns by members’ agentU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .[F3433 Payments on account of tax]U.K.
3(1)In the case of a member’s profit for a year of assessment, the members’ agent shall, on or before the 1st January next following the end of the closing year for that year, pay to the collector, on account of the member’s liability to tax, the amount stated in his return for that year under paragraph 2B(1)(c) above.
(2)Where an amount is paid to the collector under sub-paragraph (1) above for a year of assessment, the following provisions shall apply as between a member and that members’ agent—
(a)where the amount so paid exceeds the amount deducted by the members’ agent in accounting to the member for that member’s profit, the amount of the excess shall be paid by the member to the members’ agent; and
(b)where the amount so paid is less than the amount deducted by the members’ agent in accounting to the member for that member’s profit, the amount of the excess shall be paid by the members’ agent to the member.
(3)Where an amount is paid to the collector under sub-paragraph (1) above for a year of assessment, the following provisions shall apply as respects the member’s liability to tax for that year—
(a)where the amount in which the member is charged to tax exceeds the amount so paid, the amount of the excess shall be the amount of tax due and payable; and
(b)where that amount exceeds the amount in which the member is so charged, the amount of the excess shall be treated as tax overpaid.
(4)Any amount which is payable under sub-paragraph (1) above shall carry interest at the rate applicable under section 178 of the Finance Act 1989 from the date when it becomes payable until payment, whether or not that date is a non-business day within the meaning of the Bills of Exchange Act 1882, and section 90 of the Taxes Management Act 1970 shall apply for the purposes of this paragraph as it applies for the purposes of any provision of Part IX of that Act.
Assessments on members’ agentU.K.
3A(1)If the members’ agent delivers a return in accordance with paragraph 2B above but does not pay to the collector the amount of tax stated in the return in accordance with paragraph 3 above, the inspector may make an assessment on the members’ agent in that amount whether or not it has been paid when the assessment is made.
(2)If for a year of assessment the inspector is dissatisfied with a return under paragraph 2B above, or there is no such return, he may make an assessment on the members’ agent to the best of his judgment.
(3)Any income tax due under an assessment made by virtue of sub-paragraph (1) or (2) above shall be treated for the purposes of interest on unpaid tax as having been payable at the time when it would have been payable if a correct return had been made.
Determinations by inspectorU.K.
4(1)If the inspector is satisfied that a return under paragraph 2(1) above affords correct and complete information concerning the syndicate profit or loss for a year of assessment, he shall determine that profit or loss accordingly.
(2)If for a year of assessment the inspector is dissatisfied with a return under paragraph 2(1) above, or there is no such return, the inspector shall determine the syndicate profit or loss for that year to the best of his judgment.
(3)If the inspector discovers that a determination under sub-paragraph (1) or (2) above—
(a)understates the syndicate profits for the year of assessment; or
(b)overstates the syndicate losses for that year,
he may, by a determination under this sub-paragraph, vary the first-mentioned determination accordingly.
(4)Notice of a determination under this paragraph shall be served on the [managing F3434] agent and shall state the time within which any appeal against the determination may be made under paragraph 5 below.
(5)After notice of a determination under this paragraph has been served on the [managing F3434] agent, the determination shall not be altered except in accordance with the express provisions of the Taxes Acts.
AppealsU.K.
5(1)The [managing F3435] agent may appeal against a determination under paragraph 4 above by a notice of appeal in writing given to the inspector within thirty days after the date of the notice of determination.
(2)An appeal under this paragraph shall be to the General Commissioners, except that the [managing F3435] agent may elect (in accordance with section 46(1) of the Taxes Management Act 1970) to bring the appeal before the Special Commissioners instead of the General Commissioners; and subsections (5) to (5E) of section 31 of that Act shall apply for the purposes of an election under this sub-paragraph as they apply for the purposes of an election under subsection (4) of that section.
Modification of determinations pending appealU.K.
6(1)Where the [managing F3436] agent appeals against a determination under paragraph 4 above, then, for the purpose of establishing, in the event of a member of the syndicate appealing against an assessment made on him, the amount of tax the payment of which should, pending the determination of that appeal, be postponed under section 55 of the Taxes Management Act 1970, that section shall apply to the first-mentioned appeal with the modifications specified in sub-paragraph (2) below.
(2)The modifications are as follows—
(a)any reference to the notice of assessment shall be construed as a reference to the notice of determination;
(b)any reference to the appellant believing that he is overcharged to tax by the assessment shall be construed as a reference to him believing that the determination overstates the syndicate profits, or understates the syndicate losses, for the year of assessment, and any reference to the appellant having grounds for so believing, or there being reasonable grounds for so believing, shall be construed accordingly;
(c)any reference to a determination of the amount of tax the payment of which should be postponed pending the determination of the appeal shall be construed as a reference to a direction that the determination shall, pending the determination of the appeal, have effect for the purpose stated in sub-paragraph (1) above as if the syndicate profits there stated were reduced, or the syndicate losses there stated were increased, by such amount as may be specified in the direction, and any reference to an amount of tax so determined, or to the amount of tax which should be so postponed, shall be construed accordingly; and
(d)subsections (2) and (9) and, in subsection (6), paragraphs (a) and (b) and the word “and” immediately preceding paragraph (a) shall be omitted.
Apportionments of syndicate profit or lossU.K.
7(1)Where a determination of a syndicate profit or loss for a year of assessment is made, varied or modified (whether under the foregoing provisions of this Schedule or on appeal), the inspector may, by notice in writing to the [managing F3437] agent, require him to make to the inspector, within the specified period, a return apportioning, between the members of the syndicate, the syndicate profit or loss as stated in the determination as so made, varied or modified.
(2)If the [managing F3437] agent, having been required by a notice under sub-paragraph (1) above to deliver a return within the specified period, fails to deliver the return within that period, he shall be liable to a penalty equal to the prescribed amount multiplied by the number of days on which the failure continues; and in this sub-paragraph “the prescribed amount” means £5 for each fifty members of the syndicate (counting any number of members left over as fifty).
(3)In this paragraph “the specified period” means such period, not being less than thirty days and beginning with the day following the date of the notice under sub-paragraph (1) above, as may be specified in that notice.
Individual members: effect of determinationsU.K.
8(1)A determination of a syndicate profit or loss for a year of assessment (whether as originally made or as varied or modified) shall, for the purpose of determining the liability to tax of each member of the syndicate, be conclusive against that member that the syndicate profit or loss for that year is as there stated.
(2)Where a determination of a syndicate profit or loss for a year of assessment is varied or modified at any time after the issue of a notice of assessment assessing any member of the syndicate to tax—
(a)section 31 of the Taxes Management Act 1970 (right of appeal) and section 55 of that Act (postponement of tax) shall have effect, in relation to that member, as if any reference to the date of the notice of assessment, or the date of the issue of the notice of assessment, were a reference to the date of the variation or modification; and
(b)in the case of a variation, an assessment which gives effect to the determination as varied shall not be out of time if it is made within one year of the date of the variation.
(3)Sub-paragraph (2)(b) above shall not apply in the case of a variation under paragraph 4(3) above which is made later than six years after the end of the closing year.
Assessment of individual members: time limitsU.K.
9For the purposes of sections 36, [F3438of the Taxes Management Act 1970 (extension of time in cases of [fraudulent or negligent conduct F3438], anything done or omitted to be done by the [managing F3439] agent shall be deemed to have been done or omitted to be done by each member of the syndicate.]
Supplemental: penaltiesU.K.
10(1)If it appears to an inspector or the Board that the agent is liable to a penalty under paragraph 2(3)or 7(2)above, the amount appearing to be due may be assessed by the inspector or the Board as if it were tax for the year of assessment in which the failure to make the return occurred; and, subject to the provisions of this paragraph, the provisions of the Taxes Management Act 1970relating to the assessment and collection of tax shall apply accordingly.
(2)An amount assessed by way of penalty under paragraph 2(3)or 7(2)above shall be due at the end of the period of thirty days beginning with the date of the issue of the notice of assessment.
(3)On an appeal against an assessment of an amount by way of penalty under sub-paragraphs (3)of paragraph 2or sub-paragraph (2)of paragraph 7above, subsections (6)to (8)of section 50of that Act shall not apply but the Commissioners—
(a)may confirm the amount of the assessment or, if it appears to them that the amount assessed is greater or smaller than the penalty provided for under that sub-paragraph, may reduce it or increase it to such an amount as is appropriate having regard to the provisions of that sub-paragraph; and
(b)if it appears to them that no penalty has been incurred, may set the assessment aside.
(4)Where an amount has been assessed by way of penalty under sub-paragraph (3)of paragraph 2or sub-paragraph (2)of paragraph 7above and either no appeal has been brought against that assessment or the amount assessed has been confirmed or varied on appeal—
(a)a certificate of an inspector or other officer of the Board that an amount is due by way of penalty under that sub-paragraph; and
(b)a certificate of a collector that payment of that amount has not been made to him or, to the best of his knowledge and belief, to any other collector, or to a person acting on his behalf or on behalf of another collector,
shall be sufficient evidence that the amount mentioned in the certificates is unpaid and is due to the Crown; and any document purporting to be such a certificate as is mentioned in this sub-paragraph shall be deemed to be such a certificate unless the contrary is proved.
(5)Section 100of the Taxes Management Act 1970 (procedure for recovery of penalties)shall not apply to a penalty under paragraph 2(3)or 7(2)aboveF3440.
Supplemental: interestU.K.
11(1)Interest charged under paragraph 3(4)above shall be treated for the purposes of the enactments mentioned in section 69of the Taxes Management Act 1970 (interest on tax)as if it were tax charged and due and payable under an assessment.
(2)References to section 86of that Act in sections 70(2)and 92of that Act (evidence, and remission of interest in certain cases)shall include a reference to paragraph 3(4)aboveF3441. F3442]
Section 496A
[F3443SCHEDULE 19BU.K.Petroleum extraction activities: exploration expenditure supplement
Textual Amendments
F3443Sch. 19B inserted (22.7.2004) by Finance Act 2004 (c. 12), s. 286(3), Sch. 38
Part 1 U.K.Introductory
About this ScheduleU.K.
1(1)This Schedule entitles a company carrying on a ring fence trade, on making a claim in respect of an accounting period ending on or after 1st January 2004 [F3444but before 1st January 2006], to a supplement (initially of 6%, but variable by Treasury order) in respect of—
(a)qualifying capital expenditure incurred before the trade is set up and commenced,
(b)losses incurred in the trade, determined by reference to allowances under Part 6 of the Capital Allowances Act (expenditure on research and development) in respect of qualifying capital expenditure, and
(c)some or all of the supplement allowed in respect of earlier periods.
(2)To qualify, the capital expenditure in question must be incurred on or after 1st January 2004 [F3445but before 1st January 2006] in respect of oil and gas exploration and appraisal (as well as satisfying other conditions).
(3)Part 2 makes provision about the application and interpretation of this Schedule.
(4)Part 3 makes provision about supplement in relation to expenditure incurred by the company—
(a)with a view to carrying on a ring fence trade, but
(b)in an accounting period before the company sets up and commences that trade.
(5)Part 4 makes provision about supplement in relation to losses incurred in carrying on the ring fence trade.
(6)There is a limit on the number of accounting periods (6) in respect of which a company may claim supplement.
(7)In determining the amount of supplement allowable, reductions fall to be made in respect of—
(a)disposal receipts by virtue of section 555 of the Capital Allowances Act (disposal of oil licence with exploitation value),
(b)ring fence losses that could be set off under section 393A [F3446or 393B] against ring fence profits of earlier periods,
(c)ring fence losses incurred in earlier periods that fall to be set off under section 393 against profits of succeeding periods,
(d)unrelieved group ring fence profits.
Textual Amendments
F3444Words in Sch. 19B para. 1(1) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(4)(a)
F3445Words in Sch. 19B para. 1(2) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(4)(b)
F3446Words in Sch. 19B para. 1(7)(b) inserted (with effect in accordance with 111(3) of the amending Act) by Finance Act 2008 (c. 9), Sch. 35 para. 8(2)
Part 2 U.K.Application and interpretation
Qualifying companiesU.K.
2This Schedule applies in relation to any company which—
(a)carries on a ring fence trade, or
(b)is engaged in oil and gas exploration and appraisal (see section 837B [F3447of this Act and section 1003 of ITA 2007]) with a view to carrying on a ring fence trade,
and in this Schedule any such company is referred to as a “qualifying company”.
Textual Amendments
F3447Words in Sch. 19B para. 2(b) inserted (6.4.2007 with effect in accordance with s. 1034(1) of the amending Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 236 (with Sch. 2)
Accounting periodsU.K.
3(1)In this Schedule, in the case of any qualifying company,—
“the commencement period” means the accounting period in which the company sets up and commences its ring fence trade;
“post-commencement period” means any accounting period ending on or after 1st January 2004 [F3448but before 1st January 2006]—
(a)which is the commencement period, or
(b)which ends after the commencement period;
“pre-commencement period” means any accounting period ending—
(a)on or after 1st January 2004 [F3449but before 1st January 2006], and
(b)before the commencement period.
(2)For the purposes of this Schedule a company not within the charge to corporation tax which incurs qualifying E&A expenditure is to be treated as having such accounting periods as it would have if—
(a)it carried on a trade consisting of the activities in respect of which the expenditure is incurred, and
(b)it had started to carry on that trade when it started to carry on the research and development on which the expenditure is incurred.
[F3450(3)In the case of an accounting period (a “straddling period”) of any qualifying company beginning before 1st January 2006 and ending on or after that date—
(a)so much of the straddling period as falls before 1st January 2006, and
(b)so much of the straddling period as falls on or after that date,
are treated as separate accounting periods for the purposes of this Schedule.
(4)Special provision is made elsewhere in this Schedule in relation to straddling periods (see paragraphs 16, 18A and 22).]
Textual Amendments
F3448Words in Sch. 19B para. 3(1) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(5)(a)
F3449Words in Sch. 19B para. 3(1) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(5)(b)
F3450Sch. 19B para. 3(3)(4) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(5)(c)
The relevant percentageU.K.
4(1)For the purposes of this Schedule, the relevant percentage for any accounting period ending on or after 1st January 2004 is 6%.
(2)The Treasury may by order vary the percentage for the time being specified in sub-paragraph (1) for such accounting periods as may be specified in the order.
Limit on number of accounting periods for which supplement may be claimedU.K.
5(1)A company may claim supplement under this Schedule in respect of no more than 6 accounting periods.
(2)The accounting periods in respect of which claims are made need not be consecutive.
Qualifying E&A expenditureU.K.
6(1)For the purposes of this Schedule “qualifying E&A expenditure”is any expenditure as respects which the following conditions are satisfied.
(2)Condition 1 is that the expenditure is incurred on or after 1st January 2004 [F3451but before 1st January 2006].
(3)Condition 2 is that, for the purposes of Part 6 of the Capital Allowances Act, the expenditure is qualifying expenditure incurred on research and development consisting of oil and gas exploration and appraisal (see section 437(2)(b) of that Act).
(4)Condition 3 is that an allowance under section 441 of that Act is claimed in respect of the expenditure.
(5)Condition 4 is that the expenditure is incurred in the course of oil extraction activities.
(6)Condition 5 is that—
(a)those oil extraction activities are comprised in a ring fence trade, or
(b)after incurring the expenditure, the person incurring it sets up and commences a ring fence trade connected with the research and development [F3452or starts to be within the charge to corporation tax in respect of such a ring fence trade.]
Textual Amendments
F3451Words in Sch. 19B para. 6(2) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(6)
F3452Words in Sch. 19B para. 6(6)(b) inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 283 (with Sch. 2 Pts. 1, 2)
Unrelieved group ring fence profits for accounting periodsU.K.
7(1)There is an amount of unrelieved group ring fence profits for an accounting period of a qualifying company (“company Q”) in any case where—
(a)the company and any other company (“company X”) are members of the same group of companies, within the meaning given by section 413(3)(a), and
(b)company X has an amount of taxable ring fence profits (see paragraph 8) for a corresponding accounting period.
(2)An accounting period of company X corresponds to an accounting period of company Q if—
(a)it coincides with, or falls wholly within, the accounting period of company Q, or
(b)it falls partly within the accounting period of company Q.
(3)Where an accounting period of company X—
(a)coincides with an accounting period of company Q, or
(b)falls wholly within an accounting period of company Q,
there is, for the accounting period of company Q, an amount of unrelieved group ring fence profits equal to the whole of company X’s taxable ring fence profits for its accounting period.
(4)Where an accounting period of company X falls partly within an accounting period of company Q—
(a)there is an amount of unrelieved group ring fence profits for the accounting period of company Q, and
(b)that amount is an amount equal to the part of company X’s taxable ring fence profits for its accounting period that is attributable, on an apportionment in accordance with section 834(4), to the part of that period which falls within the accounting period of company Q.
(5)This paragraph applies for the purposes of this Schedule.
Taxable ring fence profits of an accounting periodU.K.
8For the purposes of this Schedule, a company has taxable ring fence profits for an accounting period if it has an amount of ring fence profits which is chargeable to corporation tax for that accounting period after any group relief claimed under Chapter 4 of Part 10.
Part 3 U.K.Pre-commencement supplement
Supplement in respect of a pre-commencement accounting periodU.K.
9(1)Where—
(a)a qualifying company claims an allowance under section 441 of the Capital Allowances Act (research and development allowances) for the commencement period, and
(b)the claim is for an allowance in respect of qualifying E&A expenditure incurred before that period,
the company may also claim supplement under this Part of this Schedule (“pre-commencement supplement”) in respect of one or more pre-commencement periods.
(2)Any pre-commencement supplement allowed on a claim in respect of a pre-commencement period shall be treated as an allowance under Part 6 of the Capital Allowances Act for the commencement period in respect of qualifying E&A expenditure incurred by the company.
(3)The amount of the supplement for any pre-commencement period in respect of which a claim under this paragraph is made is the relevant percentage for that period of the reference amount for that period.
(4)If the pre-commencement period is a period of less than twelve months, the amount of the supplement for the period (apart from this sub-paragraph) shall be reduced proportionally.
(5)Paragraphs 10 to 13 have effect for the purpose of determining the reference amount for a pre-commencement period.
The mixed pool of qualifying E&A expenditure and supplement previously allowedU.K.
10(1)For the purpose of determining the amount of any pre-commencement supplement, a qualifying company shall be taken to have had, at all times in the pre-commencement periods of the company, a continuing mixed pool of qualifying E&A expenditure and pre-commencement supplement.
(2)The pool shall be taken to have consisted of—
(a)the company’s qualifying E&A expenditure, allocated to the pool for each pre-commencement period in accordance with sub-paragraph (3), and
(b)the company’s pre-commencement supplement, allocated to the pool for each pre-commencement period in accordance with sub-paragraph (4).
(3)To allocate qualifying E&A expenditure to the pool for any pre-commencement period, take the following steps—
(a)Step 1: count as eligible expenditure for that period so much of the qualifying E&A expenditure mentioned in paragraph 9(1)(b) as was incurred in that period,
(b)Step 2: find the total of all the eligible expenditure for that period (amount E),
(c)Step 3: if paragraph 11 applies, reduce amount E in accordance with that paragraph,
(d)Step 4: if paragraph 12 applies, reduce (or, as the case may be, further reduce) amount E in accordance with that paragraph,
and so much of amount E as remains after making those reductions shall be taken to have been added to the pool in that period.
(4)If any pre-commencement supplement is allowed on a claim in respect of a pre-commencement period, the amount of that supplement shall be taken to have been added to the pool in that period.
Treatment of disposal value on disposal of oil licence with exploitation valueU.K.
11(1)This paragraph applies in any case where—
(a)the qualifying company disposes of an interest in an oil licence in a pre-commencement period,
(b)part of the value of the interest (the “deductible amount”) is attributable to qualifying E&A expenditure incurred by the company, and
(c)section 555 of the Capital Allowances Act (disposal of oil licence with exploitation value) has effect in relation to the disposal.
(2)For the purpose of allocating qualifying E&A expenditure to the pool for each pre-commencement period—
(a)find the total of the deductible amounts in the case of all such disposals made by the company (amount D), and
(b)taking later periods before earlier periods, reduce (but not below nil) amount E for any pre-commencement period by setting against it so much of amount D as does not fall to be set against amount E for a later pre-commencement period.
(3)In this paragraph “oil licence” has the same meaning as in section 555 of the Capital Allowances Act (see section 552 (1) of that Act).
Reduction in respect of unrelieved group ring fence profitsU.K.
12(1)This paragraph applies if there is an amount of unrelieved group ring fence profits for a pre-commencement period.
(2)For the purpose of allocating qualifying E&A expenditure to the pool for that period—
(a)find so much (if any) of amount E for that period as remains after any reduction falling to be made under paragraph 11, and
(b)reduce that amount (but not below nil) by setting against it a sum equal to the aggregate of the amounts of unrelieved group ring fence profits for the period.
The reference amount for a pre-commencement periodU.K.
13For the purposes of this Part of this Schedule, the reference amount for a pre-commencement period is the amount in the pool at the end of the period—
(a)after the addition to the pool of any qualifying E&A expenditure allocated to the pool for that period in accordance with paragraph 10(3), but
(b)before determining, and adding to the pool, the amount of any pre-commencement supplement claimed in respect of the period.
Claims for pre-commencement supplementU.K.
14(1)Any claim for pre-commencement supplement in respect of a pre-commencement period must be made at the same time as, and as if it were part of, the claim under section 441 of the Capital Allowances Act mentioned in paragraph 9(1)(a).
(2)Subsection (3) of that section (claim for reduced amount) applies in relation to any such claim.
Part 4 U.K.Post-commencement supplement
Supplement in respect of a post-commencement periodU.K.
15(1)A qualifying company which incurs a qualifying E&A loss (see paragraph 17) in a post-commencement period may claim supplement under this Part of this Schedule (“post-commencement supplement”) in respect of—
(a)that period, or
(b)any subsequent accounting period in which it carries on its ring fence trade.
(2)Any post-commencement supplement allowed on a claim in respect of a post-commencement period shall be treated for the purposes of the Corporation Tax Acts (other than this Part of [F3453this Schedule or [F3454sections 321 to 329 of CTA 2010])] as if it were a loss—
(a)incurred in carrying on the ring fence trade in that period,
(b)which falls in whole to be set off under section 393 against trading income from the ring fence trade in succeeding accounting periods.
(3)Paragraph 74 of Schedule 18 to the Finance Act 1998 (company tax returns etc: time limit for claims for group relief) shall apply in relation to a claim for post-commencement supplement as it applies in relation to a claim for group relief.
Textual Amendments
F3453Words in Sch. 19B para. 15(2) substituted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(7)
F3454Words in Sch. 19B para. 15(2) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 142(2) (with Sch. 2)
Amount of post-commencement supplement for a post-commencement periodU.K.
16(1)The amount of the post-commencement supplement for any post-commencement period in respect of which a claim under paragraph 15 is made is the relevant percentage for that period of the reference amount for that period.
(2)If the post-commencement period is a period of less than twelve months, the amount of the supplement for the period (apart from this sub-paragraph) shall be reduced proportionally.
[F3455(2A)But, if the post-commencement period is the deemed accounting period under paragraph 3(3) ending before 1st January 2006, sub-paragraph (2) has no effect in relation to the amount of the supplement for that period.]
(3)Paragraphs 19 to 24 have effect for the purpose of determining the reference amount for a post-commencement period.
Textual Amendments
F3455Sch. 19B para. 16(2A) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(8)
Ring fence losses and qualifying E&A lossesU.K.
17(1)Where—
(a)in any post-commencement period (“the period of the loss”) a qualifying company carrying on a ring fence trade incurs a loss in the trade, and
(b)some or all of the loss falls to be set off under section 393 against trading income from the trade in succeeding accounting periods,
so much of the loss as falls to be so set off is a “ring fence loss” of the company.
(2)In determining for the purposes of this Part of this Schedule how much of a loss incurred in a ring fence trade falls to be set off as mentioned in sub-paragraph (1)(b), it shall be assumed—
[F3456(a)]that every claim is made that could be made by the company under section 393A to set losses incurred in the ring fence trade against ring fence profits of earlier post-commencement periods, [F3457and
(b)that (where appropriate) section 393B applies in relation to every such claim.]
(3)So much of a ring fence loss as is attributable to qualifying E&A allowances for the period of the loss is a “qualifying E&A loss”.
(4)A ring fence loss is attributable to qualifying E&A allowances to the extent that the amount of the ring fence loss does not exceed the amount of the qualifying E&A allowances for the period of the loss.
(5)But a claim for post-commencement supplement may include an election for a ring fence loss to be treated—
(a)as attributable to qualifying E&A allowances for the period of the loss to such lesser extent as may be specified in the election, or
(b)as not attributable to such allowances.
(6)“Qualifying E&A allowances”, in the case of an accounting period, means allowances for that period under Part 6 of the Capital Allowances Act in respect of qualifying E&A expenditure incurred by the company (including any pre-commencement supplement treated under paragraph 9(2) as such an allowance).
(7)This paragraph has effect for the purposes of this Part of this Schedule.
Textual Amendments
F3456Words in Sch. 19B para. 17(2) renumbered as para. 17(2)(a) (with effect in accordance with 111(3) of the amending Act) by virtue of Finance Act 2008 (c. 9), Sch. 35 para. 8(3)(a)
F3457Sch. 19B para. 17(2)(b) and preceding word inserted (with effect in accordance with 111(3) of the amending Act) by Finance Act 2008 (c. 9), Sch. 35 para. 8(3)(b)
Ring fence losses and non-qualifying lossesU.K.
18(1)So much of a ring fence loss as is not a qualifying E&A loss is a non-qualifying loss.
(2)Where—
(a)a loss was incurred by a qualifying company in its ring fence trade in an accounting period ending on or before 31st December 2003, and
(b)some or all of that loss falls to be set off under section 393 against profits of that trade in accounting periods ending on or after that date,
so much of the loss as falls to be so set off is a ring fence loss and that loss is a non-qualifying loss.
(3)This paragraph has effect for the purposes of this Part of this Schedule.
Special rule for straddling periodsU.K.
[F345818A(1)This paragraph applies in any case where the period of the loss in which a ring fence loss is incurred is the deemed accounting period under paragraph 3(3) ending before 1st January 2006.
(2)The following assumption shall be made for the purpose of calculating the amount of the qualifying E&A loss and the amount of the non-qualifying loss.
(3)The assumption is that the loss made in the trade is taken to be the loss incurred in the accounting period beginning before 1st January 2006 and ending on or after that date (disregarding paragraph 3(3)).
(4)The amount of the non-qualifying loss (found in accordance with that assumption) is then reduced (but not below nil) by the following amount.
(5)The amount is the amount of the ring fence loss in the deemed accounting period beginning on 1st January 2006 determined under [F3459section 324 of CTA 2010].]
Textual Amendments
F3458Sch. 19B para. 18A inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(9)
F3459Words in Sch. 19B para. 18A(5) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 142(3) (with Sch. 2)
The pool of qualifying E&A losses and the pool of non-qualifying lossesU.K.
19(1)For the purpose of determining the amount of any post-commencement supplement, a qualifying company shall be taken at all times in its post-commencement periods to have—
(a)a continuing pool of the company’s non-qualifying losses (the “non-qualifying pool”), and
(b)a continuing mixed pool of the company’s qualifying E&A losses and post-commencement supplement (the “qualifying pool”).
(2)A pool continues even if the amount in it is nil.
The non-qualifying poolU.K.
20(1)The non-qualifying pool consists of the company’s non-qualifying losses, allocated to the pool in accordance with sub-paragraph (2).
(2)A non-qualifying loss is allocated to the pool by adding the amount of the non-qualifying loss to the pool in the period of the loss.
(3)In the case of a non-qualifying loss incurred in an accounting period ending on or before 31st December 2003, the period of the loss shall be taken for the purposes of sub-paragraph (2) to be the first accounting period of the company that ends on or after 1st January 2004.
(4)The amount in the non-qualifying pool is subject to reductions in accordance with the following provisions of this Part of this Schedule.
(5)Where a reduction in the amount in the non-qualifying pool falls to be made in any accounting period—
(a)the reduction is to be made after the addition to the pool of any non-qualifying loss allocated to the pool in that period in accordance with sub-paragraph (2), and
(b)references to the amount in the non-qualifying pool shall be construed accordingly.
The qualifying poolU.K.
21(1)The qualifying pool consists of—
(a)the company’s qualifying E&A losses, allocated to the pool in accordance with sub-paragraph (2)(a), and
(b)the company’s post-commencement supplement, allocated to the pool in accordance with sub-paragraph (2)(b).
(2)The allocation of qualifying E&A losses and post-commencement supplement to the pool is as follows—
(a)the amount of a qualifying E&A loss is added to the pool in the period of the loss, and
(b)if any post-commencement supplement is allowed on a claim in respect of a post-commencement period, the amount of that supplement is added to the pool in that period.
(3)The amount in the qualifying pool is subject to reductions in accordance with the following provisions of this Part of this Schedule.
(4)Where a reduction in the amount in the qualifying pool falls to be made in any accounting period, the reduction is to be made—
(a)after the addition to the pool of the amount of any qualifying E&A losses allocated to the pool in that period in accordance with sub-paragraph (2)(a), but
(b)before determining, and adding to the pool, the amount of any supplement claimed in respect of the period,
and references to the amount in the pool shall be construed accordingly.
Reductions in respect of utilised ring fence lossesU.K.
22(1)If one or more ring fence losses are set off under section 393 against any profits of a post-commencement period, reductions shall be made in that period in accordance with this paragraph.
(2)The amount in the non-qualifying pool shall be reduced (but not below nil) by setting against it a sum equal to the total amount so set off.
(3)If any of that sum remains after being so set against the amount in the non-qualifying pool, the amount in the qualifying pool shall be reduced (but not below nil) by setting against it so much of that sum as so remains.
[F3460(4)If the post-commencement period is the deemed accounting period under paragraph 3(3) ending before 1st January 2006 (“the deemed accounting period”), the amount of the profits of the deemed accounting period is determined as follows.
(5)The amount of the profits of the straddling period is apportioned to the deemed accounting period in proportion to the number of days in the deemed accounting period that fall in the straddling period.
(6)The apportioned amount is taken for the purposes of this paragraph to be the amount of the profits of the deemed accounting period.
(7)In this paragraph “the straddling period”, in relation to a qualifying company, means an accounting period of the company beginning before 1st January 2006 and ending on or after that date (disregarding paragraph 3(3)).]
Textual Amendments
F3460Sch. 19B para. 22(4)-(7) inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(10)
Reductions in respect of unrelieved group ring fence profitsU.K.
23(1)If there is an amount of unrelieved group ring fence profits for a post-commencement period, reductions shall be made in that period in accordance with this paragraph.
(2)In the following provisions of this paragraph, references to the remaining amount in a pool are references to so much (if any) of the amount in the pool as remains after making any reductions that fall to be made in accordance with paragraph 22.
(3)The remaining amount in the non-qualifying pool shall be reduced (but not below nil) by setting against it a sum equal to the aggregate of the amounts of unrelieved group ring fence profits for the period.
(4)If any of that sum remains after being so set against the remaining amount in the non-qualifying pool, the remaining amount in the qualifying pool shall be reduced (but not below nil) by setting against it so much of that sum as so remains.
The reference amount for a post-commencement periodU.K.
24For the purposes of this Part of this Schedule the reference amount for a post-commencement period is so much of the amount in the qualifying pool as remains after making any reductions required by paragraph 22 or 23.]
F3461F3461[F3462SCHEDULE 19C]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3461Sch. 19C repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 143, Sch. 3 Pt. 1 (with Sch. 2)
F3462Sch. 19C inserted (19.7.2006) by Finance Act 2006 (c. 25), s. 154(11), Sch. 19
F3470F3470SCHEDULE 20U.K.
Textual Amendments
F3470Sch. 20 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 144, Sch. 3 Pt. 1 (with Sch. 2)
PART IU.K. QUALIFYING INVESTMENTS
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IIU.K. QUALIFYING LOANS
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F3486F3486PART IIIU.K. ATTRIBUTION OF EXCESS NON-QUALIFYING EXPENDITURE TO EARLIER CHARGEABLE PERIODS
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Sections 570 and 572.
SCHEDULE 21U.K. TAX RELIEF IN CONNECTION WITH SCHEMES FOR RATIONALIZING INDUSTRY AND OTHER REDUNDANCY SCHEMES M290
PART IU.K. PRELIMINARY
1(1)In this Schedule—U.K.
“scheme” means a scheme which is for the time being certified or has at any time been certified by the Secretary of State under section 568;
“payment” means a payment made under a scheme, being a payment made to a person carrying on a trade to which the scheme relates and not being a payment made by way of repayment of contributions;
“the person chargeable” means, in relation to any such payment, the person liable to pay any tax which may fall to be paid by reason of the receipt of the payment;
“damage” includes any loss, liability, expense or other burden, and references to the amount of any damage are references to the sum which would be fair compensation for that damage;
“contribution” includes part of a contribution, and “deductible contribution” means a contribution allowed to be deducted under section 568, any reduction under Part III of this Schedule being left out of account; and
“asset” includes part of an asset.
(2)For the purposes of this Schedule, a sum received by any person by way of repayment of contributions shall be deemed to be by way of repayment of the last contribution paid by him, and, if the sum exceeds the amount of that contribution, by way of repayment of the penultimate contribution so paid, and so on.
PART IIU.K. RELIEF IN RESPECT OF CERTAIN PAYMENTS
2U.K.The question whether any, and if so, what, relief is to be given shall be determined separately in relation to each payment made under the scheme in respect of the trade, but for the purpose of determining that question regard shall be had, as provided by the following provisions of this Part of this Schedule, to the sum (“the total payment”) produced by adding the amount of the payment to the amount of any payments previously so made.
3U.K.F3488. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3488Sch. 21 para. 3 repealed (with effect in accordance with s. 134(2) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 20 para. 43, Sch. 41 Pt. 5(10), Note
4U.K.No relief shall be given in respect of the payment unless the total payment, or the amount of the damage in respect of which the total payment has been made, whichever is the smaller, exceeds the aggregate amount of the deductible contributions which have been paid in furtherance of the scheme in respect of the trade in question before the payment is made, exclusive of any contributions which have been repaid before the payment is made.
5U.K.The amount of the reduction to be made in respect of the payment shall be arrived at by—
(a)ascertaining the sum which bears to the excess mentioned in paragraph 4 above the same proportion that the amount mentioned in paragraph 3(b) above bears to the amount mentioned in paragraph 3(a); and
(b)deducting from that sum the total amount of any reductions which have been or fall to be made under this Schedule in respect of payments previously made under the scheme in respect of the trade.
6(1)For the purposes of this Schedule, and subject to sub-paragraph (2) below, damage shall be deemed to be damage in respect of which relief may be given under the Tax Acts if and only if—U.K.
(a)the damage is attributable to any of the following events, that is to say, the demolition, destruction or putting out of use of any asset, or the disposition or termination of an interest in any asset, and, by reason of that event, an allowance falls to be made under [F3489Part 2 or 3 of the Capital Allowances Act in calculating the profits of a trade]; or
(b)the damage consists of any loss, liability, expense or other burden in respect of which an allowance may be made in computing the [F3490profits] of the trade for the purposes of the Tax Acts.
(2)F3491. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)Where any event occurs which would give rise to an allowance under the Tax Acts in respect of any asset in taxing, or computing the [F3490profits] of, a trade but for any of the following matters, that is to say—
(a)that there are no [F3490profits] against which the allowance could be made, or
(b)that account is required to be taken of allowances previously made or deemed to have been made in respect of the asset; or
(c)that account is required to be taken of any sum which falls to be written off the expenditure incurred on the asset for the purpose of determining whether any and if so what allowance may be given by reason of the event; or
(d)that account is required to be taken of any sum falling to be taken into account as sale, insurance, salvage or compensation moneys, the like consequences shall ensue under this Schedule as if an allowance had fallen to be made by reason of that event.
(4)Where any damage is attributable to a permanent change in the purposes for which an asset is used, or the temporary or permanent putting out of use of an asset, the question whether the damage is damage in respect of which relief may be given under the Tax Acts shall be determined as if the damage had been attributable to a sale of the asset on the date upon which the change or putting out of use took place.
Textual Amendments
F3489Words in Sch. 21 para. 6(1)(a) substituted (with effect in accordance with s. 579 of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 65
F3490Words in Sch. 21 para. 6(1)(b)(3) substituted (31.7.1998) by Finance Act 1998 (c. 36), s. 46(3)(a), Sch. 7 para. 1
F3491Sch. 21 para. 6(2) repealed (with effect in accordance with s. 164(1)(2) of the repealing Act) by Capital Allowances Act 1990 (c. 1), s. 164(4)(5), Sch. 2
PART IIIU.K. EXCLUSION OF RELIEF IN RESPECT OF CONTRIBUTIONS PAID AFTER RELIEF HAS BEEN GIVEN UNDER PART II
7U.K.The provisions of this Part of this Schedule shall have effect where—
(a)a contribution is paid under a scheme in respect of a trade; and
(b)before the contribution is paid, payments have been made under the scheme to the person carrying on the trade; and
(c)reductions have been made, under Part II of this Schedule, in the amounts which, by reason of those payments, are to be treated as trading receipts of the trade.
8U.K.There shall be ascertained—
(a)the total amount of those reductions; and
(b)the sum by which that total would have been decreased if the contribution, and any previous contributions to which this Part of this Schedule applies, had been paid before any of the payments were made.
9U.K.For the purpose of determining what deduction is to be made in respect of the contribution under section 568, the contribution shall be deemed to be reduced by the sum specified in paragraph 8(b) above, but—
(a)for the purpose of the application of paragraph 8 above in relation to contributions subsequently paid under the scheme in respect of the trade, the total amount of the reductions referred to in that paragraph shall be treated as decreased by that sum; and
(b)for the purpose of the application of paragraph 5 above in relation to payments subsequently made under the scheme in respect of the trade, the total amount of the reductions referred to in that paragraph shall be treated as decreased by that sum.
10U.K.When two or more contributions are paid at the same time, the provisions of this Part of this Schedule shall have effect as if they were a single contribution.
F3492F3492SCHEDULE 22U.K.
Textual Amendments
F3492Sch. 22 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
1(1)The Board may make regulations providing for this Schedule to apply, as from a prescribed date, in relation to any exempt approved scheme which is of a prescribed kind.
(2)The Board may make regulations providing for prescribed provisions of this Schedule to apply, as from a prescribed date, in prescribed circumstances, and subject to any prescribed omissions or modifications, in relation to any exempt approved scheme of another prescribed kind.
(3)In this Schedule “prescribed” means prescribed by regulations made by the Board.
2(1)The administrator of a scheme in relation to which this Schedule applies shall, in prescribed circumstances and at a prescribed time, either produce to the Board a written valuation such as is mentioned in sub-paragraph (2) below or give to the Board a certificate such as is mentioned in sub-paragraph (3) below.
(2)The valuation must be a valuation of the assets held for the purposes of the scheme and the liabilities of the scheme, must be determined in accordance with prescribed principles and fulfil prescribed requirements, and must be signed by a person with qualifications of a prescribed kind.
(3)The certificate must state whether or not the value of the assets (as determined in accordance with prescribed principles) exceeds the value of the liabilities (as so determined) by a percentage which is more than a prescribed maximum, must be in a prescribed form, and must be signed by a person with qualifications of a prescribed kind.
3(1)Subject to paragraph 4(4) below, where a valuation produced under paragraph 2 shows, or a certificate given under that paragraph states, that the value of the assets exceeds the value of the liabilities by a percentage which is more than the prescribed maximum, the administrator of the scheme shall within a prescribed period submit to the Board for their approval proposals which comply with sub-paragraph (2) below.
(2)The proposals must be proposals for reducing (or, subject to paragraph (b) below, eliminating) the excess in a way or ways set out in the proposals and falling within sub-paragraph (3) below; and they must be such as to secure that—
(a)by the end of a prescribed period the percentage (if any) by which the value of the assets exceeds the value of the liabilities is no more than the prescribed maximum; and
(b)if the way, or one of the ways, set out in the proposals falls within sub-paragraph (3)(a) below, there remains an excess which is of a level not less than the prescribed minimum.
(3)Subject to sub-paragraph (4) below, the permitted ways of reducing or eliminating the excess are—
(a)making payments to an employer;
(b)suspending for a period (of five years or less) set out in the proposals an employer’s obligation to pay contributions under the scheme or reducing for such a period the amount of an employer’s contributions under the scheme;
(c)suspending for a period (of five years or less) set out in the proposals the obligation of employees to pay contributions under the scheme or reducing for such a period the amount of employees’ contributions under the scheme;
(d)improving existing benefits provided under the scheme;
(e)providing new benefits under the scheme;
(f)such other ways as may be prescribed.
(4)In prescribed circumstances sub-paragraph (3) above shall apply subject to such omissions or modifications as may be prescribed.
(5)Subject to paragraph 4(4) below, if the administrator of the scheme fails to submit proposals to the Board within the period mentioned in subparagraph (1) above, or if the proposals submitted to them within that period are not approved by the Board within a further prescribed period, paragraph 7 below shall apply.
4(1)Where a valuation has been produced under paragraph 2 above, the Board may serve on the administrator of the scheme a notice requiring him to furnish the Board, within a prescribed period, with such particulars relating to the valuation as may be specified in the notice.
(2)Where a certificate has been given under paragraph 2 above, the Board may serve on the administrator of the scheme a notice requiring him to produce to the Board, within a prescribed period, a written valuation such as is mentioned in paragraph 2(2) above.
(3)Where a valuation has been produced in compliance with a notice served under sub-paragraph (2) above, the Board may serve on the administrator of the scheme a further notice requiring him to furnish the Board, within a prescribed period, with such particulars relating to the valuation as may be specified in the notice.
(4)Where a notice is served on the administrator of a scheme under sub-paragraph (1) or (2) above, paragraph 3(1) and (5) above shall cease to apply.
5(1)Where particulars have been furnished under paragraph 4 above, or a valuation has been produced under that paragraph, the Board shall, within a prescribed period, serve on the administrator of the scheme a notice—
(a)stating that they accept the valuation produced under paragraph 2 or, as the case may be, 4 above; or
(b)stating that they do not accept the valuation so produced, and specifying their estimate of the value of the liabilities of the scheme at the relevant time and their estimate of the value of the assets held for the purposes of the scheme at that time.
(2)For the purposes of sub-paragraph (1)(b) above, the relevant time is the time specified in the valuation produced under paragraph 2 or 4 above as the time by reference to which the values of the assets and liabilities are determined.
(3)Where—
(a)in a case falling within sub-paragraph (1)(a) above, the valuation shows that the value of the assets exceeds the value of the liabilities by a percentage which is more than the prescribed maximum; or
(b)in a case falling within sub-paragraph (1)(b) above, the value of the assets as estimated by the Board exceeds the value of the liabilities as so estimated by a percentage which is more than the prescribed maximum;
the administrator of the scheme shall within a prescribed period submit to the Board for their approval proposals which comply with paragraph 3(2) to (4) above.
(4)If the administrator of the scheme fails to submit proposals to the Board within the period mentioned in sub-paragraph (3) above, or if proposals submitted to them within that period are not approved by the Board within a further prescribed period, paragraph 7 below shall apply.
6(1)Where proposals are submitted to the Board under paragraph 3(1) or 5(3) above and they approve them within the further prescribed period mentioned in paragraph 3(5) or 5(4) above, the administrator of the scheme shall carry out the proposals within the period mentioned in paragraph 3(2) above.
(2)If the administrator fails to carry out the proposals within that period, paragraph 7 below shall apply.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .8(1)The Board may make regulations providing that an appeal may be brought against a notice under paragraph 5(1)(b) above as if it were notice of the decision of the Board on a claim made by the administrator of the scheme concerned.
(2)Regulations under this paragraph may include—
(a)provision that bringing an appeal shall suspend the operation of paragraph 5(3) and (4) above; and
(b)other provisions consequential on the provision that an appeal may be brought (including provisions modifying this Schedule).
F3495F3495SCHEDULE 23U.K.
Textual Amendments
F3495Sch. 23 repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
PreliminaryU.K.
1(1)This Schedule shall be deemed to have come into force on 17th March 1987 and, subject to sub-paragraphs (2) and (3) below, applies in relation to any retirement benefits scheme approved by the Board before the passing of the Finance (No.2) Act 1987 (23rd July 1987).
[F3496(2)The Board may by regulations provide that, in circumstances prescribed in the regulations, this Schedule or any provision of it shall not apply or shall apply with such modifications as may be so prescribed.
(2A)Regulations under sub-paragraph (2) above—
(a)may include provision authorising the Board to direct that this Schedule or any provision of it shall not apply in any particular case where in the opinion of the Board the facts are such that its application would not be appropriate;
(b)may take effect (and may authorise any direction given under them to take effect) as from 17th March 1987 or any later date;
(c)may make such supplementary provision as appears to the Board to be necessary or expedient.]
(3)This Schedule shall not apply to a retirement benefits scheme if, before the end of 1987, the administrator of the scheme gave notice to the Board that it is not to apply.
(4)Where a notice is given to the Board under sub-paragraph (3) above, the scheme shall, with effect from 17th March 1987 or (if later) the date with effect from which it was approved, cease to be approved.
Accelerated accrualU.K.
2(1)This paragraph applies where an employee becomes a member of the scheme on or after 17th March 1987.
(2)Notwithstanding anything to the contrary in the rules of the scheme, they shall have effect as if they did not allow the provision for the employee of a pension exceeding one-thirtieth of his relevant annual remuneration for each year of service up to a maximum of 20.
3(1)This paragraph applies where an employee becomes a member of the scheme on or after 17th March 1987 and the scheme allows him to commute his pension or part of it for a lump sum or sums.
(2)If the employee’s full pension (that is, the pension before any commutation) is equal to or less than a basic rate commutable pension, the rules of the scheme shall have effect (notwithstanding anything in them to the contrary) as if they did not allow him to obtain by way of commutation a lump sum or sums exceeding in all a basic rate lump sum.
(3)If the employee’s full pension is greater than a basic rate commutable pension but less than a maximum rate commutable pension, the rules of the scheme shall have effect (notwithstanding anything in them to the contrary) as if they did not allow him to obtain by way of commutation a lump sum or sums exceeding in all the aggregate of—
(a)a basic rate lump sum, and
(b)an amount equal to the relevant percentage of the difference between a basic rate lump sum and a maximum rate lump sum.
(4)In this paragraph, as it applies in relation to an employee—
(a)a “basic rate commutable pension” means a pension of one-sixtieth of his relevant annual remuneration for each year of service up to a maximum of 40;
(b)a “maximum rate commutable pension” means a pension of one-thirtieth of his relevant annual remuneration for each year of service up to a maximum of 20;
(c)a “basic rate lump sum” means a lump sum of three-eightieths of his relevant annual remuneration for each year of service up to a maximum of 40;
(d)a “maximum rate lump sum” means a lump sum of such amount as may be determined by or under regulations made by the Board for the purposes of this paragraph and paragraph 4 below;
(e)“the relevant percentage” means the difference between a basic rate commutable pension and the employee’s full pension expressed as a percentage of the difference between a basic rate commutable pension and a maximum rate commutable pension.
4(1)This paragraph applies where an employee becomes a member of the scheme on or after 17th March 1987 and the scheme provides a lump sum or sums for him otherwise than by commutation of his pension or part of it.
(2)If the employee’s pension is equal to or less than a basic rate non-commutable pension, the rules of the scheme shall have effect (notwithstanding anything in them to the contrary) as if they did not allow the payment to him, otherwise than by way of commutation, of a lump sum or sums exceeding in all a basic rate lump sum.
(3)If the employee’s pension is greater than a basic rate non-commutable pension but less than a maximum rate non-commutable pension the rules of the scheme shall have effect (notwithstanding anything in them to the contrary) as if they did not allow the payment to him, otherwise than by way of commutation, of a lump sum or sums exceeding in all the aggregate of—
(a)a basic rate lump sum, and
(b)an amount equal to the relevant percentage of the difference between a basic rate lump sum and a maximum rate lump sum.
(4)In this paragraph, as it applies in relation to an employee—
(a)a “basic rate non-commutable pension” means a pension of one-eightieth of his relevant annual remuneration for each year of service up to a maximum of 40,
(b)a “maximum rate non-commutable pension” means a pension of one-fortieth of his relevant annual remuneration for each year of service up to a maximum of 20,
(c)“basic rate lump sum” and “maximum rate lump sum” have the same meanings as in paragraph 3 above, and
(d)“the relevant percentage” means the difference between a basic rate non-commutable pension and the employee’s actual pension expressed as a percentage of the difference between a basic rate non-commutable pension and a maximum rate non-commutable pension.
Final remunerationU.K.
5(1)his paragraph applies where an employee who is a member of the scheme retires on or after 17th March 1987.
(2)The rules of the scheme shall have effect as if they provided that in determining the employee’s relevant annual remuneration for the purpose of calculating benefits, no account should be taken of anything excluded from the definition of “remuneration” in section 612(1).
(3)In the case of an employee—
(a)whose employer is a company and who at any time in the last ten years of his service is a controlling director of the company, or
(b)whose relevant annual remuneration for the purpose of calculating benefits, so far as the remuneration is ascertained by reference to years beginning on or after 6th April 1987, would (apart from this Schedule) exceed the permitted maximum,
the rules of the scheme shall have effect as if they provided that his relevant annual remuneration must not exceed his highest average annual remuneration for any period of three or more years ending within the period of ten years which ends with the date on which his service ends.
(4)In the case of an employee within paragraph (b) of sub-paragraph (3) above who retires before 6th April 1991, the rules of the scheme shall have effect as if they provided that his relevant annual remuneration must not exceed the higher of—
(a)the average annual remuneration referred to in that sub-paragraph, and
(b)his remuneration (within the meaning given by section 612(1)) assessable to income tax under Schedule E for the year of assessment 1986-87.
(5)For the purposes of this paragraph a person is a controlling director of a company if—
(a)he is a director (as defined in section 612), and
(b)he is within paragraph (b) of section 417(5),
in relation to the company.
Lump sumsU.K.
6(1)This paragraph applies where an employee becomes a member of the scheme on or after 17th March 1987.
(2)If the rules of the scheme allow the employee to obtain, (by commutation of his pension or otherwise), a lump sum or sums calculated by reference to his relevant annual remuneration, they shall have effect as if they included a rule that in calculating a lump sum any excess of that remuneration over the permitted maximum should be disregarded.
Additional voluntary contributionsU.K.
7(1)This paragraph applies where—
(a)the rules of the scheme make provision for the payment by employees of voluntary contributions, and
(b)on or after 8th April 1987 an employee enters into arrangements to pay such contributions.
(2)Notwithstanding anything in the rules of the scheme, they shall have effect as if they did not allow the payment to the employee of a lump sum in commutation of a pension if or to the extent that the pension is secured by the voluntary contributions.
8(1)This paragraph applies where an employee who is a member of the scheme (“the main scheme”)is also a member of an approved scheme (“the voluntary scheme”)which provides additional benefits to supplement those provided by the main scheme and to which no contributions are made by any employer of his.
(2)Any rules of the main scheme imposing a limit on the amount of a benefit provided for the employee shall have effect (notwithstanding anything in them to the contrary)as if they provided for the limit to be reduced by the amount of any like benefit provided for the employee by the voluntary schemeF3497.
SupplementaryU.K.
9In this Schedule “relevant annual remuneration” means final remuneration or, if the scheme provides for benefits to be calculated by reference to some other annual remuneration, that other annual remuneration.
F3498F3498[F3499SCHEDULE 23ZA]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3498Sch. 23ZA repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
F3499Sch. 23ZA inserted (28.7.2000) by Finance Act 2000 (c. 17), s. 61, Sch. 13 para. 27 (with Sch. 13 paras. 28, 29)
F3500F3500 [F3501Schedule 23A]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3500Sch. 23A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 145, Sch. 3 Pt. 1 (with Sch. 2)
F3501Sch. 23A inserted by Finance Act 1991 (c. 31, SIF 63:1), s. 58, Sch. 13 para. 1 (with effect as mentioned in s. 58(3) in relation to payments made on or after such day as may be specified: 26.2.1992 specified for certain purposes by S.I. 1992/173, reg.2; 30.6.1992 specified for certain purposes by S.I. 1992/1346, regs.2, 3, 4; 21.4.1993 specified for certain purposes by S.I. 1993/933, regs.2, 3(b), 4)
Section 747(6).
SCHEDULE 24U.K.M295ASSUMPTIONS FOR CALCULATING CHARGEABLE PROFITS, CREDITABLE TAX AND CORRESPONDING UNITED KINGDOM TAX OF FOREIGN COMPANIES
Modifications etc. (not altering text)
C199Sch. 24 modified (28.7.2000) by Finance Act 2000 (c. 17), Sch. 22 para. 54(2)-(5)
Marginal Citations
M295Source-1984 Sch. 16, 1985 Sch. 14 16
GeneralU.K.
1(1)The company shall be assumed to be resident in the United Kingdom.U.K.
(2)Nothing in sub-paragraph (1) above requires it to be assumed that there is any change in the place or places at which the company carries on its activities.
(3)For the avoidance of doubt, it is hereby declared that, if any sums forming part of the company’s profits for an accounting period have been received by the company without any deduction of or charge to tax [F3615and have been so received by virtue of [F3616section 1279 of CTA 2009]] the effect of the assumption in sub-paragraph (1) above is that those sums are to be brought within the charge to tax for the purposes of calculating the company’s chargeable profits or corresponding United Kingdom tax.
[F3617(3A)In any case where—
(a)it is at any time necessary for any purpose of Chapter IV of Part XVII to determine [F3618in the case of any person] the chargeable profits of the company for an accounting period, and
(b)at that time—
[F3619(i)it has not been established in the case of that person that that or any earlier accounting period of the company is an accounting period in respect of which an apportionment under section 747(3) falls to be made, F3620. . . ]
(ii)F3620. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F3621in determining the chargeable profits of the company for the accounting period mentioned in paragraph (a) above, it shall be assumed, for the purposes of those provisions of paragraphs 2 and 10 below which refer to the first accounting period in respect of which an apportionment under section 747(3) falls to be made F3622. . . , that that period (but not any earlier period) is an accounting period in respect of which such an apportionment falls to be made F3622. . . .]]
(4)In any case where—
(a)it is at any time necessary for any purpose of Chapter IV of Part XVII to determine [F3623in the case of any person] the chargeable profits of the company for an accounting period, and
[F3624(b)at that time it has not been established in the case of that person that that or any earlier accounting period of the company is an accounting period in respect of which an apportionment under section 747(3) falls to be made,]
[F3625in determining the chargeable profits of the company for the accounting period mentioned in paragraph (a) above, it shall be assumed, for the purposes of those provisions of paragraph 9 below which refer to the first accounting period in respect of which an apportionment under section 747(3) falls to be made, that such an apportionment falls to be made in respect of that period (but not in respect of any earlier period).]
(5)Nothing in this Schedule affects any liability for, or the computation of, corporation tax in respect of a trade which is carried on by a company resident outside the United Kingdom through a [F3626permanent establishment] in the United Kingdom.
[F3627(6)F3628. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3615Words in Sch. 24 para. 1(3) substituted (with effect in accordance with s. 154(9) of the amending Act) by Finance Act 1996 (c. 8), Sch. 28 para. 6
F3616Words in Sch. 24 para. 1(3) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 286(2) (with Sch. 2 Pts. 1, 2)
F3617Sch. 24 para. 1(3A) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(2)
F3618Words in Sch. 24A para. 1(3A)(a) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 17(3); S.I. 1998/3173, art. 2
F3619Sch. 24 para. 1(3A)(b)(i) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 17(4)(a); S.I. 1998/3173, art. 2
F3620Sch. 24 para. 1(3A)(b)(ii) and preceding word omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(a) (with Sch. 16 paras. 7, 8)
F3621Words in Sch. 24 para. 1(3A) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 17(5); S.I. 1998/3173, art. 2
F3622Words in Sch. 24 para. 1(3A)(b) omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(a) (with Sch. 16 paras. 7, 8)
F3623Words in Sch. 24 para. 1(4)(a) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 17(7); S.I. 1998/3173, art. 2
F3624Sch. 24 para. 1(4)(b) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 17(8); S.I. 1998/3173, art. 2
F3625Words in Sch. 24 para. 1(4) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 17(9); S.I. 1998/3173, art. 2
F3626Words in Sch. 24 para. 1(5) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
F3627Sch. 24 para. 1(6) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(3)
F3628Sch. 24 para. 1(6) omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(b) (with Sch. 16 paras. 7, 8)
2(1)The company shall be assumed to have become resident in the United Kingdom (and, accordingly, within the charge to corporation tax) at the beginning of the first accounting period—U.K.
[F3629(a)in respect of which [F3630an apportionment under section 747(3) falls to be made], F3631. . .
(b)F3631. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
and] that United Kingdom residence shall be assumed to continue throughout subsequent accounting periods of the company (whether or not [F3632an apportionment falls to be made] in respect of all or any of them) until the company ceases to be controlled by persons resident in the United Kingdom.
(2)Except in so far as the following provisions of this Schedule otherwise provide, for the purposes of calculating a company’s chargeable profits or corresponding United Kingdom tax for any accounting period which is not the first such period referred to in sub-paragraph (1) above (and, in particular, for the purpose of applying any relief which is relevant to two or more accounting periods), it shall be assumed that a calculation of chargeable profits or, as the case may be, corresponding United Kingdom tax has been made for every previous accounting period throughout which the company was, by virtue of sub-paragraph (1) above, assumed to have been resident in the United Kingdom.
Textual Amendments
F3629Words in Sch. 24 para. 2(1) substituted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(4)
F3630Words in Sch. 24 para. 2(1)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 18(a); S.I. 1998/3173, art. 2
F3631Sch. 24 para. 2(1)(b) and preceding word omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(c) (with Sch. 16 paras. 7, 8)
F3632Words in Sch. 24 para. 2(1) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 18(b); S.I. 1998/3173, art. 2
3U.K.The company shall be assumed not to be a close company.
4(1)Subject to sub-paragraph (2) below, where any relief under the Corporation Tax Acts is dependent upon the making of a claim or election, the company shall be assumed to have made that claim or election which would give the maximum amount of relief and to have made that claim or election within any time limit applicable to it [F3633, except that the company shall be assumed not to have made an election under section 18A of CTA 2009.]U.K.
[F3634(1A)Sub-paragraph (2) below applies to any accounting period of the company—
(a)in respect of which [F3635an apportionment under section 747(3) falls to be made]; F3636. . .
(b)F3636. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(2)[F3637Where this sub-paragraph applies to an accounting period of the company, then] if, by notice [F3638given to an officer of the Board] at any time not later than the expiry of [F3639the period of twenty months following the end of the accounting period] or within such longer period as the Board may in any particular case allow, the United Kingdom resident company which has or, as the case may be, any two or more United Kingdom resident companies which together have, a majority interest in the company so request, the company shall be assumed—
(a)not to have made any claim or election specified in the notice; or
(b)to have made a claim or election so specified, being different from one assumed by sub-paragraph (1) above but being one which (subject to compliance with any time limit) could have been made in the case of a company within the charge to corporation tax; or
(c)to have disclaimed or required the postponement, in whole or in part, of an allowance if (subject to compliance with any time limit) a company within the charge to corporation tax could have disclaimed the allowance or, as the case may be, required such a postponement.
[F3640(2A)F3641. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F3642(2B)For the purposes of sub-paragraph (1) an election under section 9A of CTA 2010 (designated currency of a UK resident investment company) is not to be regarded as an election upon which relief under the Corporation Tax Acts is dependent, and sub-paragraph (2)(b) does not apply in relation to such an election.
(2C)But if, by notice given to an officer of the Board, the United Kingdom resident company which has or, as the case may be, any two or more United Kingdom resident companies which together have, a majority interest in the company so request, the company shall be assumed (subject to section 9A(2) of CTA 2010) to have made an election under section 9A of that Act in the form specified in the notice (and accordingly that section and section 9B of that Act apply to determine the effect (if any) of that election).]
(3)For the purposes of this paragraph, a United Kingdom resident company has, or two or more United Kingdom resident companies together have, a majority interest in the company if on the apportionment of the company’s chargeable profits for the relevant accounting period under section 747(3) more than half of the amount of those profits—
(a)which are apportioned to all United Kingdom resident companies, and
(b)which give rise to [F3643any liability] on any such companies under subsection (4)(a) of that section,
are apportioned to the United Kingdom resident company or companies concerned.
[F3644(3A)F3645. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(4)In sub-paragraph (3) above “the relevant accounting period” means the accounting period or, as the case may be, the first accounting period in which the relief in question is or would be available in accordance with sub-paragraph (1) above.
Textual Amendments
F3633Words in Sch. 24 para. 4(1) inserted (19.7.2011) by Finance Act 2011 (c. 11), Sch. 13 paras. 12, 31
F3634Sch. 24 para. 4(1A) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(5)
F3635Words in Sch. 24 para. 4(1A)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 19(2); S.I. 1998/3173, art. 2
F3636Sch. 24 para. 4(1A)(b) and preceding word omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(d) (with Sch. 16 paras. 7, 8)
F3637Words in Sch. 24 para. 4(2) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(6)(a)
F3638Words in Sch. 24 para. 4(2) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 19(3)(a); S.I. 1998/3173, art. 2
F3639Words in Sch. 24 para. 4(2) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 19(3)(b); S.I. 1998/3173, art. 2
F3640Sch. 24 para. 4(2A) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(7)
F3641Sch. 24 para. 4(2A) repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act by Finance Act 1998 (c. 36), Sch. 17 para. 19(4), Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
F3642Sch. 24 para. 4(2B)(2C) inserted (with effect in accordance with Sch. 7 para. 8 of the amending Act) by Finance Act 2011 (c. 11), Sch. 7 para. 5
F3643Words in Sch. 24 para. 4(3)(b) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 19(5); S.I. 1998/3173, art. 2
F3644Sch. 24 para. 4(3A) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(8)
F3645Sch. 24 para. 4(3A) omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(e) (with Sch. 16 paras. 7, 8)
Modifications etc. (not altering text)
C200Sch. 24 para. 4(1) excluded (with effect in accordance with Sch. 29 Pt. 14 of the affecting Act) by Finance Act 2002 (c. 23), Sch. 29 para. 116(3)
C201Sch. 24 para. 4(1) restricted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), s. 870(4)(5) (with Sch. 2 Pts. 1, 2)
C202Sch. 24 para. 4(2) modified (29.5.2001 with effect in accordance with reg. 1 of the modifying S.I.) by The General Insurance Reserves (Tax) Regulations 2001 (S.I. 2001/1757), reg. 8(3)
C203Sch. 24 para. 4(3)(4) applied (with modifications) (23.3.1995) by The Exchange Gains and Losses (Alternative Method of Calculation of Gain or Loss) Regulations 1994 (S.I. 1994/3227), regs. 1(2), 6
[F36464AU.K.F3647. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3646Sch. 24 para. 4A inserted (27.7.1993 with effect as mentioned in s. 96(2) of the amending act in relation to any accounting period on or after such day as may be appointed under s. 165(7)(b) of the amending Act) by 1993 c. 34, ss. 96(1)(2), 165(7)(b)
F3647Sch. 24 para. 4A deemed never to have been inserted, by virtue of Finance Act 1995 (c. 4), Sch. 25 para. 6(3), Sch. 29 Pt. 8(18), Note
Group relief etc.U.K.
5[F3648(1)]The company shall be assumed to be neither a member of a group of companies nor a member of a consortium for the purposes of any provision of the Tax Acts.U.K.
[F3649(2)Where, under [F3650Part 5 of CTA 2010], any relief is in fact surrendered by the company and allowed to another company by way of group relief, it shall be assumed that the chargeable profits of the company, apart from this paragraph, are to be increased by an amount of additional profits equal to the amount of the relief so surrendered and allowed.]
Textual Amendments
F3648Sch. 24 para. 5 renumbered as para. 5(1) (with effect in accordance with Sch. 27 para. 12(1) of the amending Act) by virtue of Finance Act 2000 (c. 17), Sch. 27 para. 10
F3649Sch. 24 para. 5(2) inserted (with effect in accordance with Sch. 27 para. 12(1) of the amending Act) by Finance Act 2000 (c. 17), Sch. 27 para. 10
F3650Words in Sch. 24 para. 5(2) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 146(2) (with Sch. 2)
Modifications etc. (not altering text)
C204Sch. 24 para. 5(1) excluded by Corporation Tax Act 2010 (c. 4), s. 938M(1) (as inserted (19.7.2011) by Finance Act 2011 (c. 11), Sch. 5 para. 2)
6U.K.F3651. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3651Sch. 24 para. 6 repealed (with application in accordance with Sch. 33 Pt. 2(10) Note of the repealing Act) by Finance Act 2001 (c. 9), Sch. 33 Pt. 2(10)
7U.K.F3652. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3652Sch. 24 para. 7 repealed (with effect in accordance with Sch. 3 para. 43(4) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 43(3), Sch. 27 Pt. 3(2), Note
Company reconstructionsU.K.
8U.K.Without prejudice to the operation of [F3653Chapter 1 of Part 22 of CTA 2010] in a case where the company is the predecessor, within the meaning of [F3654that Chapter], and a company resident in the United Kingdom is the successor, within the meaning of [F3654that Chapter]—
(a)the assumption that the company is resident in the United Kingdom shall not be regarded as requiring it also to be assumed that the company is within the charge to tax in respect of a trade for the purposes of [F3654that Chapter], and
(b)except in so far as the company is actually within that charge (by carrying on the trade through a [F3655permanent establishment] in the United Kingdom), it shall accordingly be assumed that the company can never be the successor, within the meaning of [F3654that Chapter], to another company (whether resident in the United Kingdom or not).
Textual Amendments
F3653Words in Sch. 24 para. 8 substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 146(3)(a) (with Sch. 2)
F3654Words in Sch. 24 para. 8 substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 146(3)(b) (with Sch. 2)
F3655Words in Sch. 24 para. 8(b) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
Losses in pre-direction accounting periodsU.K.
9(1)F3656. . . This paragraph applies in any case where the company incurred a loss in a trade in an accounting period—U.K.
(a)which precedes the first accounting period in respect of which [F3657an apportionment under section 747(3) falls to be made] (“the starting period”); and
(b)which ended less than six years before the beginning of the starting period; and
(c)in which the company was not resident [F3658F3659. . . ] in the United Kingdom;
and in this paragraph any such accounting period is referred to as a “ [F3660pre-apportionment] period”.
(2)F3661. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(3)If a claim is made for the purpose by the United Kingdom resident company or companies referred to in paragraph 4(2) above, the chargeable profits (if any) of the company for accounting periods beginning with that [F3660pre-apportionment] period which is specified in the claim and in which a loss is incurred as mentioned in sub-paragraph (1) above shall be determined (in accordance with the provisions of this Schedule other than this paragraph) on the assumption that that [F3660pre-apportionment] period was the first accounting period in respect of which [F3662an apportionment under section 747(3) fell to be made].
[F3663(4)A claim under sub-paragraph (3) above shall be made by notice given to an officer of the Board within the period of twenty months following the end of the starting period or within such longer period as the Board may in any particular case allow.]
(5)F3661. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(6)F3661. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F3664(7)Nothing in—
(a)paragraph 10 of Schedule 18 to the Finance Act 1998 (claims or elections in company tax returns), or
(b)Schedule 1A to the Management Act (claims or elections not included in returns),
shall apply, whether by virtue of section 754 or otherwise, to a claim under sub-paragraph (3) above.]
Textual Amendments
F3656Words in Sch. 24 para. 9(1) repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(3)(a), Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
F3657Words in Sch. 24 para. 9(1)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(3)(b); S.I. 1998/3173, art. 2
F3658Words in Sch. 24 para. 9(1)(c) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(9)
F3659Words in Sch. 24 para. 9(1)(c) omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(f) (with Sch. 16 paras. 7, 8)
F3660Words in Sch. 24 para. 9(1)(3) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(2); S.I. 1998/3173, art. 2
F3661Sch. 24 para. 9(2)(5)(6) repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(4)(7)(8), Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
F3662Words in Sch. 24 para. 9(3) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(5); S.I. 1998/3173, art. 2
F3663Sch. 24 para. 9(4) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(6); S.I. 1998/3173, art. 2
F3664Sch. 24 para. 9(7) added (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 20(9); S.I. 1998/3173, art. 2
Capital allowances[F3665 and expenditure on car hire]U.K.
Textual Amendments
F3665Words in cross-heading relating to Sch. 24 para. 11A inserted (with effect in accordance with s. 579 of the amending Act) by virtue of Capital Allowances Act 2001 (c. 2), Sch. 2 para. 66(3)(a)
10(1)[F3666Subject to paragraph 12 below,] if, in an accounting period falling before the beginning of the first accounting period—U.K.
[F3667(a)in respect of which [F3668an apportionment under section 747(3) falls to be made], F3669. . .
(b)F3669. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
the] company incurred any capital expenditure on the provision of [F3670plant or machinery for the purposes of its trade, that plant or machinery shall be assumed, for the purposes of Part 2 of the Capital Allowances Act], to have been provided for purposes wholly other than those of the trade and not to have been brought into use for the purposes of that trade until the beginning of that first accounting period, and [F3671section 13 of that Act (use for qualifying activity of plant or machinery provided for other purposes)] shall apply accordingly.
(2)This paragraph shall be construed as one with [F3672Part 2 of the Capital Allowances Act].
Textual Amendments
F3666Words in Sch. 24 para. 10(1) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 21(a); S.I. 1998/3173, art. 2
F3667Words in Sch. 24 para. 10(1) substituted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 3(10)
F3668Words in Sch. 24 para. 10(1)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 21(b); S.I. 1998/3173, art. 2
F3669Sch. 24 para. 10(1)(b) and preceding word omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 2(6)(g) (with Sch. 16 paras. 7, 8)
F3670Words in Sch. 24 para. 10(1) substituted (with effect in accordance with s. 579 of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 66(1)(a)
F3671Words in Sch. 24 para. 10(1) substituted (with effect in accordance with s. 579 of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 66(1)(b)
F3672Words in Sch. 24 para. 10(2) substituted (with effect in accordance with s. 579 of the amending Act) by Capital Allowances Act 2001 (c. 2), Sch. 2 para. 66(2)
11U.K.F3673. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3673Sch. 24 para. 11 repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 22, Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
[F367411AU.K.F3675. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3674Sch. 24 para. 11A inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 25 para. 6(4)
F3675Sch. 24 para. 11A repealed (with effect in accordance with Sch. 4 para. 24(2) of the repealing Act) by Finance Act 2005 (c. 7), Sch. 11 Pt. 2(6), Note
Unremittable overseas incomeU.K.
12U.K.For the purposes of the application of [F3676Part 18 of CTA 2009] to the company’s income it shall be assumed—
(a)that any reference in [F3677section 1274(3) or (4) of that Act] to the United Kingdom is a reference to both the United Kingdom and the territory in which the company is in fact resident; and
(b)that [F3678a claim under section 1275 of that Act (claim for relief for unremittable income) may be made] on behalf of the company by the United Kingdom resident company or companies referred to in paragraph 4(2) above.
Textual Amendments
F3676Words in Sch. 24 para. 12 substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 286(3)(a) (with Sch. 2 Pts. 1, 2)
F3677Words in Sch. 24 para. 12(a) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 286(3)(b) (with Sch. 2 Pts. 1, 2)
F3678Words in Sch. 24 para. 12(b) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 286(3)(c) (with Sch. 2 Pts. 1, 2)
[F3679 Exchange gains and lossesU.K.
Textual Amendments
F3679Sch. 24 paras. 13-19 and cross-heading inserted (1.5.1995) by Finance Act 1995 (c. 4), Sch. 25 para. 6(5)
13U.K.F3680. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3680Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
14U.K.F3681. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3681Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
15U.K.F3682. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3682Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
16U.K.F3683. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3683Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
17U.K.F3684. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3684Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
18U.K.F3685. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3685Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
19U.K.F3686. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3686Sch. 24 paras. 13-19 repealed (with effect in accordance with s. 79(3) of the repealing Act) by Finance Act 2002 (c. 23), Sch. 40 Pt. 3(10), Note
[F3687 Transfer pricingU.K.
Textual Amendments
F3687Sch. 24 para. 20 and cross-heading inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 24; S.I. 1998/3173, art. 2
20U.K.F3688. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3688Sch. 24 para. 20 repealed (with effect in accordance with s. 37 of the repealing Act) by Finance Act 2004 (c. 12), Sch. 5 para. 4, Sch. 42 Pt. 2(1), Note
Section 748.
SCHEDULE 25U.K.[F3689Cases where section 747(3) does not apply]
Textual Amendments
F3689Sch. 25 heading substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 25; S.I. 1998/3173, art. 2
F3690F3690PART IU.K. ACCEPTABLE DISTRIBUTION POLICY
Textual Amendments
F3690Sch. 25 Pt. 1 (paras. 1-4A) omitted (with effect in accordance with Sch. 16 para. 6 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 1(3) (with Sch. 16 paras. 7-9) (subject, as saved, to amendment by Corporation Tax Act 2010 (c. 4), s. 1184(1), Sch. 1 para. 147(2) (with Sch. 2))
PART IIU.K. EXEMPT ACTIVITIES
Modifications etc. (not altering text)
C205Sch. 25 Pt. 2 modified (21.7.2009) by Finance Act 2009 (c. 10), Sch. 16 para. 17 (with Sch. 16 paras. 13-16, 18-20)
5(1)The provisions of this Part of this Schedule have effect for the purposes of paragraph (b) of subsection (1) of section 748.U.K.
[F3729(1A)Except as provided in paragraph 8 below, the provisions of this Part of this Schedule apply in relation to a company which is resident in an EEA territory in the same way as they apply in relation to a company which is resident elsewhere.]
(2)In the case of a controlled foreign company—
(a)which is, by virtue of section [F3730749(5)], presumed to be resident in a territory in which it is subject to a lower level of taxation, and
(b)the business affairs of which are, throughout the accounting period in question, effectively managed in a territory outside the United Kingdom other than one in which companies are liable to tax by reason of domicile, residence or place of management,
references in the following provisions of this Part of this Schedule to the territory in which that company is resident shall be construed as references to the territory falling within paragraph (b) above, or, if there is more than one, to that one of them which may be notified to the Board by the United Kingdom resident company or companies referred to in paragraph 4(2) of Schedule 24.
[F3731(3)In the case of a controlled foreign company—
(a)which is, by virtue of section 749(5), presumed to be resident in a territory in which it is subject to a lower level of taxation,
(b)the business affairs of which are, throughout the accounting period in question, effectively managed in a special administrative region, and
(c)which is liable to tax for that period in that region,
references in the following provisions of this Part of this Schedule to the territory in which that company is resident shall be construed as references to that region.
(4)In sub-paragraph (3) above “special administrative region” means the Hong Kong or the Macao Special Administrative Region of the People’s Republic of China.
(5)Where sub-paragraph (3) above applies, it applies in place of sub-paragraph (2).]
Textual Amendments
F3729Sch. 25 para. 5(1A) inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 7(2)
F3730Words in Sch. 25 para. 5(2)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 29; S.I. 1998/3173, art. 2
F3731Sch. 25 para. 5(3)-(5) inserted (with effect in accordance with s. 201(2) of the amending Act) by Finance Act 2003 (c. 14), s. 201(1)
6(1)Throughout an accounting period a controlled foreign company is engaged in exempt activities if, and only if, each of the following conditions is fulfilled—U.K.
(a)that, throughout that accounting period, the company has a business establishment in the territory in which it is resident; and
(b)that, throughout that accounting period, its business affairs in that territory are effectively managed there; and
(c)that any of sub-paragraphs [F3732(2) or (3)] below applies to the company.
(2)This sub-paragraph applies to a company if—
(a)at no time during the accounting period in question does the main business of the company consist of either—
(i)investment business, or
(ii)dealing in goods for delivery to or from the United Kingdom or to or from connected or associated persons; and
(b)in the case of a company which is mainly engaged in wholesale, distributive [F3733financial or service] business in that accounting period, less than 50 per cent. of its gross trading receipts from that business is derived directly or indirectly from [F3734persons falling within sub-paragraph (2A) below.]
[F3735(2A)Those persons are—
(a)persons who are connected or associated with the company;
(b)persons who have a 25 per cent assessable interest in the company in the case of the accounting period in question; F3736. . .
(c)if the company is a controlled foreign company in that accounting period by virtue of subsection (1A) of section 747, persons who are connected or associated with either or both of the two persons mentioned in that subsection [F3737;
(d)persons not falling within paragraphs (a) to (c) above which are companies resident in the United Kingdom;
(e)persons not falling within paragraphs (a) to (c) above which are companies not resident in the United Kingdom which carry on business through a [F3738permanent establishment] in the United Kingdom;
(f)persons not falling within paragraphs (a) to (c) above who are individuals habitually resident in the United Kingdom;
but where the company is a controlled foreign company falling within sub-paragraph (2B) below, paragraphs (d) to (f) above shall be disregarded.]]
[F3739(2B)A controlled foreign company falls within this sub-paragraph if either—
(a)its main business is the effecting or carrying out of contracts of long-term insurance, other than protection business; or
(b)it is a member of an insurance group and its main business is insuring or reinsuring large risks.
Paragraph 11A below has effect for the interpretation of this sub-paragraph.
(2C)For the purposes of sub-paragraph (2)(b) above, a company’s gross trading receipts from a business shall be regarded as directly or indirectly derived from a person falling within sub-paragraph (2A)(e) above only to the extent that they are derived directly or indirectly from contracts or other arrangements relating to that person’s [F3738permanent establishment] in the United Kingdom.]
(3)This sub-paragraph applies to a company which is a holding company if at least 90 per cent. of its gross income during the accounting period in question [F3740is received by it in the territory in which it is resident and] is derived directly from companies which it controls and which, throughout that period—
(a)are resident in the territory in which the holding company is resident; and
(b)are not themselves holding companies [F3741F3742. . . ], but otherwise are, in terms of this Schedule, engaged in exempt activities [F3743or are, in terms of sub-paragraph (5A) below, exempt trading companies] ;
and a holding company to which this sub-paragraph applies is in this Part of this Schedule referred to as a “local holding company”.
(4)F3744. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F3745(4ZA)F3744. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F3746(4A)F3744. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
[F3747(4AA)F3744. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
(4B)F3744. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F3748(4BB)F3744. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F3749(4C)For the purposes of sub-paragraph [F3750(2A)(b)] above, a person has a 25 per cent. assessable interest in a controlled foreign company in the case of an accounting period of the company if, on an apportionment of the chargeable profits and creditable tax (if any) of the company for that accounting period under section 747(3), at least 25 per cent. of the controlled foreign company’s chargeable profits for the accounting period would be apportioned to that person.]
(5)Any reference in [F3751sub-paragraph (3)] above to a company which a holding company [F3752F3753. . . ] controls includes a reference to a trading company [F3754to which sub-paragraph (5ZA) or (5ZB) below applies.
(5ZA)This sub-paragraph applies to a trading company] in which the holding company [F3752F3755. . . ] holds the maximum amount of ordinary share capital which is permitted under the law of the territory—
(a)in which the trading company is resident; and
(b)from whose laws the trading company derives its status as a company.
[F3756(5ZB)This sub-paragraph applies to a trading company if—
(a)it is a controlled foreign company by virtue of subsection (1A) of section 747; and
(b)the person who satisfies the requirement in paragraph (b) of that subsection in relation to the company also controls the holding company F3757. . . .]
[F3758(5A)For the purposes of [F3759sub-paragraph (3)] above, a company is an exempt trading company throughout any period if—
(a)it is a trading company throughout each of its accounting periods which falls wholly or partly within that period; and
(b)each of those accounting periods is one as regards which—
(i)the condition in section 747(1)(c) is not satisfied; or
(ii)the conditions in section 748(1)(e) are satisfied; or
(iii)the conditions in section 748(3)(a) and (b) are satisfied.]
[F3760(5B)F3761. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
[F3762(5C)For the purposes of this paragraph, the gross income of a holding company F3763. . . during an accounting period includes—
(a)any income which accrues during that period to the trustees of a settlement in relation to which the company is a settlor or a beneficiary, and
(b)any income which accrues during that period to a partnership of which the company is a partner, apportioned between the company and the other partners on a just and reasonable basis.
(5D)Where there is more than one settlor or beneficiary in relation to the settlement mentioned in sub-paragraph (5C)(a), the income is to be apportioned between the company and the other settlors or beneficiaries on a just and reasonable basis.
(5E)In sub-paragraph (5C)(b) “partnership” includes an entity established under the law of a country or territory outside the United Kingdom of a similar character to a partnership; and “partner” is to be read accordingly.]
(6)The following provisions of this Part of this Schedule have effect in relation to [F3764this paragraph].
Textual Amendments
F3732Words in Sch. 25 para. 6(1)(c) substituted (with effect in accordance with Sch. 16 para. 12 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(a) (with Sch. 16 paras. 13-20)
F3733Words in Sch. 25 para. 6(2)(b) substituted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 5(2)(a)
F3734Words in Sch. 25 para. 6(2)(b) substituted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 5(2)(b)
F3735Sch. 25 para. 6(2A) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 5(3)
F3736Word in Sch. 25 para. 6(2A) repealed (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the repealing Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 2(3), Sch. 43 Pt. 5(2)
F3737Sch. 25 para. 6(2A)(d)-(f) and words inserted (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 2(3)
F3738Words in Sch. 25 para. 6(2A)(e)(2C) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
F3739Sch. 25 para. 6(2B)(2C) inserted (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 2(4)
F3740Words in Sch. 25 para. 6(3) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 6(2)
F3741Words in Sch. 25 para. 6(3)(b) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 30(4)(a); S.I. 1998/3173, art. 2
F3742Words in Sch. 25 para. 6(3)(b) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(b) (with Sch. 16 paras. 13-20)
F3743Words in Sch. 25 para. 6(3)(b) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 30(4)(b); S.I. 1998/3173, art. 2
F3744Sch. 25 para. 6(4)-(4BB) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(c) (with Sch. 16 paras. 13-20)
F3745Sch. 25 para. 6(4ZA) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 7(3)
F3746Sch. 25 para. 6(4A)(4B) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 30(6); S.I. 1998/3173, art. 2
F3747Sch. 25 para. 6(4AA) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 7(5)
F3748Sch. 25 para. 6(4BB) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 7(7)
F3749Sch. 25 para. 6(4C) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 30(7); S.I. 1998/3173, art. 2
F3750Words in Sch. 25 para. 6(4C) substituted (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 2(5)
F3751Words in Sch. 25 para. 6(5) substituted (with effect in accordance with Sch. 16 para. 12 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(d)(i) (with Sch. 16 paras. 13-20)
F3752Words in Sch. 25 para. 6(5) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 30(8)(b); S.I. 1998/3173, art. 2
F3753Words in Sch. 25 para. 6(5) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(d)(ii) (with Sch. 16 paras. 13-20)
F3754Words in Sch. 25 para. 6 inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 7(8)
F3755Words in Sch. 25 para. 6(5ZA) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(e) (with Sch. 16 paras. 13-20)
F3756Sch. 25 para. 6(5ZB) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 7(9)
F3757Words in Sch. 25 para. 6(5ZB)(b) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(f) (with Sch. 16 paras. 13-20)
F3758Sch. 25 para. 6(5A) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 30(9); S.I. 1998/3173, art. 2
F3759Words in Sch. 25 para. 6(5A) substituted (with effect in accordance with Sch. 16 para. 12 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(g) (with Sch. 16 paras. 13-20)
F3760Sch. 25 para. 6(5B) inserted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 7(10)
F3761Sch. 25 para. 6(5B) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(h) (with Sch. 16 paras. 13-20)
F3762Sch. 25 para. 6(5C)-(5E) inserted (with effect in accordance with s. 64(6)(9) of the amending Act) by Finance Act 2008 (c. 9), s. 64(5)
F3763Words in Sch. 25 para. 6(5C) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(i) (with Sch. 16 paras. 13-20)
F3764Words in Sch. 25 para. 6(6) substituted (with effect in accordance with Sch. 16 para. 12 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 10(2)(j) (with Sch. 16 paras. 13-20)
7(1)For the purposes of paragraph 6(1)(a) above, a “business establishment”, in relation to a controlled foreign company, means premises—U.K.
(a)which are, or are intended to be, occupied and used with a reasonable degree of permanence; and
(b)from which the company’s business in the territory in which it is resident is wholly or mainly carried on.
(2)For the purposes of sub-paragraph (1) above the following shall be regarded as premises—
(a)an office, shop, factory or other building or part of a building; or
(b)a mine, an oil or gas well, a quarry or any other place of extraction of natural resources; or
(c)a building site or the site of a construction or installation project;
but such a site as is referred to in paragraph (c) above shall not be regarded as premises unless the building work or the project, as the case may be, has a duration of at least twelve months.
8(1)Subject to sub-paragraph (4) below, the condition in paragraph 6(1)(b) above shall not be regarded as fulfilled [F3765in relation to a company which is not resident in an EEA territory] unless—U.K.
(a)the number of persons employed by the company in the territory in which it is resident is adequate to deal with the volume of the company’s business; and
(b)any services provided by the company for persons resident outside that territory are not in fact performed in the United Kingdom.
(2)For the purposes of sub-paragraph (1)(a) above, persons who are engaged wholly or mainly in the business of the company and whose remuneration is paid by a person connected with, and resident in the same territory as, the company shall be treated as employed by the company.
(3)In the case of a holding company [F3766F3767. . . ], sub-paragraph (2) above shall apply with the omission of the words “wholly or mainly”.
(4)For the purposes of sub-paragraph (1)(b) above, no account shall be taken of services—
(a)provided through a [F3768permanent establishment] of the controlled foreign company if the profits or gains of the business carried on through the [F3768permanent establishment] are within the charge to tax in the United Kingdom; or
(b)provided through any other person whose profits or gains from the provision of the services are within the charge to tax in the United Kingdom and who provides the services for a consideration which is, or which is not dissimilar from what might reasonably be expected to be, determined under a contract entered into at arm’s length; or
(c)which are no more than incidental to services provided outside the United Kingdom.
[F3769(5)The condition in paragraph 6(1)(b) above shall not be regarded as fulfilled in relation to a company which is resident in an EEA territory unless there are sufficient individuals working for the company in the territory who have the competence and authority to undertake all, or substantially all, of the company's business.
(6)For the purposes of sub-paragraph (5) above, individuals are not to be regarded as working for a company in any territory unless—
(a)they are employed by the company in the territory, or
(b)they are otherwise directed by the company to perform duties on its behalf in the territory.]
Textual Amendments
F3765Words in Sch. 25 para. 8(1) inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 7(3)
F3766Words in Sch. 25 para. 8(3) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 31(2); S.I. 1998/3173, art. 2
F3767Words in Sch. 25 para. 8(3) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(3) (with Sch. 16 paras. 13-20)
F3768Words in Sch. 25 para. 8(4)(a) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
F3769Sch. 25 para. 8(5)(6) inserted (with effect in accordance with Sch. 15 para. 10 of the amending Act) by Finance Act 2007 (c. 11), Sch. 15 para. 7(4)
9(1)Subject to sub-paragraph (3) below, for the purposes of paragraph 6(2)(a)(i) above, each of the following activities constitutes investment business—U.K.
(a)the holding of securities, [F3770or intellectual property];
(b)dealing in securities, other than in the capacity of a broker;
(c)the leasing of any description of property or rights; and
(d)the investment in any manner of funds which would otherwise be available, directly or indirectly, for investment by or on behalf of any person (whether resident in the United Kingdom or not) who has, or is connected or associated with a person who has, control, either alone or together with other persons, of the controlled foreign company in question.
[F3771[F3772(1A)In sub-paragraph (1)(a) above “intellectual property” includes (in particular)—
(a)any industrial, commercial or scientific information, knowledge or expertise;
(b)any patent, trade mark, registered design, copyright or design right;
(c)any licence or other right in respect of intellectual property;
(d)any rights under the law of a country outside the United Kingdom which correspond or are similar to those falling within paragraph (b) or (c) above.]]
(2)In sub-paragraph (1)(b) above “broker” includes any person offering to sell securities to, or purchase securities from, members of the public generally.
(3)For the purposes of paragraph 6(2) above, in the case of a company which is mainly engaged in [F3773business] falling within paragraph 11(1)(c) below, nothing in sub-paragraph (1) above shall require the main business of the company to be regarded as investment business.
Textual Amendments
F3770Words in Sch. 25 para. 9(1)(a) substituted (1.8.1989) by Copyright, Designs and Patents Act 1988 (c. 48), s. 305(3), Sch. 7 para. 36(9); S.I. 1989/816, art. 2
F3771Sch. 25 para. 9(1A) inserted (1.8.1989) by Copyright, Designs and Patents Act 1988 (c. 48), s. 305(3), Sch. 7 para. 36(9); S.I. 1989/816, art. 2
F3772Sch. 25 para. 9(1A) substituted (with effect in accordance with s. 112(5) of the amending Act) by Finance Act 1998 (c. 36), s. 112(2)
F3773Word in Sch. 25 para. 9(3) substituted (with effect in accordance with s. 112(5) of the amending Act) by Finance Act 1998 (c. 36), s. 112(4)(a)
10U.K.Goods which are actually delivered into the territory in which the controlled foreign company is resident shall not be taken into account for the purposes of paragraph 6(2)(a)(ii) above.
11(1)For the purposes of paragraph 6(2)(b) above, each of the following activities constitutes wholesale, distributive [F3774financial or service] business—U.K.
(a)dealing in any description of goods wholesale rather than retail;
(b)the business of shipping or air transport, that is to say, the business carried on by an owner of ships or the business carried on by an owner of aircraft (“owner” including, for this purpose, any charterer);
[F3775(c)banking, deposit-taking, money-lending or debt-factoring, or any business similar to banking, deposit-taking, money-lending or debt-factoring;]
(d)the administration of trusts;
(e)dealing in securities in the capacity of a broker, as defined in paragraph 9(2) above;
(f)dealing in commodity or financial futures;F3776. . .
[F3777(g)the effecting or carrying out of contracts of insurance; and]
[F3778(h)the provision of services not falling within any of the preceding paragraphs.]
[F3779(1A)For the purposes of sub-paragraph (1)(g) above “contract of insurance” has the meaning given by Article 3(1) of the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001.]
(2)In a case where the gross trading receipts of a company include an amount in respect of the proceeds of sale of any description of property or rights, the cost to the company of the purchase of that property or those rights shall be a deduction in calculating the company’s gross trading receipts for the purposes of paragraph 6(2)(b) above.
(3)In the case of a controlled foreign company engaged in a [F3780business] falling within sub-paragraph (1)(c) above—
[F3781(a)no payment of interest received from a company resident in the United Kingdom which is connected or associated with the controlled foreign company shall be regarded for the purposes of paragraph 6(2)(b) above as a receipt derived directly or indirectly from a person falling within paragraph 6(2A) above, but]
(b)it shall be conclusively presumed that the condition in paragraph 6(2)(b) above is not fulfilled if, at any time during the accounting period in question, the amount by which the aggregate value of the capital interests in the company held directly or indirectly by—
(i)the persons who have control of the company, and
(ii)any person connected or associated with those persons,
exceeds the value of the company’s fixed assets is 15 per cent. or more of the amount by which the company’s outstanding capital exceeds that value [F3782, and
(c)it shall also be conclusively presumed that the condition in paragraph 6(2)(b) is not fulfilled if 10% or more of the company’s gross trading receipts from all businesses carried on by it in the accounting period in question, taken together, are receipts other than interest and are directly or indirectly derived from persons—
(i)which are companies resident in the United Kingdom,
(ii)which are companies not resident in the United Kingdom but which carry on business through a [F3783permanent establishment] in the United Kingdom, or
(iii)who are individuals habitually resident in the United Kingdom,
but for this purpose a company’s gross trading receipts shall be regarded as directly or indirectly derived from a person falling within sub-paragraph (ii) above only to the extent that they are derived directly or indirectly from contracts or other arrangements relating to that person’s [F3783permanent establishment] in the United Kingdom.]
(4)For the purposes of this paragraph, in relation to a controlled foreign company—
(a)“capital interest” means an interest in the issued share capital or reserves of the company or in a loan to or deposit with the company or the liability of a guarantor under a guarantee given to or for the benefit of the company;
(b)except in the case of the liability of a guarantor, the value of a capital interest is its value as shown in the company’s accounts;
(c)in the case of the liability of a guarantor, the value shall be taken to be the market value of the benefit which the controlled foreign company derives from the provision of the guarantee;
(d)the value of the company’s fixed assets means the value, as shown in the company’s accounts, of the plant, premises and trade investments employed in the company’s business; and
(e)“outstanding capital” means the total value of all the capital interests in the company, less the value, as shown in the company’s accounts, of any advances made by the company to persons resident outside the United Kingdom and falling within paragraph (i) or paragraph (ii) of sub-paragraph (3)(b) above.
(5)For the purposes of sub-paragraph (4) above—
(a)“trade investments”, in relation to a controlled foreign company, means securities any profit on the sale of which would not be brought into account as a trading receipt in computing the chargeable profits of an accounting period in which that profit arose; and
(b)the reference in paragraph (e) to advances made to a person by the controlled foreign company includes, in the case of a company which is a person resident outside the United Kingdom and falling within paragraph (i) or paragraph (ii) of sub-paragraph (3)(b) above, any securities of that company which are held by the controlled foreign company but are not trade investments, as defined in paragraph (a) above;
and in this sub-paragraph “securities” includes stocks and shares.
(6)In the application of paragraph 6(2)(b) above in the case of a controlled foreign company engaged in insurance business of any kind—
(a)the reference to gross trading receipts which are derived directly or indirectly from connected or associated persons is a reference to those which, subject to sub-paragraph (7) below, are attributable, directly or indirectly, to liabilities undertaken in relation to any of those persons or their property;
(b)the only receipts to be taken into account are commissions and premiums received under insurance contracts;
(c)so much of any such commission or premium as is returned is not to be taken into account; and
(d)when a liability under an insurance contract is reinsured, in whole or in part, the amount of the premium which is attributable, directly or indirectly, to that liability shall be treated as reduced by so much of the premium under the reinsurance contract as is attributable to that liability.
(7)In determining, in relation to a controlled foreign company to which sub-paragraph (6) above applies, the gross trading receipts referred to in paragraph (a) of that sub-paragraph, there shall be left out of account any receipts under a local reinsurance contract which are attributable to liabilities which—
(a)are undertaken under an insurance contract made in the territory in which the company is resident; and
(b)are not reinsured under any contract other than a local reinsurance contract; and
(c)relate either to persons who are resident in that territory and are neither connected nor associated with the company or to property which is situated there and belongs to persons who are not so connected or associated;
and in paragraph (a) above “insurance contract” does not include a reinsurance contract.
(8)In sub-paragraph (7) above “local reinsurance contract” means a reinsurance contract—
(a)which is made in the territory in which the controlled foreign company is resident; and
(b)the parties to which are companies which are resident in that territory.
(9)For the purposes of sub-paragraphs (7) and (8) above, any question as to the territory in which a company is resident shall be determined in accordance with section 749 and, where appropriate, paragraph 5(2) above; and, for the purpose of the application of those provisions in accordance with this sub-paragraph, the company shall be assumed to be a controlled foreign company.
Textual Amendments
F3774Words in Sch. 25 para. 11(1) substituted (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 8(2)(a)
F3775Sch. 25 para. 11(1)(c) substituted (with effect in accordance with s. 112(5) of the amending Act) by Finance Act 1998 (c. 36), s. 112(3)
F3776Word preceding Sch. 25 para. 11(1)(g) repealed (with effect in accordance with Sch. 31 para. 9(4) of the repealing Act) by Finance Act 2000 (c. 17), Sch. 31 para. 8(2)(b), Sch. 40 Pt. 2(14), Note
F3777Sch. 25 para. 11(1)(g) substituted (1.12.2001 with effect in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2000/3629), art. 51(2)
F3778Sch. 25 para. 11(1)(h) and preceding word added (with effect in accordance with Sch. 31 para. 9(4) of the amending Act) by Finance Act 2000 (c. 17), Sch. 31 para. 8(2)(c)
F3779Sch. 25 para. 11(1A) inserted (1.12.2001 with effect in accordance with art. 1(2)(a) of the amending S.I.) by The Financial Services and Markets Act 2000 (Consequential Amendments) (Taxes) Order 2001 (S.I. 2000/3629), art. 51(3)
F3780Word in s. 11(3) substituted (with effect in accordance with s. 112(5) of the amending Act) by Finance Act 1998 (c. 36), s. 112(4)(b)
F3781Sch. 25 para. 11(3)(a) substituted (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 3(2)
F3782Sch. 25 para. 11(3)(c) and preceding word added (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 3(3)
F3783Words in Sch. 25 para. 11(3)(c) substituted (with effect in accordance with s. 153(4) of the amending Act) by Finance Act 2003 (c. 14), s. 153(1)(a)
[F378411A(1)This paragraph has effect for the interpretation of paragraph 6(2B) above.U.K.
(2)“Contract of long-term insurance” means any contract falling within Part II of Schedule 1 to the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001.
(3)“Protection business” means contracts of long-term insurance where—
(a)either—
(i)the contract has no surrender value; or
(ii)the consideration consists of a single premium and the surrender value does not exceed the amount of that premium; and
(b)the contract makes no provision for its conversion or extension in a manner which would result in its ceasing to fall within paragraph (a) above;
and references to protection business include a reference to reinsurance of protection business.
[F3785(4)“Insurance group” shall be construed in accordance with section 1165(5) of the Companies Act 2006, but does not include such an insurance group if it falls within sub-paragraph (5) below.]
(5)Such an insurance group falls within this sub-paragraph if F3786. . . the parent company is a subsidiary undertaking of a parent company which is neither—
(a)the parent company of an insurance group; nor
(b)a subsidiary undertaking of the parent company of an insurance group.
(6)A controlled foreign company is, in accordance with sub-paragraphs (4) and (5) above, a “member of an insurance group” if (within the meaning of that Part as so read) it is the parent company, or a subsidiary undertaking of the parent company, of an insurance group which is by virtue of sub-paragraph (4) above an insurance group for the purposes of paragraph 6(2B) above.
(7)A company’s main business is “insuring or reinsuring large risks” if (and only if)—
(a)the company’s main business is the effecting or carrying out of contracts of insurance; and
(b)50% or more of its gross trading receipts from that business are derived from insuring or reinsuring large risks.
“Large risks” is defined in paragraph 11B below.
(8)In this paragraph—
“contract of insurance” has the meaning given by article 3(1) of the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001;
“contract of long-term insurance” has the meaning given by sub-paragraph (2) above.
Textual Amendments
F3784Sch. 25 paras. 11A, 11B inserted (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 4
F3785Sch. 25 para. 11A(4) substituted (6.4.2008 with effect in accordance with art. 1(2) of the amending S.I.) by The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2008 (S.I. 2008/954), arts. 1(1), 14(2)(a) (with art. 4)
F3786Words in Sch. 25 para. 11A(5) repealed (6.4.2008 with effect in accordance with art. 1(2) of the repealing S.I.) by The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2008 (S.I. 2008/954), arts. 1(1), 14(2)(b), Sch. (with art. 4)
11B(1)In paragraph 11A above “large risks” means—U.K.
(a)risks falling within classes 4, 5, 6, 7, 11 and 12 of Part I of Schedule 1 to the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001;
(b)risks falling within classes 14 and 15 of that Part which relate to a business carried on by the policy holder;
(c)risks falling within classes 3, 8, 9, 10, 13 and 16 of that Part where the policy holder carries on a business in respect of which the condition specified in sub-paragraph (2) below is satisfied.
(2)The condition referred to in sub-paragraph (1)(c) above is that, in the case of that business of the policy holder, at least two of the three following criteria were exceeded in the most recent financial year beginning on or after 1st January 1999 for which the information is available—
(a)balance sheet total: 6.2 million euros;
(b)net turnover: 12.8 million euros;
(c)number of employees: 250.
(3)For the purposes of sub-paragraph (2) above as it applies where the policy holder is a company, within the meaning of section [F37871] of the Companies Act [F37872006]F3788. . . ,—
(a)“balance sheet total” has the meaning given by [F3789sections 382(5) and 465(5) of the Companies Act 2006];
(b)“net turnover” has the meaning given to “turnover” by [F3790section 474(1) of that Act]; and
(c)“number of employees” has the meaning given by [F3791sections 382(6) and 465(6) of that Act];
and for a financial year which is a company’s financial year but not in fact a year, the net turnover of the company shall be proportionately reduced.
(4)Where the policy holder is a member of a group for which consolidated accounts (within the meaning of Directive 83/349/EEC) are drawn up, the question whether the condition in sub-paragraph (2) above is met shall be determined by reference to those accounts.
(5)For the purposes of sub-paragraph (1)(c) above as it applies where the policy holder is a professional association, joint venture or temporary grouping, the question whether the condition in sub-paragraph (2) above is met shall be determined by reference to the aggregate of the figures of the description in question for all the members of the professional association, joint venture or temporary grouping.
(6)In sub-paragraphs (1) to (5) above “business” includes a trade or profession and, for the purposes of sub-paragraph (1)(c) above, any activity of a professional association, joint venture or temporary grouping.
(7)For the purposes of this paragraph, where an amount is denominated in any accounts in a currency other than the euro, it shall be converted into its equivalent in euros using the London closing exchange rate for that currency and the euro for the last day of the period to which the accounts relate.
(8)In this paragraph—
“euro” means the single currency adopted or proposed to be adopted as its currency by a member State in accordance with the Treaty establishing the European Community;
“financial year”, in relation to any person, means the period (not exceeding 12 months) for which that person makes up accounts.]
Textual Amendments
F3784Sch. 25 paras. 11A, 11B inserted (retrospective to 27.11.2002 with effect in accordance with s. 200(2)(3) of the amending Act) by Finance Act 2003 (c. 14), s. 200(4), Sch. 42 para. 4
F3787Words in Sch. 25 para. 11B(3) substituted (1.10.2009) by The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2009 (S.I. 2009/1890), arts. 1, 3(5)(c)
F3788Words in Sch. 25 para. 11B(3) omitted (1.10.2009) by virtue of The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2009 (S.I. 2009/1890), arts. 1, 3(5)(c)
F3789Words in Sch. 25 para. 11B(3)(a) substituted (6.4.2008 with effect in accordance with art. 1(2) of the amending S.I.) by The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2008 (S.I. 2008/954), arts. 1(1), 14(3)(a) (with art. 4)
F3790Words in Sch. 25 para. 11B(3)(b) substituted (6.4.2008 with effect in accordance with art. 1(2) of the amending S.I.) by The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2008 (S.I. 2008/954), arts. 1(1), 14(3)(b) (with art. 4)
F3791Words in Sch. 25 para. 11B(3)(c) substituted (6.4.2008 with effect in accordance with art. 1(2) of the amending S.I.) by The Companies Act 2006 (Consequential Amendments) (Taxes and National Insurance) Order 2008 (S.I. 2008/954), arts. 1(1), 14(3)(c) (with art. 4)
12(1)Subject to sub-paragraph (2) below, in paragraphs 6 and 8(3) above and [F3792[F3793in]] sub-paragraphs (4) and (5) below “holding company” means—U.K.
(a)a company the business of which consists wholly or mainly in the holding of shares or securities of companies which are either local holding companies and its 90 per cent. subsidiaries or trading companies and either its 51 per cent. subsidiaries or companies falling within paragraph 6(5) above; or
(b)a company which would fall within paragraph (a) above if there were disregarded so much of its business as consists in the holding of property or rights of any description for use wholly or mainly by companies which it controls and which are resident in the territory in which it is resident.
(2)In determining whether a company is a holding company for the purposes of paragraph 6(3) above (and, accordingly, whether the company is or may be a local holding company), sub-paragraph (1) above shall have effect with the omission from paragraph (a) thereof of the words “either local holding companies and its 90 per cent. subsidiaries or”.
(3)In its application for the purposes of this paragraph, [F3794 section 1154 of CTA 2010 has effect with the omission of the following—
(a)in subsection (2), the words “or indirectly”, and
(b)subsection (5).]
(4)For the purposes of sub-paragraph (3) F3795. . . of paragraph 6 above, as it applies in relation to a holding company part of whose business consists of activities other than the holding of shares or securities or the holding of property or rights as mentioned in paragraph (a) or (b) of sub-paragraph (1) above, the company’s gross income during any accounting period shall be determined as follows—
(a)there shall be left out of account so much of what would otherwise be the company’s gross income as is derived from any activity which, if it were the business in which the company is mainly engaged, would be such that paragraph 6(2) above would apply to the company; and
(b)to the extent that the receipts of the company from any other activity include receipts from the proceeds of sale of any description of property or rights, the cost to the company of the purchase of that property or those rights shall (to the extent that the cost does not exceed the receipts) be a deduction in calculating the company’s gross income, and no other deduction shall be made in respect of that activity.
(5)For the purposes of [F3796sub-paragraph (3)] of paragraph 6 above, so much of the income of a holding company as—
(a)is derived directly from another company which it controls and which is not a holding company [F3797F3798. . . ] but otherwise is, in terms of this Schedule, engaged in exempt activities [F3799or, in terms of sub-paragraph (5A) of that paragraph, is an exempt trading company], and
(b)was or could have been paid out of any non-trading income of that other company which is derived directly or indirectly from a third company connected or associated with it,
shall be treated, in relation to the holding company, as if it were not derived directly from companies which it controls.
(6)The reference in sub-paragraph (5) above to the non-trading income of a company is a reference to so much of its income as, if the company were carrying on its trade in the United Kingdom, would not be within the charge to corporation tax under [F3800section 35 of CTA 2009].
Textual Amendments
F3792Words in Sch. 25 para. 12(1) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 32(2); S.I. 1998/3173, art. 2
F3793Word in Sch. 25 para. 12(1) substituted (with effect in accordance with Sch. 16 para. 12 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 10(4)(a) (with Sch. 16 paras. 13-20)
F3794Words in Sch. 25 para. 12(3) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 147(3) (with Sch. 2)
F3795Words in Sch. 25 para. 12(4) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(4)(b) (with Sch. 16 paras. 13-20)
F3796Words in Sch. 25 para. 12(5) substituted (with effect in accordance with Sch. 16 para. 12 of the amending Act) by Finance Act 2009 (c. 10), Sch. 16 para. 10(4)(c)(i) (with Sch. 16 paras. 13-20)
F3797Words in Sch. 25 para. 12(5)(a) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 32(3)(a); S.I. 1998/3173, art. 2
F3798Words in Sch. 25 para. 12(5)(a) omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(4)(c)(ii) (with Sch. 16 paras. 13-20)
F3799Words in Sch. 25 para. 12(5)(a) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 32(3)(b); S.I. 1998/3173, art. 2
F3800Words in Sch. 25 para. 12(6) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 287(5) (with Sch. 2 Pts. 1, 2)
[F380112AU.K.F3802. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F3801Sch. 25 para. 12A inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 33; S.I. 1998/3173, art. 2
F3802Sch. 25 para. 12A omitted (with effect in accordance with Sch. 16 para. 12 of the repealing Act) by virtue of Finance Act 2009 (c. 10), Sch. 16 para. 10(5) (with Sch. 16 paras. 13-20)
[F3803Part 2A U.K.Trading Companies with Limited UK Connection
Textual Amendments
F3803Sch. 25 Pts. 2A, 2B (paras. 12B-12N) inserted (with effect in accordance with Sch. 12 para. 14(2) of the amending Act) by Finance Act 2011 (c. 11), Sch. 12 para. 3
IntroductoryU.K.
12B(1)For the purposes of section 748(1)(ba), a controlled foreign company (“C”) is exempt for an accounting period if the requirements of this Part of this Schedule are satisfied.U.K.
(2)The requirements are those imposed as to C's—
(a)business establishment (see paragraph 12C),
(b)business activities (see paragraph 12D),
(c)UK connection (see paragraph 12E), and
(d)finance income and relevant IP income (see paragraph 12F).
Business establishmentU.K.
12C(1)The requirement of this paragraph is that throughout the accounting period C has a business establishment in the territory in which it is resident.U.K.
(2)For the purposes of sub-paragraph (1)—
(a)paragraph 5(2) to (5) (special rules about residence of the company) applies as it applies for the purposes of Part 2 of this Schedule, and
(b)paragraph 7 (meaning of “business establishment”) applies as it applies for the purposes of paragraph 6(1)(a).
Business activitiesU.K.
12D(1)The requirement of this paragraph is that—U.K.
(a)C's business does not, at any time during the accounting period, include to a substantial extent non-exempt activities, or
(b)if C is wholly engaged in business falling within paragraph 11(1)(c) (banking etc), C's business does not, at any time during the accounting period, include to a substantial extent non-exempt activities which do not constitute investment business.
(2)For this purpose—
“non-exempt activities” means—
(a)the holding or managing of shares or securities,
(b)the holding of intellectual property,
(c)dealing in securities, other than in the capacity of a broker,
(d)the leasing of any description of property or rights,
(e)the investment in any manner of funds which would otherwise be available, directly or indirectly, for investment by or on behalf of any person (whether resident in the United Kingdom or not) who has, or is connected or associated with a person who has, control, either alone or together with other persons, of C, and
(f)if C is not a member of an insurance group throughout the accounting period, the effecting or carrying out of contracts of insurance between C and persons related to C;
“investment business” means activities within paragraphs (a) to (d) of paragraph 9(1).
(3)For the purposes of sub-paragraph (2)(f), a person is “related” to C if—
(a)the person is connected or associated with C,
(b)the person has a 25 per cent assessable interest in C in the case of the accounting period in question (within the meaning of paragraph 6(4C)), or
(c)if C is a controlled foreign company in that accounting period by virtue of subsection (1A) of section 747, the person is connected or associated with either or both of the two persons mentioned in that subsection.
(4)In sub-paragraph (2)—
“broker” includes any person offering to sell securities to, or purchase securities from, members of the public generally;
“contract of insurance” has the meaning given by Article 3(1) of the Financial Services and Markets Act 2000 (Regulated Activities) Order 2001;
“insurance group” has the meaning given by paragraph 11A(4);
“intellectual property” is to be construed in accordance with paragraph 9(1A);
“member of an insurance group” has the meaning given by paragraph 11A(6).
UK connectionU.K.
12E(1)The requirement of this paragraph is that C does not have a significant connection with the United Kingdom during the accounting period.U.K.
(2)C has a significant connection with the United Kingdom during the accounting period if Condition A or B is met.
(3)Condition A is that—
(a)the UK-connected gross income of C's business for that period exceeds 10% of the gross income of that business for that period, and
(b)sub-paragraph (4) does not apply.
(4)This sub-paragraph applies if—
(a)at all times in the accounting period there are sufficient individuals working for C in the territory in which it is resident, or in any other territory outside of the United Kingdom, who have the competence and authority to undertake all, or substantially all, of C's business,
(b)C's relevant profits for the accounting period do not exceed 10% of C's relevant operating expenses for that period, and
(c)the UK-connected gross income of C's business for that period does not exceed 50% of the gross income of that business for that period.
(5)Condition B is that—
(a)the UK-connected related-party business expenditure of C's business for that period exceeds 50% of the total related-party business expenditure of C's business for that period, and
(b)during the accounting period C has been involved in a scheme where the main purpose, or one of the main purposes, of any party to the scheme in entering into the scheme is to achieve a reduction in corporation tax or any tax chargeable as if it were corporation tax.
(6)For the purposes of sub-paragraph (4)(a), individuals are not to be regarded as working for C in any territory unless—
(a)they are employed by C in the territory, or
(b)they are otherwise directed by C to perform duties on its behalf in the territory.
(7)In this paragraph—
“” means any expenditure, other than capital expenditure, which gives rise, directly or indirectly, to income of a person related to C;
“relevant profits”, for an accounting period, means the total profits of C for that period calculated in accordance with generally accepted accounting practice (disregarding any capital gains or losses), but before any deduction for interest or tax;
“relevant operating expenses” of C means operating expenses of C other than—
(a)the cost of goods sold, and
(b)related-party business expenditure;
“scheme” means any scheme, arrangements or understanding of any kind whatever, whether or not legally enforceable, involving one or more transactions;
“UK-connected gross income” means the gross income derived, directly or indirectly, from persons who are within the charge to United Kingdom tax for all or part of the accounting period;
“” means related-party business expenditure which gives rise, directly or indirectly, to income of a person within the charge to United Kingdom tax in respect of that income;
“United Kingdom tax” means income tax or corporation tax;
and paragraph 12D(3) (persons “related” to C) applies for the purposes of this paragraph as it applies for the purposes of paragraph 12D(2)(f).
(8)In the case of a company which is within the charge to United Kingdom tax only because it carries on a trade in the United Kingdom through a permanent establishment there, for the purposes of sub-paragraph (7)—
(a)the gross income derived from that company is so much of the gross income as is attributable to that establishment, and
(b)the income received by that company is such of its income as is attributable to that establishment.
Finance income and relevant IP incomeU.K.
12F(1)The requirement of this paragraph is that not more than 5% of C's gross income for the accounting period falls within sub-paragraph (2).U.K.
(2)Gross income falls within this sub-paragraph to the extent that it is—
(a)finance income, or
(b)relevant IP income.
(3)“Finance income” means—
(a)any amount which in accordance with UK generally accepted accounting practice falls to be recognised as arising from a financial asset, and
(b)any return, in relation to an amount, which—
(i)is produced for C by an arrangement to which C is party, and
(ii)is economically equivalent to interest,
except to the extent that the return is taken into account in determining an amount within paragraph (a).
(4)“Relevant IP income” means royalties and receipts of a similar nature arising from intellectual property.
(5)For the purposes of sub-paragraph (3)(b), the amount of a return is the amount which by virtue of the return would, in calculating C's chargeable profits, be treated under section 486B of CTA 2009 (disguised interest to be regarded as profit from loan relationship) as a profit arising to C from a loan relationship.
(6)But, in calculating that profit for the purposes of sub-paragraph (5), sections 486B(7) and 486C to 486E of CTA 2009 are to be ignored.
(7)In this paragraph—
“economically equivalent to interest” is to be construed in accordance with section 486B(2) and (3) of CTA 2009;
“financial asset” means a financial asset as defined for the purposes of UK generally accepted accounting practice or international accounting standards;
“intellectual property” is to be construed in accordance with paragraph 9(1A).
Gross incomeU.K.
12G(1)References in this Part of this Schedule to C's gross income are to be construed in accordance with this paragraph.U.K.
(2)C's gross income for an accounting period does not include—
(a)any distribution that would not be included in C's chargeable profits by reason of it being exempt for the purposes of Part 9A of CTA 2009 (see section 931A of that Act), or
(b)any amount that would be taken into account in computing chargeable gains if C were within the charge to corporation tax.
(3)C's gross income for an accounting period includes—
(a)any income which accrues during that period to the trustees of a settlement in relation to which C is a settlor or a beneficiary, and
(b)any income which accrues during that period to a partnership of which C is a partner, apportioned between C and the other partners on a just and reasonable basis.
(4)Where there is more than one settlor or beneficiary in relation to the settlement mentioned in sub-paragraph (3)(a), the income is to be apportioned between C and the other settlors or beneficiaries on a just and reasonable basis.
(5)In this paragraph—
“distribution” has the same meaning as in the Corporation Tax Acts (see Part 23 of CTA 2010);
“partnership” includes an entity established under the law of a country or territory outside the United Kingdom of a similar character to a partnership; and “partner” is to be read accordingly.
Part 2B U.K.Companies Exploiting Intellectual Property with Limited UK Connection
IntroductoryU.K.
12H(1)For the purposes of section 748(1)(bb), a company (“C”) is exempt for an accounting period if the requirements of this Part of this Schedule are satisfied.U.K.
(2)The requirements are those imposed as to C's—
(a)business establishment (see paragraph 12I),
(b)intellectual property business (see paragraph 12J),
(c)other business activities (see paragraph 12K),
(d)UK connection (see paragraph 12L), and
(e)finance income (see paragraph 12M).
Business establishmentU.K.
12I(1)The requirement of this paragraph is that throughout the accounting period C has a business establishment in the territory in which it is resident.U.K.
(2)For the purposes of sub-paragraph (1)—
(a)paragraph 5(2) to (5) (special rules about residence of the company) applies as it applies for the purposes of Part 2 of this Schedule, and
(b)paragraph 7 (meaning of “business establishment”) applies as it applies for the purposes of paragraph 6(1)(a).
Intellectual property businessU.K.
12J(1)The requirement of this paragraph is that C's main business, throughout the accounting period, consists of the exploitation of intellectual property which does not have a relevant UK connection.U.K.
(2)For the purposes of sub-paragraph (1), if any part of C's main business consists of the exploitation of intellectual property which has a relevant UK connection, that part is to be ignored if it is an insignificant part of C's main business.
(3)Intellectual property has a relevant UK connection if—
(a)at any time during the accounting period or the 6 years immediately preceding that period, it has been held by a person resident in the United Kingdom, or
(b)activities relating to the creation, maintenance or enhancement of the intellectual property (other than activities of an incidental or insignificant nature) have been carried on by a person who for some or all of the period—
(i)beginning when the activities were first carried on by the person, and
(ii)ending at the end of the accounting period,
was related to C and within the charge to United Kingdom tax.
Other business activitiesU.K.
12K(1)The requirement of this paragraph is that—U.K.
(a)C does not, at any time during the accounting period, carry on any activities otherwise than in the course of its main business, or
(b)if it carries on any such activities (“secondary activities”), the secondary activities condition is met.
(2)The secondary activities condition is that either—
(a)the secondary activities do not, at any time during the accounting period, constitute a substantial part of the activities of C's business taken as a whole, or
(b)section 748(1)(b) or (ba) would apply to prevent an apportionment under section 747(3) falling to be made as regards that period, if C's business consisted only of the secondary activities carried on by it during the accounting period.
UK connectionU.K.
12L(1)The requirement of this paragraph is that C does not have a significant connection with the United Kingdom during the accounting period.U.K.
(2)C has a significant connection with the United Kingdom during the accounting period if—
(a)all or a substantial proportion of C's gross income for that period consists of income from the exploitation of intellectual property which derives from persons within the charge to United Kingdom tax, or
(b)during that period C incurs expenditure (other than expenditure of an incidental or insignificant nature) on—
(i)R&D sub-contractor payments, or
(ii)the creation, development or maintenance of relevant intellectual property,
and that expenditure forms part of the income of a person who for some or all of that period is related to C and within the charge to United Kingdom tax.
(3)In this paragraph—
“R&D sub-contractor payment” means a payment made by C to another person in respect of research and development contracted out by C to that person;
“relevant intellectual property” means intellectual property which does not have a relevant UK connection (see paragraph 12J(3)) and which C exploits in the course of its main business.
Finance incomeU.K.
12MU.K.The requirement of this paragraph is that not more than 5% of C's gross income for the accounting period consists of finance income (within the meaning of paragraph 12F(3)).
Interpretation of Part 2BU.K.
12N(1)For the purpose of this Part of this Schedule—U.K.
“intellectual property” is to be construed in accordance with paragraph 9(1A);
“United Kingdom tax” means corporation tax or income tax;
and paragraph 12G (meaning of “gross income”) applies as it applies for the purposes of Part 2A of this Schedule.
(2)For the purposes of this Part of this Schedule a person is “related” to C at a particular time if at that time—
(a)the person is connected or associated with C,
(b)the person has a 25 per cent assessable interest in C in the case of the accounting period of C in which that time falls (within the meaning of paragraph 6(4C)), or
(c)if C is a controlled foreign company in the accounting period in which that time falls by virtue of subsection (1A) of section 747, the person is connected or associated with either or both of the two persons mentioned in that subsection.
(3)In the case of a company which is within the charge to United Kingdom tax only because it carries on a trade in the United Kingdom through a permanent establishment there—
(a)for the purposes of paragraph 12J(3)(b), the activities carried on by the company are such of the activities as are carried on through that establishment,
(b)for the purposes of paragraph 12L(2)(a), the income derived from that company is such of the income so derived as is attributable to that establishment, and
(c)for the purposes of paragraph 12L(2)(b), the income of that company is such of its income as is attributable to that establishment.]
F3804F3804PART IIIU.K. THE PUBLIC QUOTATION CONDITION
Textual Amendments
F3804Sch. 25 Pt. 3 (paras. 13-15) repealed (with effect in accordance with Sch. 15 para. 10 of the repealing Act) by Finance Act 2007 (c. 11), Sch. 15 para. 8(2), Sch. 27 Pt. 2(15), Note
14(1)The condition in paragraph 13(2) above is not fulfilled with respect to an accounting period of a controlled foreign company if at any time in that period the total percentage of the voting power in the company possessed by all of the company’s principal members exceeds 85 per cent.
(2)For the purposes of paragraph 13(2) above shares in a controlled foreign company shall be deemed to be beneficially held by the public if they are held by any person other than—
(a)a person connected or associated with the company; or
(b)a principal member of the company;
and a corresponding construction shall be given to the reference to shares which have been allotted unconditionally to, or acquired unconditionally by, the public.
15(1)References in this Part of this Schedule to shares held by any person include references to any shares the rights or powers attached to which could, for the purposes of section 416, be attributed to that person under subsection (5) of that section.
(2)For the purposes of this Part of this Schedule—
(a)a person is a principal member of a controlled foreign company if he possesses a percentage of the voting power in the company of more than 5 per cent. and—
(i)where there are more than five such persons, if he is one of the five persons who possess the greatest percentages, or
(ii)if, because two or more persons possess equal percentage of the voting power in the company, there are no such five persons, he is one of six or more persons (so as to include those two or more who possess the equal percentages) who possess the greatest percentages; and
(b)a principal member’s holding consists of the shares which carry the voting power possessed by him.
(3)In arriving at the voting power which a person possesses, there shall be attributed to him any voting power which, for the purposes of section 416, would be attributed to him under subsection (5) or (6) of that section.
(4)In this Part of this Schedule “shares” include “stock”.
[F3806Part 3A U.K.Exempt Periods
Textual Amendments
F3806Sch. 25 Pt. 3A (paras. 15A-15G) inserted (with effect in accordance with Sch. 12 para. 14(2) of the amending Act) by Finance Act 2011 (c. 11), Sch. 12 para. 8
IntroductoryU.K.
15AU.K.The provisions of this Part of this Schedule have effect for the purposes of section 748(1)(f).
Beginning of exempt periodU.K.
15B(1)An exempt period begins in relation to a company (“X”) at a time (“the relevant time”) when—U.K.
(a)X is resident outside the United Kingdom,
(b)X is controlled by persons resident in the United Kingdom,
(c)there is at least one relevant UK corporate investor in X, and
(d)the requirements of paragraph 15C or 15D are met.
(2)There is a “relevant UK corporate investor in X” at a particular time if, at that time, there is a company which—
(a)is resident in the United Kingdom, and
(b)would, on the assumptions set out in sub-paragraph (3), be a company to which an apportionment of X's chargeable profits for the relevant accounting period would fall to be made in circumstances where section 747(5) would not prevent tax being chargeable on the company under section 747(4).
(3)The assumptions are—
(a)X has chargeable profits for the relevant accounting period,
(b)an apportionment of those profits falls to be made under section 747(3) for that period, and
(c)no reduction of those profits arises under section 751A, 751AA or 751AB.
(4)“The relevant accounting period” means the accounting period of X in which the time mentioned in sub-paragraph (2) falls.
15C(1)The requirements of this paragraph are that—U.K.
(a)no company was, at any time before the relevant time, a relevant UK corporate investor in X,
(b)no asset owned by X, or part of the business carried on by X, at the relevant time was previously owned, or carried on, by a company which—
(i)was under the control of persons resident in the United Kingdom at any time it owned the asset or carried on the part of the business, and
(ii)is or has been related to X,
(c)condition A, B, C or D is met, and
(d)no disqualifying relevant transaction occurs (see paragraph 15E).
(2)Condition A is that, immediately before the relevant time, X—
(a)was in existence, but
(b)was not a member of the same group of companies as any person who, at the relevant time, was a controlling UK person.
(3)Condition B is that—
(a)at the relevant time X is controlled by a company which is resident in the United Kingdom, and
(b)immediately before that time, X was controlled by that same company but that company was not then resident in the United Kingdom.
(4)Condition C is that—
(a)at the relevant time—
(i)X is controlled by a company which is resident in the United Kingdom (“the intermediate parent”), and
(ii)the intermediate parent is controlled by a company which is not resident in the United Kingdom (“the parent”), and
(b)immediately before that time X was controlled by the parent but not the intermediate parent.
(5)Condition D is that X—
(a)is a controlled foreign company at the time it is formed, and
(b)is formed by one or more persons for the purpose of controlling one or more companies in circumstances where it is expected that an exempt period will begin in relation to one or more of those companies at the time when X begins to control the company or companies.
(6)In this paragraph “controlling UK person” means a person resident in the United Kingdom who alone, or together with other such persons, controls X.
15D(1)The requirements of this paragraph are that—U.K.
(a)the relevant time falls after 23 March 2011,
(b)X has an accounting period during which 23 March 2011 falls,
(c)no company was, at any time during that accounting period, a relevant UK corporate investor in X,
(d)no company was, immediately before the relevant time, a relevant UK corporate investor in X,
(e)at the relevant time X is controlled by a company which—
(i)is resident in the United Kingdom, and
(ii)is not under the control of another body corporate, or two or more other bodies corporate taken together, and
(f)no disqualifying relevant transaction occurs (see paragraph 15E).
(2)In determining for the purposes of sub-paragraph (1)(e)(ii) whether a company is under the control of two or more bodies corporate taken together, a body corporate which holds less than 10% of the issued ordinary shares of that company is to be disregarded.
(3)For the purposes of sub-paragraph (2), a body corporate is treated as holding any shares held by persons who are connected or associated with the body corporate.
Disqualifying relevant transactionsU.K.
15E(1)This paragraph applies for the purposes of paragraph 15C and 15D.U.K.
(2)A disqualifying relevant transaction occurs if—
(a)a relevant transaction occurs at the relevant time (whether or not the transaction occurs pursuant to an agreement entered into by X before that time), or
(b)a relevant transaction occurs on or after 9 December 2010 but before the relevant time and that transaction forms part of an avoidance scheme.
(3)“Relevant transaction” means—
(a)the making by X of a loan or advance of an amount (other than a negligible amount) to a person who, at the time it is made, is related to X and subject to United Kingdom tax,
(b)an increase (other than an increase of a negligible amount) in the amount of an existing loan or advance made by X to a person who, at the time of the increase, is related to X and subject to United Kingdom tax,
(c)a change in the terms or conditions of an existing loan or advance made by X where—
(i)the loan or advance is to a person who, at the time the change is made, is related to X and subject to United Kingdom tax, and
(ii)the change has an effect (other than a negligible effect) on the amount of interest payable, or
(d)a transaction to which sub-paragraph (4) applies.
(4)This sub-paragraph applies to a transaction if—
(a)it is referable to an activity carried on by X as part, or the whole, of any non-exempt activities carried on by X,
(b)the results of the transaction are reflected in the profits arising in an accounting period of X and are not negligible in value, and
(c)the results of the transaction alone, or together with the results of one or more other transactions, achieves a reduction in United Kingdom tax.
(5)A transaction achieves, or two or more transactions together achieve, a reduction in United Kingdom tax if, had the transaction or transactions not been effected, any person—
(a)would have been liable for any such tax or for a greater amount of any such tax, or
(b)would not have been entitled to a relief from or repayment of any such tax or would have been entitled to a smaller relief from or repayment of any such tax.
(6)In this paragraph—
“avoidance scheme” means a scheme the main purpose, or one of the main purposes, of any party to which in entering into the scheme is to secure that section 748(1)(f) prevents an apportionment falling to be made under section 747(3) as regards an accounting period, or accounting periods, of X;
“non-exempt activities” has the meaning given by paragraph 12D(2);
“scheme” means any scheme, arrangements or understanding of any kind whatever, whether or not legally enforceable, involving one or more transactions;
“United Kingdom tax” means corporation tax (or any tax chargeable as if it were corporation tax) or income tax.
Ending of exempt periodU.K.
15F(1)An exempt period ends on the expiry of the period of 24 months which begins immediately after the first accounting period of X to end after the relevant time, unless sub-paragraph (2) applies.U.K.
(2)If an early termination event occurs after the relevant time but before the time the exempt period would end under sub-paragraph (1), the exempt period ends immediately before that event.
(3)An early termination event occurs if and when—
(a)a relevant transaction occurs, whether or not the transaction occurs pursuant to an agreement entered into by X before that time, or
(b)where the exempt period began because Condition D was met, X's business does not consist wholly in the holding of shares of companies which X controls, together with activities incidental to the holding of such shares.
Interpretation of Part 3AU.K.
15G(1)In this Part of this Schedule—U.K.
“group” means a company and any other companies it controls;
“the relevant time” has the meaning given by paragraph 15B;
“relevant transaction” has the meaning given by paragraph 15E;
“relevant UK corporate investor in X” has the meaning given by paragraph 15B(2);
“X” is to be construed in accordance with paragraph 15B.
(2)For the purposes of this Part of this Schedule a person is “related” to X at a particular time if—
(a)the person is connected or associated with X at that time,
(b)the person has a 25 per cent assessable interest in X in the case of the accounting period in which that time falls (within the meaning of paragraph 6(4C)), or
(c)if X is a controlled foreign company in the accounting period in which that time falls by virtue of subsection (1A) of section 747, the person is connected or associated with either or both of the two persons mentioned in that subsection.]
PART IVU.K. REDUCTIONS IN UNITED KINGDOM TAX AND DIVERSION OF PROFITS
16(1)The provisions of this Part of this Schedule have effect for the purposes of section 748(3).U.K.
(2)Any reference in paragraphs 17 and 18 below to a transaction—
(a)is a reference to a transaction [F3807the results of which are] reflected in the profits arising in an accounting period of a controlled foreign company; and
(b)includes a reference to [F3808two or more transactions taken together, the results of at least one of which are so reflected].
Textual Amendments
F3807Words in Sch. 25 para. 16(2)(a) inserted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 4(6)(a)
F3808Words in Sch. 25 para. 16(2)(b) substituted (with effect in accordance with s. 182 of the amending Act) by Finance Act 1996 (c. 8), Sch. 36 para. 4(6)(b)
17(1)A transaction achieves a reduction in United Kingdom tax if, had the transaction not been effected, any person—U.K.
(a)would have been liable for any such tax or for a greater amount of any such tax; or
(b)would not have been entitled to a relief from or repayment of any such tax or would have been entitled to a smaller relief from or repayment of any such tax.
(2)In this Part of this Schedule and section 748(3) “United Kingdom tax” means income tax, corporation tax or capital gains tax.
18U.K.It is the main purpose or one of the main purposes of a transaction to achieve a reduction in United Kingdom tax if this is the purpose or one of the main purposes—
(a)of the controlled foreign company concerned; or
(b)of a person who has an interest in that company at any time during the accounting period concerned.
19(1)The existence of a controlled foreign company achieves a reduction in United Kingdom tax by a diversion of profits from the United Kingdom in an accounting period if it is reasonable to suppose that, had neither the company nor any company related to it been in existence—U.K.
(a)the whole or a substantial part of the receipts which are reflected in the controlled foreign company’s profits in that accounting period would have been received by a company or individual resident in the United Kingdom; and
(b)that company or individual or any other person resident in the United Kingdom either—
(i)would have been liable for any United Kingdom tax or for a greater amount of any such tax; or
(ii)would not have been entitled to a relief from or repayment of any such tax or would have been entitled to a smaller relief from or repayment of any such tax.
(2)For the purposes of sub-paragraph (1) above, a company is related to a controlled foreign company if—
(a)it is resident outside the United Kingdom; and
(b)it is connected or associated with the controlled foreign company; and
(c)in relation to any company or companies resident in the United Kingdom, it fulfils or could fulfil, directly or indirectly, substantially the same functions as the controlled foreign company.
(3)Any reference in sub-paragraph (1) above to a company resident in the United Kingdom includes a reference to such a company which, if the controlled foreign company in question were not in existence, it is reasonable to suppose would have been established.
Section 754(5).
SCHEDULE 26U.K. RELIEFS AGAINST LIABILITY FOR TAX IN RESPECT OF CHARGEABLE PROFITS
Trading losses and group relief etc. M296U.K.
Marginal Citations
M296Source—1984 Sch.18.
1(1)In any case where—U.K.
(a)an amount of chargeable profits is apportioned to a company resident in the United Kingdom, and
(b)the company is entitled, or would on the making of a claim be entitled, in computing its profits for the appropriate accounting period, to a deduction in respect of any relevant allowance, F3809. . .
(c)F3809. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
then, on the making of a claim, a sum equal to corporation tax at the appropriate rate on so much of the relevant allowance F3810. . . as is specified in the claim shall be set off against the company’s liability to tax under section 747(4)(a) in respect of the chargeable profits apportioned to it.
(2)In this paragraph—
(a)“the appropriate accounting period” means the accounting period for which, by virtue of section 754(2), the company is [F3811chargeable to tax by virtue of this Chapter] in respect of the chargeable profits concerned; and
(b)“the appropriate rate” means the rate of corporation tax applicable to profits of the appropriate accounting period or, if there is more than one such rate, the average rate over the whole accounting period.
(3)In this paragraph “relevant allowance” means—
(a)any loss to which [F3812section 37 or 62(1) to (3) of CTA 2010] applies;
(b)any [F3813qualifying charitable donation];
(c)any expenses of management to which [F3814section 1219(1) of CTA 2009] applies;
[F3815(cc)any expenses deduction under section 76(1);]
(d)so much of any allowance to which section 74 of the 1968 Act applies as falls within subsection (3) of that section; F3816. . .
(e)any amount available to the company by way of group relief; [F3817and
(f)any non-trading deficit on its loan relationships.]
(4)F3818. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(5)Where, by virtue of sub-paragraph (1) above, a sum is set off against a liability to tax, so much of the relevant allowance as gives rise to the amount set off shall be regarded for the purposes of the Tax Acts as having been allowed as a deduction against the company’s profits in accordance with the appropriate provisions of those Acts.
(6)F3818. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3809Sch. 26 para. 1(1)(c) and preceding word repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 34(2)(a), Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
F3810Words in Sch. 26 para. 1(1) repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 34(2)(b), Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
F3811Words in Sch. 26 para. 1(2)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 34(3); S.I. 1998/3173, art. 2
F3812Words in Sch. 26 para. 1(3)(a) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 148(2) (with Sch. 2)
F3813Words in Sch. 26 para. 1(3)(b) substituted (1.4.2010 with effect in accordance with s. 1184(1) of the amending Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 148(3) (with Sch. 2)
F3814Words in Sch. 26 para. 1(3)(c) substituted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 288 (with Sch. 2 Pts. 1, 2)
F3815Sch. 26 para. 1(3)(cc) inserted (28.9.2004 with effect in accordance with art. 1(2) of the amending S.I.) by The Finance Act 2004, Sections 38 to 40 and 45 and Schedule 6 (Consequential Amendment of Enactments) Order 2004 (S.I. 2004/2310), art. 2, Sch. para. 38(2)
F3816Word at the end of Sch. 26 para. 1(3)(d) repealed (with effect in accordance with s. 105(1) of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(3), Note (with Sch. 15)
F3817Sch. 26 para. 1(3)(f) and preceding word inserted (with effect in accordance with s. 105(1) of the amending Act) by Finance Act 1996 (c. 8), Sch. 14 para. 53 (with Sch. 15)
F3818Sch. 26 para. 1(4)(6) repealed (with effect in accordance with Sch. 17 para. 37 of the repealing Act) by Finance Act 1998 (c. 36), Sch. 17 para. 34(4)(5), Sch. 27 Pt. 3(27), Note; S.I. 1998/3173, art. 2
Advance corporation taxU.K.
2U.K.F3819. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3819Sch. 26 para. 2 repealed (with effect in accordance with Sch. 3 para. 44(3) of the repealing Act) by Finance Act 1998 (c. 36), Sch. 3 para. 44(2), Sch. 27 Pt. 3(2), Note (with Sch. 3 para. 44(4))
Gains on disposal of shares in controlled foreign companiesU.K.
3(1)This paragraph applies in any case where—U.K.
[F3820(a)an accounting period of a controlled foreign company (“the apportionment period”) is one in respect of which an apportionment under section 747(3) falls to be made; and]
(b)the company’s chargeable profits for [F3821the apportionment period] have been apportioned among the persons in subsection (3) of that section; and
(c)a company resident in the United Kingdom (“the claimant company”) disposes of—
(i)shares in the controlled foreign company, or
(ii)shares in another company which, in whole or in part, give rise to the claimant company’s interest in the controlled foreign company,
being, in either case, shares acquired before the end of [F3821the apportionment period]; and
(d)by virtue of the apportionment referred to in paragraph (b) above, a sum is, under section 747(4)(a), [F3822chargeable on] the claimant company as if it were an amount of corporation tax; and
(e)the claimant company makes a claim for relief under this paragraph;
and in this paragraph the disposal mentioned in paragraph (c) above is referred to as “the relevant disposal”.
(2)Subject to the following provisions of this paragraph, in the computation under Chapter [F3823III of Part II of the 1992] Act of the gain accruing on the relevant disposal, the appropriate fraction of the sum referred to in sub-paragraph (1)(d) above shall be allowable as a deduction; but to the extent that any sum has been allowed as a deduction under this sub-paragraph it shall not again be allowed as a deduction on any claim under this paragraph (whether made by the claimant company or another company).
(3)In relation to the relevant disposal, the appropriate fraction is—

where—
A is the average market value in [F3824the apportionment period] of the shares disposed of, and
B is the average market value in that period of the interest in the controlled foreign company which, in the case of the claimant company, was taken into account in the apportionment referred to in sub-paragraph (1)(b) above.
(4)Where, before the relevant disposal—
(a)a dividend is paid by the controlled foreign company, and
(b)the profits out of which the dividend is paid are those from which the chargeable profits referred to in sub-paragraph (1)(b) above are derived, and
(c)at least one of the two conditions in sub-paragraph (5) below is fulfilled,
this paragraph does not apply in relation to a sum [F3825chargeable under section 747(4)(a)] in respect of so much of the chargeable profits as corresponds to the profits which the dividend represents.
(5)The conditions referred to in sub-paragraph (4) above are—
(a)that the effect of the payment of the dividend is such that the value of the shares disposed of by the relevant disposal is less after the payment than it was before it; and
(b)that, in respect of a dividend paid or payable on the shares disposed of by the relevant disposal, the claimant company is, by virtue of paragraph 4(2) below, entitled under [F3826Part 2 of TIOPA 2010] to relief (by way of underlying tax) by reference to sums which include the sum referred to in sub-paragraph (1)(d) above.
(6)A claim for relief under this paragraph shall be made before the expiry of the period of three months beginning—
(a)at the end of the accounting period in which the relevant disposal occurs; or
(b)if it is later, on the date on which the assessment to tax for which the claimant company is liable by virtue of section 747(4)(a) becomes final and conclusive.
[F3827(6A)Nothing in—
(a)paragraph 10 of Schedule 18 to the Finance Act 1998 (claims or elections in company tax returns), or
(b)Schedule 1A to the Management Act (claims or elections not included in returns),
shall apply, whether by virtue of section 754 or otherwise, to a claim under sub-paragraph (6) above.]
(7)In identifying for the purposes of this paragraph shares in a company with shares of the same class which are disposed of by the relevant disposal, shares acquired at an earlier time shall be deemed to be disposed of before shares acquired at a later time.
Textual Amendments
F3820Sch. 26 para. 3(1)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 35(2); S.I. 1998/3173, art. 2
F3821Words in Sch. 26 para. 3(1)(b)(c) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 35(3); S.I. 1998/3173, art. 2
F3822Words in Sch. 26 para. 3(1)(d) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 35(4); S.I. 1998/3173, art. 2
F3823Words in Sch. 26 para. 3 substituted (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 10 para. 14(62) (with ss. 60, 101(1), 171, 201(3))
F3824Words in Sch. 26 para. 3(3) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 35(5); S.I. 1998/3173, art. 2
F3825Words in Sch. 26 para. 3(4) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 35(6); S.I. 1998/3173, art. 2
F3826Words in Sch. 26 para. 3(5)(b) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(2) (with Sch. 9)
F3827Sch. 26 para. 3(6A) inserted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 35(7); S.I. 1998/3173, art. 2
Dividends from the controlled foreign companyU.K.
4(1)This paragraph applies in any case where—U.K.
[F3828(a)an accounting period of a controlled foreign company is one in respect of which an apportionment under subsection (3) of section 747 falls to be made; and]
(b)the company’s chargeable profits for that period have been apportioned among the persons referred to in [F3829that subsection], and
(c)the controlled foreign company pays a dividend in whole or in part out of the total profits from which (in accordance with subsection (6)(a) of that section) those chargeable profits are derived.
(2)Subject to paragraphs 5 and 6 below, where this paragraph applies, the aggregate of the sums [F3830chargeable on] companies resident in the United Kingdom in accordance with section 747(4)(a) in respect of the chargeable profits referred to in sub-paragraph (1)(b) above shall be treated for the purposes of [F3831Part 2 of TIOPA 2010 (double taxation relief)] as if it were an amount of tax paid in respect of the profits concerned under the law of the territory in which the controlled foreign company was resident and, accordingly, as underlying tax for the purposes of Chapter II of that Part.
(3)In the following provisions of this paragraph and in paragraphs 5 and 6 below, the aggregate of the sums which, under sub-paragraph (2) above, fall to be treated as underlying tax is referred to as the “gross attributed tax”.
(4)If, in the case of a person who receives the dividend, [F3832section 36, 40, 41 or 42 of TIOPA 2010] has the effect of reducing the amount which (apart from that section) would have been the amount of the credit for foreign tax which is to be allowed to that person, then, for the purposes of sub-paragraph (5) below, the amount of that reduction shall be determined and so much of it as does not exceed the amount of the foreign tax, exclusive of underlying tax, for which credit is to be allowed in respect of the dividend is in that sub-paragraph referred to as “the wasted relief”.
(5)Except for the purpose of determining the amount of the wasted relief, the gross attributed tax shall be treated as reduced by the aggregate of the wasted relief arising in the case of all the persons falling within sub-paragraph (4) above and, on the making of a claim by any of the companies referred to in sub-paragraph (2) above—
(a)the amount of tax [F3830chargeable on] the company in accordance with section 747(4)(a) in respect of the chargeable profits referred to in sub-paragraph (1) (b) above shall, where appropriate, be reduced; and
(b)all such adjustments (whether by repayment of tax or otherwise) shall be made as are appropriate to give effect to any reduction under paragraph (a) above.
Textual Amendments
F3828Sch. 26 para. 4(1)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 36(2); S.I. 1998/3173, art. 2
F3829Words in Sch. 26 para. 4(1)(b) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 36(3); S.I. 1998/3173, art. 2
F3830Words in Sch. 26 para. 4(2)(5)(a) substituted (with effect in accordance with Sch. 17 para. 37 of the amending Act) by Finance Act 1998 (c. 36), Sch. 17 para. 36(4)(5); S.I. 1998/3173, art. 2
F3831Words in Sch. 26 para. 4(2) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(3) (with Sch. 9)
F3832Words in Sch. 26 para. 4(4) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(4) (with Sch. 9)
5(1)In so far as any provision of—U.K.
[F3833(a)arrangements which have effect under section 2(1) of TIOPA 2010 (double taxation relief by agreement with territories outside the United Kingdom), or
(b)unilateral relief arrangements for a territory outside the United Kingdom (as defined by section 8 of that Act),]
makes relief which is related to foreign dividends received by a company resident in the United Kingdom conditional upon that company either having a particular degree of control of the company paying the dividend or being a subsidiary of another company which has that degree of control, that condition shall be treated as fulfilled in considering whether any such company is by virtue of paragraph 4(2) above entitled to relief under [F3834Part 2 of TIOPA 2010] in respect of any of the gross attributed tax.
(2)Notwithstanding anything in paragraph 4(2) above, in [F3835section 31(2)(b) and (3) of TIOPA 2010] the expression “underlying tax” does not include gross attributed tax.
(3)In a case where the controlled foreign company pays a dividend otherwise than out of specified profits and, on the apportionment referred to in paragraph 4(1) above, less than the whole of the chargeable profits of the controlled foreign company concerned is apportioned to companies which are resident in the United Kingdom and liable for tax thereon as mentioned in section 747(4)(a)—
(a)the gross attributed tax shall be regarded as attributable to a corresponding proportion of the profits in question, and in this sub-paragraph the profits making up that proportion are referred to as “taxed profits”;
(b)so much of the dividend as is received by, or by a successor in title of, any such company shall be regarded as paid primarily out of taxed profits; and
(c)so much of the dividend as is received by any other person shall be regarded as paid primarily out of profits which are not taxed profits.
(4)The reference in sub-paragraph (3)(b) above to a successor in title of a company resident in the United Kingdom is a reference to a person who is such a successor in respect of the whole or any part of that interest in the controlled foreign company by virtue of which an amount of its chargeable profits was apportioned to that company.
Textual Amendments
F3833Sch. 26 para. 5(1)(a)(b) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(5) (with Sch. 9)
F3834Words in Sch. 26 para. 5(1) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(6) (with Sch. 9)
F3835Words in Sch. 26 para. 5(2) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(7) (with Sch. 9)
6(1)In any case where—U.K.
(a)on a claim for relief under paragraph 3 above, the whole or any part of any sum has been allowed as a deduction on a disposal of shares in any company; and
(b)that sum forms part of the gross attributed tax in relation to a dividend paid by that company; and
(c)a person receiving the dividend in respect of the shares referred to in paragraph (a) above (“the primary dividend”) or any other relevant dividend is, by virtue of paragraph 4(2) above, entitled under [F3836Part 2 of TIOPA 2010] to relief (by way of underlying tax) by reference to the whole or any part of the gross attributed tax;
the amount which, apart from this paragraph, would be available by way of any such relief to the person referred to in paragraph (c) above shall be reduced or, as the case may be, extinguished by deducting therefrom the amount allowed by way of relief as mentioned in paragraph (a) above.
(2)For the purposes of sub-paragraph (1)(c) above, in relation to the primary dividend, another dividend is a relevant dividend if—
(a)it is a dividend in respect of shares in a company which is resident outside the United Kingdom; and
(b)it represents profits which, directly or indirectly, consist of or include the primary dividend.
Textual Amendments
F3836Words in Sch. 26 para. 6(1)(c) substituted (1.4.2010 with effect in accordance with s. 381(1) of the amending Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 35(8) (with Sch. 9)
F3837F3837SCHEDULE 27U.K.
Textual Amendments
F3837Sch. 27 repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with saving in Sch. 1 para. 3(4)) (subject, as saved, to modification by Taxation (International and Other Provisions) Act 2010 (c. 8), s. 381(1), Sch. 9 para. 24)
PART IU.K. THE DISTRIBUTION TEST
Requirements as to distributionsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Funds operating equalisation arrangementsU.K.
2(1)In the case of an offshore fund which throughout any account period operates equalisation arrangements, on any occasion in that period when there is a disposal to which this sub-paragraph applies, the fund shall be treated for the purposes of this Part of this Schedule as making a distribution of an amount equal to so much of the consideration for the disposal as, in accordance with this paragraph, represents income accrued to the date of the disposal.
(2)Sub-paragraph (1) above applies to a disposal—
(a)which is a disposal of a material interest in the offshore fund concerned; and
(b)which is a disposal to which this Chapter applies (whether by virtue of section 758(3) or otherwise) or is one to which this Chapter would apply if subsections (5) and (6) of that section applied generally and not only for the purpose of determining whether, by virtue of subsection (3) of that section, there is a disposal to which this Chapter applies; and
(c)which is not a disposal with respect to which the conditions in subsection (4) of that section are fulfilled; and
(d)which is a disposal to the fund itself or to the persons concerned in the management of the fund (“the managers”) in their capacity as such.
(3)On a disposal to which sub-paragraph (1) above applies, the part of the consideration which represents income accrued to the date of the disposal is, subject to sub-paragraph (4) and paragraph 4(4) below, the amount which would be credited to the equalisation account of the offshore fund concerned in respect of accrued income if, on the date of the disposal, the material interest which is disposed of were acquired by another person by way of initial purchase.
(4)If, after the beginning of the period by reference to which the accrued income referred to in sub-paragraph (3) above is calculated, the material interest disposed of by a disposal to which sub-paragraph (1) above applies was acquired by way of initial purchase (whether or not by the person making the disposal)—
(a)there shall be deducted from the amount which, in accordance with sub-paragraph (3) above, would represent income accrued to the date of the disposal, the amount which on that acquisition was credited to the equalisation account of the fund in respect of accrued income; and
(b)if in that period there has been more than one such acquisition of that material interest by way of initial purchase, the deduction to be made under this sub-paragraph shall be the amount so credited to the equalisation account on the latest such acquisition prior to the disposal in question.
(5)Where, by virtue of this paragraph, an offshore fund is treated for the purposes of this Part of this Schedule as making a distribution on the occasion of a disposal, the distribution shall be treated for those purposes—
(a)as complying with paragraph 1(1)(d) above; and
(b)as made out of the income of the fund for the account period in which the disposal occurs; and
(c)as paid, immediately before the disposal, to the person who was then the holder of the interest disposed of.
(6)In any case where—
(a)a distribution in respect of an interest in an offshore fund is made to the managers of the fund, and
(b)their holding of that interest is in their capacity as such, and
(c)at the time of the distribution, the fund is operating equalisation arrangements,
the distribution shall not be taken into account for the purposes of paragraph 1(1) above except to the extent that the distribution is properly referable to that part of the period for which the distribution is made during which that interest has been held by the managers of the fund in their capacity as such.
(7)Subsection (2) of section 758 applies for the purposes of this paragraph as it applies for the purposes of that section.
[F3843Certain foreign income]U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Commodity incomeU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .United Kingdom equivalent profitsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IIU.K. MODIFICATIONS OF CONDITIONS FOR CERTIFICATION IN CERTAIN CASES
Exclusion of investments in distributing offshore fundsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .8(1)The modification referred to in paragraph 6(3)(b) above is that, in determining whether the condition in paragraph 1(1)(b)(ii) above is fulfilled with respect to the account period of the primary fund referred to in paragraph 6(1) above, the United Kingdom equivalent profits of the primary fund for that period shall be treated as increased by the primary fund’s share of the excess income (if any) of the qualifying fund which is attributable to that period.
(2)For the purposes of this paragraph, the excess income of the qualifying fund for any account period of that fund is the amount (if any) by which its United Kingdom equivalent profits for that account period exceed the amount of the distributions made for that period, as determined for the purposes of the application of paragraph 1(1) above to the qualifying fund.
(3)If an account period of the qualifying fund coincides with an account period of the primary fund, then the excess income (if any) of the qualifying fund for that period is the excess income which is attributable to that period of the primary fund.
(4)In a case where sub-paragraph (3) above does not apply, the excess income of the qualifying fund which is attributable to an account period of the primary fund is the appropriate fraction of the excess income (if any) of the qualifying fund for any of its account periods which comprises the whole or any part of the account period of the primary fund and, if there is more than one such account period of the qualifying fund, the aggregate of the excess income (if any) of each of them.
(5)For the purposes of sub-paragraph (4) above, the appropriate fraction is—

where—
A is the number of days in the account period of the primary fund which are also days in an account period of the qualifying fund; and
B is the number of days in that account period of the qualifying fund or, as the case may be, in each of those account periods of that fund which comprises the whole or any part of the account period of the primary fund.
9(1)The references in paragraphs 7 and 8(1) above to the primary fund’s share of—
(a)an interest forming part of the assets of the qualifying fund, or
(b)the excess income (as defined in paragraph 8 above) of the qualifying fund,
shall be construed as references to the fraction specified in sub-paragraph (2) below of that interest or excess income.
(2)In relation to any account period of the primary fund, the fraction referred to in sub-paragraph (1) above is—

where—
C is the average value of the primary fund’s holding of interests in the qualifying fund during that period; and
D is the average value of all the interests in the qualifying fund held by any persons during that period.
Offshore funds investing in trading companiesU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Offshore funds with wholly-owned subsidiariesU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Offshore funds with interests in dealing and management companiesU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Disregard of certain investments forming less than 5 per cent. of a fundU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Power of Board to disregard certain breaches of conditionsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IIIU.K. CERTIFICATION PROCEDURE
Application for certificationU.K.
15(1)The Board shall, in such manner as they think appropriate, certify an offshore fund as a distributing fund in respect of an account period if—
(a)an application in respect of that period is made under this paragraph; and
(b)the application is accompanied by the accounts of the fund for, or for a period which includes, the account period to which the application relates; and
(c)there is furnished to the Board such information as they may reasonably require for the purpose of determining whether the fund should be so certified; and
(d)they are satisfied that nothing in section 760(2) or (3) prevents the fund being so certified.
(2)An application under this paragraph shall be made to the Board by the fund or by a trustee or officer thereof on behalf of the fund and may be so made—
(a)before the expiry of the period of six months beginning at the end of the account period to which the application relates; or
(b)at such later time as the Board may in any particular case allow.
(3)In any case where, on an application under this paragraph, the Board determine that the offshore fund concerned should not be certified as a distributing fund in respect of the account period to which the application relates, they shall give notice of that fact to the fund.
(4)If at any time it appears to the Board that the accounts accompanying an application under this paragraph in respect of any account period of an offshore fund or any information furnished to the Board in connection with such an application is or are not such as to make full and accurate disclosure of all facts and considerations relevant to the application, they shall give notice to the fund accordingly, specifying the period concerned.
(5)Where a notice is given by the Board under sub-paragraph (4) above, any certification by them in respect of the account period in question shall be void.
AppealsU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .PART IVU.K. SUPPLEMENTARY
Assessment: effect of non-certificationU.K.
Postponement of tax pending determination of question as to certificationU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Information as to decisions on certification etc.U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Application of this Schedule in relation to umbrella funds and funds comprising more than one class of interestU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F3885F3885SCHEDULE 28U.K.
Textual Amendments
F3885Sch. 28 repealed (1.12.2009 with effect in accordance with reg. 1(2) of the repealing S.I.) by The Offshore Funds (Tax) Regulations 2009 (S.I. 2009/3001), regs. 1(1), 13(2)(3), Sch. 2 (with saving in Sch. 1 para. 3(4))
PART IU.K. DISPOSALS OF INTERESTS IN NON-QUALIFYING FUNDS
InterpretationU.K.
1In this Part of this Schedule “material disposal” means a disposal to which this Chapter applies, otherwise than by virtue of section 758.
Calculation of unindexed gainU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Gains since 1st January 1984U.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .The offshore income gainU.K.
5(1)Subject to sub-paragraph (2) below, a material disposal gives rise to an offshore income gain of an amount equal to the unindexed gain on that disposal.
(2)In any case where—
(a)paragraph 4 above applies, and
(b)the post-1983 gain on the material disposal is less than the unindexed gain on the disposal,
the offshore income gain to which the disposal gives rise is an amount equal to the post-1983 gain.
PART IIU.K. DISPOSALS INVOLVING AN EQUALISATION ELEMENT
6(1)Subject to paragraph 7 below, a disposal to which this Chapter applies by virtue of section 758(3) gives rise to an offshore income gain of an amount equal to the equalisation element relevant to the asset disposed of.
(2)Subject to sub-paragraphs (4) to (6) below, the equalisation element relevant to the asset disposed of by a disposal falling within sub-paragraph (1) above is the amount which would be credited to the equalisation account of the offshore fund concerned in respect of accrued income if, on the date of the disposal, the asset which is disposed of were acquired by another person by way of initial purchase.
(3)In the following provisions of this Part of this Schedule, a disposal falling within sub-paragraph (1) above is referred to as a “disposal involving an equalisation element”.
(4)Where the asset disposed of by a disposal involving an equalisation element was acquired by the person making the disposal after the beginning of the period by reference to which the accrued income referred to in sub-paragraph (2) above is calculated, the amount which, apart from this sub-paragraph, would be the equalisation element relevant to that asset shall be reduced by the following amount, that is to say—
(a)if that acquisition took place on or after 1st January 1984, the amount which, on that acquisition, was credited to the equalisation account of the offshore fund concerned in respect of accrued income or, as the case may be, would have been so credited if that acquisition had been an acquisition by way of initial purchase; and
(b)in any other case, the amount which would have been credited to that account in respect of accrued income if that acquisition had been an acquisition by way of initial purchase taking place on 1st January 1984.
(5)In any case where—
(a)the asset disposed of by a disposal involving an equalisation element was acquired by the person making the disposal at or before the beginning of the period by reference to which the accrued income referred to in sub-paragraph (2) above is calculated, and
(b)that period began before 1st January 1984 and ends after that date,
the amount which, apart from this sub-paragraph, would be the equalisation element relevant to that asset shall be reduced by the amount which would have been credited to the equalisation account of the offshore fund concerned in respect of accrued income if the acquisition referred to in paragraph (a) above had been an acquisition by way of initial purchase taking place on 1st January 1984.
(6)Where there is a disposal involving an equalisation element, then, to the extent that any amount which was or would be credited to the equalisation account of the offshore fund in respect of accrued income, as mentioned in any of sub-paragraphs (2) to (5) above, represents profits from dealing in commodities, within the meaning of paragraph 4 of Schedule 27, one half of that accrued income shall be left out of account in determining under those sub-paragraphs the equalisation element relevant to the asset disposed of by that disposal.
7(1)For the purposes of this Part of this Schedule, there shall be determined, in accordance with paragraph 8 below, the Part I gain (if any) on any disposal involving an equalisation element.
(2)Notwithstanding anything in paragraph 6 above—
(a)if there is no Part I gain on a disposal involving an equalisation element, that disposal shall not give rise to an offshore income gain; and
(b)if, apart from this paragraph, the offshore income gain on a disposal involving an equalisation element would exceed the Part I gain on that disposal, the offshore income gain to which that disposal gives rise shall be reduced to an amount equal to that Part I gain.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .Part 3 U.K.Supplementary
Application of this Schedule in relation to umbrella funds and funds comprising more than one class of interestU.K.
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .F3891F3891[F3892Schedule 28AU.K.[F3893Change in ownership of company with investment business: deductions]]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3891Sch. 28A repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 1 para. 149, Sch. 3 Pt. 1 (with Sch. 2)
F3892Sch. 28A inserted (with effect in accordance with Sch. 26 para. 5 of the amending Act) by Finance Act 1995 (c. 4), Sch. 26 para. 3
F3893Sch. 28A heading substituted (28.9.2004 with effect in accordance with art. 1(2) of the amending S.I.) by virtue of The Finance Act 2004, Sections 38 to 40 and 45 and Schedule 6 (Consequential Amendment of Enactments) Order 2004 (S.I. 2004/2310), art. 2, Sch. para. 39(11)
F3981F3981[F3982SCHEDULE 28AAU.K. Provision not at arm’s length]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F3981Sch. 28AA repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 111, Sch. 10 Pt. 2 (with Sch. 9)
F3982Sch. 28AA inserted (with effect in accordance with s. 108(5)-(7) of the amending Act) by Finance Act 1998 (c. 36), s. 108(2), Sch. 16
F4042F4042[F4043SCHEDULE 28ABU.K.Section 804ZA: prescribed schemes and arrangements]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4042Sch. 28AB repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 8 para. 36, Sch. 10 Pt. 1 (with Sch. 9)
F4043Sch. 28AB inserted (with effect in accordance with s. 87(3)-(5) of the amending Act) by Finance Act 2005 (c. 7), s. 87(2), Sch. 5
F4047F4047[F4048SCHEDULE 28BU.K. Venture Capital Trusts: Meaning of “qualifying holdings”]
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4047Sch. 28B repealed (6.4.2007 with effect in accordance with s. 1034(1) of the repealing Act) by Income Tax Act 2007 (c. 3), Sch. 1 para. 240, Sch. 3 Pt. 1 (with Sch. 2)
F4048Sch. 28B inserted (1.5.1995) by Finance Act 1995 (c. 4), s. 70(2), Sch. 14
s.844
SCHEDULE 29U.K. CONSEQUENTIAL AMENDMENTS
THE CAPITAL ALLOWANCES ACTSU.K.
F41151 and 2U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4115Sch. 29 paras. 1, 2 repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
TAXES MANAGEMENT ACT 1970 c.9U.K.
3U.K.The Taxes Management Act 1970 shall have effect subject to the amendments made by paragraphs 4 to 10 below.
F41164U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4116Sch. 29 para. 4 repealed (with effect in accordance with s. 90 of the repealing Act) by Finance Act 1990 (c. 29), Sch. 19 Pt. 5, Note 2
F41175U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
6U.K.F4118. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4118Sch. 29 para. 6 repealed (6.4.2003 with effect in accordance with s. 723(1) of the repealing Act) by Income Tax (Earnings and Pensions) Act 2003 (c. 1), Sch. 8 Pt. 1 (with Sch. 7)
7F4119(1). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .U.K.
(2)In subsection (2) and (3) of that section for the words “this section” there shall be substituted the words “ subsection (1) above ”.
F4119(3). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4119Sch. 29 para. 7(1)(3) repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 4, Note 9
8(1)In subsection (1) of section 55 (recovery of tax not postponed) the following paragraph shall be [F4120substituted for paragraph (g)]—[for text see Taxes Management Act 1970 (c. 9), s. 55(1)(g) ].U.K.
(2)The following subsection shall be inserted in that section after subsection (6)—[for text see Taxes Management Act 1970 (c. 9), s. 55(6A)].
Textual Amendments
F4120Words in Sch. 29 para. 8 substituted (retrospectively) by Finance Act 1988 (c. 39), s. 146, Sch. 13 paras. 1, 13
9U.K.The following Table shall be substituted for the Table in section 98—[for text see Taxes Management Act 1970 (c. 9), s. 98].
10(1)The Taxes Management Act 1970, as amended by the Finance (No.2) Act 1987, shall have effect, after the day appointed under section 95 of the 1987 Act for the purposes of the provision in question, subject to the following amendments.U.K.
(2)In section 11(8) for “286” there shall be substituted “ 419 ”.
(3)In section 30(2A) F4121. . . for “87 of the Finance (No.2) Act 1987” there shall be substituted “ 826 of the principal Act ”.
(4)In section 87A—
(a)in subsection (1) for “243(4)” there shall be substituted “ 10 ”;
F4122(b). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(c)in subsection (4), in paragraph (a) for “85 of the Finance Act 1972” there shall be substituted “ 239 of the principal Act ”, and in paragraph (b) for “85” there shall be substituted “ 239 ”; and
(d)in subsection (5) for the words from “subsection” to “1972” there shall be substituted “ section 252(5) of the principal Act ”.
(5)In section 89 for “87 of the Finance (No.2) Act 1987” there shall be substituted “ 826 of the principal Act ”.
(6)In section 91(2A) for “90 of the Finance (No.2) Act 1987” there shall be substituted “ 10 of the principal Act ”.
F4123(7). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
(8)In section 109—
(a)in subsection (3) for “286” and “(4)” there shall be substituted “ 419 ” and “ (3) ”;
(b)in subsection (3A) for “(5)” and “286” (twice) there shall be substituted “ (4) ” and “ 419 ”.
Textual Amendments
F4121Words in Sch. 29 para. 10(3) repealed (with effect in accordance with Sch. 27 Pt. 3(28) Note of the repealing Act) by Finance Act 1998 (c. 36), Sch. 27 Pt. 3(28)
F4122Sch. 29 para. 10(4)(b) repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F4123Sch. 29 para. 10(7) repealed (with effect in accordance with Sch. 27 Pt. 3(28) Note of the repealing Act) by Finance Act 1998 (c. 36), Sch. 27 Pt. 3(28)
THE FRIENDLY SOCIETIES ACT (NORTHERN IRELAND) 1970 c.31 (N.I.)U.K.
F412411U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4124Sch. 29 para. 11 repealed (1.1.1994) by Friendly Societies Act 1992 (c. 40), s. 120(2), Sch. 22 Pt. I (with ss. 7(5), 93(4)); S.I. 1993/2213, art. 2(1), Sch.6 Appendix
THE FINANCE ACT 1973 c.51U.K.
F412512U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4125Sch. 29 para. 12 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
FRIENDLY SOCIETIES ACT 1974 c.46U.K.
13U.K.In section 7 of the Friendly Societies Act 1974 at the end of subsection (3) there shall be added the following—
“but nothing in this subsection shall apply with respect to—
(a)policies issued in respect of insurances made on or after 19th March 1985; or
(b)policies issued in respect of insurances made before that date which are varied on or after that date.”
THE SOCIAL SECURITY ACTSU.K.
F412614N.I.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4126Sch. 29 para. 14 repealed (1.7.1992) by Social Security (Consequential Provisions) (Northern Ireland) Act 1992 (c. 9), ss. 3, 7(2), Sch.1 (with Sch. 3 paras. 2, 4)
CAPITAL GAINS TAX ACT 1979 c.14U.K.
F412715U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4127Sch. 29 para. 15 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F412816U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4128Sch. 29 para. 16 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F412917U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4129Sch. 29 para. 17 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413018U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4130Sch. 29 para. 18 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413119U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4131Sch. 29 para. 19 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413220U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4132Sch. 29 para. 20 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413321U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4133Sch. 29 para. 21 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413422U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4134Sch. 29 para. 22 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413523U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4135Sch. 29 para. 23 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413624U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4136Sch. 29 para. 24 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413725U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4137Sch. 29 para. 25 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413826U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4138Sch. 29 para. 26 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F413927U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4139Sch. 29 para. 27 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
F414028U.K.. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4140Sch. 29 para. 28 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the amending Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 171, 201(3), Sch. 11 paras. 22, 26(2), 27)
ADMINISTRATION OF JUSTICE ACT 1985 c.61U.K.
30U.K.In paragraph 36(3) of Schedule 2 to the Administration of Justice Act 1985 for all the words preceding “any reference” there shall be substituted the words “ (3) In sections 745(3) and 778(3) of, and paragraph 14(5) of Schedule 15 to, the Income and Corporation Taxes Act 1988 ”.
LAW REFORM (MISCELLANEOUS PROVISIONS) (SCOTLAND) ACT 1985 c.73U.K.
31U.K.In Schedule 1 to the Law Reform (Miscellaneous Provisions) (Scotland) Act 1985 for the heading preceding paragraph 41 there shall be substituted the following—
“ Income and Corporation Taxes Act 1988;”and in paragragh 41 for “30(5)” there shall be substituted the words “ (3) and 778(3) of, and paragraph 14(5) of Schedule 15 to, the Income and Corporation Taxes Act 1988 ”.
TRANSLATION OF REFERENCES TO ENACTMENTS REPEALED AND RE-ENACTEDU.K.
32U.K.In the enactments specified in Column 1 of the following Table for the words set out or referred to in Column 2 there shall be substituted the words set out in the corresponding entry in Column 3.
| Enactment amended | Words to be omitted | Words to be substituted |
|---|---|---|
| In the Provisional Collection of Taxes Act 1968 c. 2 | ||
| Section 1(1A)(a) | 343 of the Income and Corporation Taxes Act 1970 | 476 of the Income and Corporation Taxes Act 1988 |
| 1(1A)(b) | 27 of the Finance Act 1984 | 479 of that Act |
| 5(1)(c) | from “243(6)” to “1972” | 8(5) of the Income and Corporation Taxes Act 1988 |
| 5(2) | from “the said” to “1972” | sections 8(5) and 822 of the 1988 Act (over-deductions from preference dividends before passing of annual Act) |
| In the Capital Allowances Act 1968 c.3 | ||
| F4141. . . | F4141. . . | F4141. . . |
| In the Finance Act 1969 c. 32 | ||
| Section 58(1)(a) | 204 of the Income and Corporation Taxes Act 1970 | 203 of the Income and Corporation Taxes Act 1988 |
| In the Taxes Management Act 1970 c. 9 | ||
| Section 6(1)(c) | 463 | 706 |
| F4142. . . | F4142. . . | F4142. . . |
| F4142. . . | F4142. . . | F4142. . . |
| F4142. . . | F4142. . . | F4142. . . |
| 11(6) | 85(4) of the Finance Act 1972 | 239(4) of the principal Act |
| F4143. . . | F4143. . . | F4143. . . |
| 15(7)(a) | from “section 196” to “1977” | sections 141, 142, 143, 145 or 154 to 165 of the principal Act |
| 15(11)(b) | Part II of the Finance Act 1976 | Part V of the principal Act |
| 80 to 82 | 34 to 36 | |
| F4144. . . | F4144. . . | F4144. . . |
| F4145. . . | F4145. . . | F4145. . . |
| F4146. . . | F4146. . . | F4146. . . |
| 30 | 47 or 48 (twice) | 824 or 825 of the principal Act or section 47 |
| 31 | all of subsection (3) | (3) The appeal shall be to the Special Commissioners if the assessment is made— |
| (a) by the Board; or | ||
| (b) under section 350, 426, 445, 740, 743(1) or 747(4)(a) of the principal Act; or | ||
| (c) under section 38 of the Finance Act 1973 or section 830 of the principal Act and is not an assessment to tax under Schedule E; | ||
| or if the appeal involves any question as to the application of Part XV or XVI of the principal Act. | ||
| 35(2)(b) | 187 | 148 |
| 42(3)(a) | 27 | 278 |
| 42(3)(c) | section 218 | subsection (5) of section 614 |
| 42(3)(c) | that section | section 615(3) of that Act |
| 47B | Schedule 5 to the Finance Act 1983 | Chapter III of Part VII of the principal Act |
| 47B | paragraph 5A(5) of that Schedule | section 294(5) of that Act |
| 55(1)(b) | 204 | 203 |
| 55(1)(c) | Schedule 20 to the Finance Act 1972 | Schedule 16 to the principal Act |
| 55(1)(e) | Schedule 14 to the Finance Act 1972 | Schedule 13 to the principal Act |
| F4147. . . | F4147. . . | F4147. . . |
| F4147. . . | F4147. . . | F4147. . . |
| F4148. . . | F4148. . . | F4148. . . |
| 63(3) (as substituted by Schedule 4 to the Debtors (Scotland) Act 1987 c.18) | 204 | 203 |
| 71(1) | Part XI | sections 6 to 12 and Parts VIII and XI |
| 78(1) | 89 | 43 |
| F4149 . . . | F4149 . . . | F4149 . . . |
| 78(5) | 533 | 839 |
| 86(2)(b) | 204 | 203 |
| 86(2)(d) | 14 to the Finance Act 1972 | 13 to the principal Act |
| 86(4) | 5 (three times) | 3 |
| 86(4) | 4(3) | 5(4) |
| 86(4) | 14 to the Finance Act 1972 | 13 to the principal Act |
| 86(4) | 243(4) | 10(1) |
| 86(4) | 344 | 478 |
| 87 | 14 (four times) | 13 |
| 87 | 20 (four times) | 16 |
| 87 | the Finance Act 1972 | the principal Act |
| F4150. . . | F4150. . . | F4150. . . |
| F4150. . . | F4150. . . | F4150. . . |
| F4150. . . | F4150. . . | F4150. . . |
| 91(3)(c) | 204 | 203 |
| F4146. . . | F4146. . . | F4146. . . |
| 93(3) | 204 | 203 |
| 94(2) | 240(5) or 246(3) | 7(2) or 11(3) |
| F4146. . . | F4146. . . | F4146. . . |
| 109(4) | 286(5) | 419(4) |
| 109(1)-(3),(5) | section 286 | sections 419 and 420 |
| 118(1) | 526(5) | 832(1) |
| 118(1) | 354 | 468 |
| 118(1) | 1970 | 1988 |
| Schedule 2, para.2(2), in column 1 of the Table | II of Part I | I of Part VII |
| 65(4) | 351(5) | |
| 3 | 2 | |
| para.2(2), in column 2 of the Table | 158(1) | 121(1), (2) |
| 315(3) | 441(3) | |
| 331 | 459 | |
| 332 | 460 | |
| 338 | 467 | |
| 339 | 484 | |
| 384 | 527 | |
| 389 | 534 | |
| 391 | 536 | |
| 392 | 538 | |
| 3, para.3,5 | 204 (three times) | 203 |
| para.5B | 65 of the Finance Act 1976 | 159 of the principal Act |
| para.8 | section 286 | sections 419 and 420 |
| para.8 | 15 of Schedule 16 to the Finance Act 1972 | 13 of Schedule 19 to the principal Act |
| last para. | from “11” to “to the principal Act” | 102, 113(5), 263(5) and (6), 343(10) and 783(9) of the principal Act, to paragraph 22 of Schedule 7 to the Income and Corporation Taxes Act 1970 |
| F4151. . . | ||
| F4151. . . | ||
| In the Friendly Societies Act (Northern Ireland) 1970 c. 31 (N.I.) | ||
| Section 1(5) | (2) and (3) respectively of section 337 of the Income and Corporation Taxes Act 1970 | (1) and (2) respectively of section 466 of the Income and Corporation Taxes Act 1988 |
| 82(4) | 226(13) of the Income and Corporation Taxes Act 1970 | 620(9) of the Income and Corporation Taxes Act 1988 |
| In the Finance Act 1971 c. 68 | ||
| Section 21 | the whole of subsection (6) | (6) Part II of Schedule 3 to this Act shall have effect. |
| F4152. . . | F4152. . . | F4152. . . |
| F4152. . . | F4152. . . | F4152. . . |
| F4152. . . | F4152. . . | F4152. . . |
| F4152. . . | F4152. . . | F4152. . . |
| F4152. . . | F4152. . . | F4152. . . |
| F4152. . . | F4152. . . | F4152. . . |
| F4152. . . | F4152. . . | F4152. . . |
| 69(2) | 1970 | 1988 |
| Schedule 3, para.8(1), (5) | the Taxes Act | the Income and Corporation Taxes Act 1970 |
| para.8(3) | the words from “sub-paragraphs” to “this Schedule)” | section 598(2) to (4) of the Taxes Act |
| para.8(4) | 1970 | 1970 or Chapter I of Part XIV of the Taxes Act |
| F4153. . . | F4153. . . | F4153. . . |
| F4153. . . | F4153. . . | F4153. . . |
| F4154F4153. . . | F4154F4153. . . | F4154F4153. . . |
| F4154F4153. . . | F4154F4153. . . | F4154F4153. . . |
| In the Finance Act 1972 c. 41 | ||
| F4155. . . | F4155. . . | F4155. . . |
| F4155. . . | F4155. . . | F4155. . . |
| F4155. . . | F4155. . . | F4155. . . |
| 134(2) | 1970 | 1988 |
| In the Finance Act 1973 c. 51 | ||
| F4156. . . | F4156. . . | F4156. . . |
| F4156. . . | F4156. . . | F4156. . . |
| F4156. . . | F4156. . . | F4156. . . |
| F4156. . . | F4156. . . | F4156. . . |
| F4156. . . | F4156. . . | F4156. . . |
| F4156. . . | ||
| F4156. . . | ||
| F4156. . . | ||
| F4156. . . | F4156. . . | F4156. . . |
| 38(2)(d) | 237(5) of the Taxes Act | 254(1) of the Taxes Act 1988 |
| 38(3) | from beginning to “such rights” | Any gains accruing on the disposal of exploration or exploitation rights |
| 38(3B) | 533 of the Taxes Act | 839 of the Taxes Act 1988 |
| 38(5) | the Taxes Act | the Taxes Act 1970 |
| 59 | all of subsection (2) | (2) In this Act— |
| (a) “the Taxes Act 1970” means the Income and Corporation Taxes Act 1970; and | ||
| (b) “the Taxes Act 1988” means the Income and Corporation Taxes Act 1988. | ||
| F4157. . . | F4157. . . | F4157. . . |
| F4157. . . | F4157. . . | F4157. . . |
| In the Friendly Societies Act 1974 c. 46 | ||
| Section 7(5) | (2) and (3) respectively of section 337 of the Income and Corporation Taxes Act 1970 | (1) and (2) respectively of section 466 of the Income and Corporation Taxes Act 1988 |
| 93(4) | 226(13) of the Income and Corporation Taxes Act 1970 | 620(9) of the Income and Corporation Taxes Act 1988 |
| F4158. . . | F4158. . . | F4158. . . |
| F4151. . . | F4151. . . | F4151. . . |
| In the Finance Act 1976 c. 40 | ||
| F4159. . . | F4159. . . | F4159. . . |
| F4159. . . | F4159. . . | F4159. . . |
| F4159. . . | F4159. . . | F4159. . . |
| F4159. . . | F4159. . . | F4159. . . |
| 131(2) | from beginning to “such a security” | A security issued by the Inter-American Development Bank |
| In the Finance Act 1978 c. 42 | ||
| F4160. . . | F4160. . . | F4160. . . |
| F4160. . . | F4160. . . | F4160. . . |
| F4151. . . | F4151. . . | F4151. . . |
| In the European Parliament (Pay and Pensions) Act 1979 c. 50 | ||
| Section 8(1) | subsections (1A) and (1B) of section 229 of the Income and Corporation Taxes Act 1970 | section 629(2) and (3) of the Income and Corporation Taxes Act 1988 |
| In the Finance Act 1980 c.48 | ||
| Section | ||
| F4161. . . | F4161. . . | F4161. . . |
| F4161. . . | F4161. . . | F4161. . . |
| F4161. . . | F4161. . . | F4161. . . |
| F4161. . . | F4161. . . | F4161. . . |
| 118 | the whole of subsection (3) | (3) The trustees of the National Heritage Memorial Fund shall be treated for the purposes of section 49(2) of the Finance Act 1974 and section 99 above as a body of persons established for charitable purposes only. |
| 122(2) | 1970 | 1970 and “the Taxes Act 1988” means the Income and Corporation Taxes Act 1988 |
| Schedule | ||
| F4151. . . | F4151. . . | F4151. . . |
| In the Finance Act 1981 c. 35 | ||
| F4151. . . | F4151. . . | F4151. . . |
| 139(2) | 1970 | 1988 |
| In the Housing (Northern Ireland) Order 1981 (S.I. No.156 N.I.3) | ||
| Article 146(3) | 341 (three times) | 488 |
| 146(3) | 1970 (three times) | 1988 |
| In the Iron and Steel Act 1982 c. 25 | ||
| Section 13(3) | 252(3) of the Income and Corporation Taxes Act 1970 | 343(3) of the Income and Corporation Taxes Act 1988 |
| 13(4) | 265(1) of the Income and Corporation Taxes Act 1970 | 345(1) of the Income and Corporation Taxes Act 1988 |
| In the Finance Act 1982 c. 39 | ||
| Section 27 | this Act (three times) | this Act or the Taxes Act 1988 |
| F4162. . . | F4162. . . | F4162. . . |
| F4162. . . | F4162. . . | F4162. . . |
| F4162. . . | F4162. . . | F4162. . . |
| 88(9)(a) | Chapter IV of Part II of the Finance Act 1985 | section 710 of the Taxes Act 1988 |
| 88(9)(b) | section 36 of the Finance Act 1984 | Schedule 4 to that Act |
| 88(9)(c) | VII of Part II of that Act | V of Part XVII of the Taxes Act 1988 |
| 147(1) | 532(1)(b) of the Taxes Act | 838 of the Taxes Act 1988 |
| 147(2), (3) | the Taxes Act | the Taxes Act 1970 |
| 157 | the whole of subsection (2) | (2) In this Act— |
| (a) “the Taxes Act 1970” means the Income and Corporation Taxes Act 1970; and | ||
| (b) “the Taxes Act 1988” means the Income and Corporation Taxes Act 1988. | ||
| F4162. . . | F4162. . . | F4162. . . |
| F4162. . . | F4162. . . | |
| F4162. . . | F4162. . . | F4162. . . |
| F4162. . . | F4162. . . | F4162. . . |
| F4162. . . | F4162. . . | F4162. . . |
| F4162. . . | F4162. . . | F4162. . . |
| 13, para.3(3)(a) | 463 of the Taxes Act | 706 of the Taxes Act 1988 |
| 21, para.3(2) | ||
| In the Finance Act 1983 c. 28 | ||
| Section 46(3) | Commission | Historic Buildings and Monuments Commission |
| F4151. . . | F4151. . . | F4151. . . |
| (ab) deep discount securities (within the meaning of Schedule 4 to the Income and Corporation Taxes Act 1988); nor | ||
| In the Telecommunications Act 1984 c. 12 | ||
| F4163. . . | F4163. . . | F4163. . . |
| 72(3)(b) | paragraph (a) of the proviso to section 21(3) of the Finance Act 1970 | section 592(5) of the Income and Corporation Taxes Act 1988 |
| 72(3) | II of Part II of the said Act of 1970 | I of Part XIV of that Act |
| F4163. . . | F4163. . . | F4163. . . |
| In the Finance Act 1984 c. 43 | ||
| F4151. . . | F4151. . . | F4151. . . |
| F4164. . . | F4164. . . | F4164. . . |
| 128 | 1970 | 1970; and “the Taxes Act 1988” means the Income and Corporation Taxes Act 1988 |
| Schedule 14, para.1(1) | VII of Part II of this Act | V of Part XVII of the Taxes Act 1988 |
| para.7(6)(b) | 45 of the Finance Act 1981 | 740 of the Taxes Act 1988 |
| para.8(6) | 45 of the Finance Act 1981 | 740 of the Taxes Act 1988 |
| para.12(7) | 45 of the Finance Act 1981 | 740 of the Taxes Act 1988 |
| para.15(2) | (5) of section 481 of the Taxes Act | (6) of section 745 of the Taxes Act 1988 |
| In the Inheritance Tax Act 1984 c. 51 | ||
| F4165. . . | ||
| F4166. . . | ||
| F4167. . . | ||
| In the Finance Act 1985 c. 54 | ||
| F4168. . . | F4168. . . | F4168. . . |
| F4168. . . | F4168. . . | F4168. . . |
| F4168. . . | F4168. . . | F4168. . . |
| F4151. . . | F4151. . . | F4151. . . |
| F4169. . . | F4169. . . | F4169. . . |
| 98(2) | 1970 | 1988 |
| F4168. . . | F4168. . . | F4168. . . |
| F4151. . . | F4151. . . | F4151. . . |
| In the Companies Act 1985 c. 6 | ||
| Section 209(3)(b) | 444 of the Income and Corporation Taxes Act 1970 | 670 of the Income and Corporation Taxes Act 1988 |
| F4170. . . | F4170. . . | F4170. . . |
| F4170. . . | F4170. . . | F4170. . . |
| In the Trustee Savings Bank Act 1985 c. 58 | ||
| Schedule 2 para.4(2) | Taxes Act (twice) | the Income and Corporation Taxes Act 1970 |
| 6(1) | 137 | 100 |
| (4) | 177 | 393 |
| (8) | 29 of the Finance Act 1973 | 410(1) to (6) of the Taxes Act |
| 7(2) | 26 of the Finance Act 1982 | 369 of the Taxes Act |
| 9(1) | 1970 | 1988 |
| In the Bankruptcy (Scotland) Act 1985 c. 66 | ||
| Schedule 3 Part I para.1(1) | 204 of the Income and Corporation Taxes Act 1970 | 203 of the Income and Corporation Taxes Act 1988 |
| para.1(2) | 69 of the Finance (No.2) Act 1975 | 559 of the Income and Corporation Taxes Act 1988 |
| In the Housing Associations Act 1985 c. 69 | ||
| Section 62(2) | 341 | 488 |
| 62(2) | 1970 | 1988 |
| In the Airports Act 1986 c. 31 | ||
| Section 77(2) | 1970 Act | Income and Corporation Taxes Act 1970 |
| 77(4) | 48(10) of the Finance Act 1981 | 400(9) of the 1988 Act |
| 77(5) | 261(2) of the 1970 Act | 408(2) of the 1988 Act |
| 77(5) | 262(1) of the 1970 Act | 409(1) of that Act |
| 77(5) | 262(2) | 409(2) |
| 77(6) | 1970 (twice) | 1988 |
| 77(6) | 258 to 264 | Chapter IV of Part X |
| In the Finance Act 1986 c. 41 | ||
| Section 24(4) | Finance Act 1978 | Taxes Act 1988 |
| F4151. . . | F4151. . . | F4151. . . |
| 114(2) | 1970 | 1970 and “the Taxes Act 1988” means the Income and Corporation Taxes Act 1988. |
| F4171. . . | F4171. . . | F4171. . . |
| F4171. . . | F4171. . . | F4171. . . |
| F4171. . . | F4171. . . | F4171. . . |
| F4171. . . | F4171. . . | F4171. . . |
| F4171. . . | F4171. . . | F4171. . . |
| F4171. . . | F4171. . . | F4171. . . |
| In the Gas Act 1986 c. 44 | ||
| Section 63(9) | 533 of the Income and Corporation Tax Act 1970 | 839 of the Income and Corporation Taxes Act 1988 |
| In the Insolvency Act 1986 c. 45 | ||
| F4172. . . | F4172. . . | F4172. . . |
| F4172. . . | F4172. . . | F4172. . . |
| F4173. . . | F4173. . . | F4173. . . |
| In the Building Societies Act 1986 c. 53 | ||
| Schedule 8, para.7 | Schedule 8 to the Finance Act 1986 | section 333 of the Income and Corporation Taxes Act 1988 |
| In the Financial Services Act 1986 c. 60 | ||
| Schedule 15, para.14(5) | 332 | 460(1) or 461(1) |
| para.14(5) | 1970 | 1988 |
| In the Companies (Northern Ireland) Order 1986 (S.I.No.1032 N.I.6) | ||
| Article 217(3)(b) | 444of the Income and Corporation Taxes Act 1970 | 670of the Income and Corporation Taxes Act 1988 |
| F4170. . . | F4170. . . | F4170. . . |
| F4170. . . | F4170. . . | F4170. . . |
| F4174. . . | F4174. . . | F4174. . . |
| In the Finance Act 1987 c. 16 | ||
| Section | ||
| 72 | 1970 | 1988 |
| In the Debtors (Scotland) Act 1987 c. 18 | ||
| Section 53(6) | 65(1A) | 351(2) |
| 53(6) | 1970 | 1988 |
| 63(9) | 65(1A) | 351(2) |
| 63(9) | 1970 | 1988 |
| In the Abolition of Domestic Rates Etc. (Scotland) Act 1987 c. 47 | ||
| Section 3(5) | the whole of paragraph (b) | (b) “retail prices index” has the meaning given by section 833 of the Income and Corporation Taxes Act 1988 |
| In the Finance (No.2) Act 1987 c. 51 | ||
| Section 84(1) | 247 of the Taxes Act | 12 of the Income and Corporation Taxes Act 1988 |
Textual Amendments
F4141Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4142Entries in Sch. 29 para. 32 Table repealed (with effect in accordance with s. 90 of the repealing Act) by Finance Act 1990 (c. 29), Sch. 19 Pt. 5, Note 2
F4143Sch. 29 para. 32 Table: entries omitted (13.8.2009) by virtue of The Finance Act 2009, Schedule 47 (Consequential Amendments) Order 2009 (S.I. 2009/2035), art. 1, Sch. para. 60(b)(i)
F4144Entry in Sch. 29 para. 32 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
F4145Entries in Sch. 29 para. 32 Table repealed by Finance Act 1989 (c. 26), Sch. 17 Pt. 5, Note 6
F4146Entries in Sch. 29 para. 32 Table repealed (1990-91 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 8, Note 6
F4147Entries in Sch. 29 para. 32 Table repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 4, Note 9
F4148Entry in Sch. 29 para. 32 Table repealed (3.4.1989) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 9, Note; S.I. 1989/473, art. 2
F4149Entry in Sch. 29 para. 32 Table repealed by Finance Act 1991 (c. 31, SIF 63:1), ss. 81, 123, Sch 19 Pt. V, Note 1
F4150Entries in Sch. 29 para. 32 repealed (with effect in accordance with Sch. 18 para. 17 of the repealing Act) by Finance Act 1996 (c. 8), Sch. 41 Pt. 5(8), Note
F4151Entries in Sch. 29 para. 32 repealed (6.3.1992 with effect as mentioned in s. 289(1)(2) of the repealing Act) by Taxation of Chargeable Gains Act 1992 (c. 12), ss. 289, 290, Sch. 12 (with ss. 60, 101(1), 172, 201(3), Sch. 11 paras. 22, 26(2), 27).
F4152Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4153Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4154Entries in Sch. 29 para. 32 Table repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 4, Note 9
F4155Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4156Sch. 29 para. 32 Table: entries omitted (13.8.2009) by virtue of The Finance Act 2009, Schedule 47 (Consequential Amendments) Order 2009 (S.I. 2009/2035), art. 1, Sch. para. 60(b)(ii)
F4157Sch. 29 para. 32 Table: entries repealed (1.4.2010 with effect in accordance with s. 381(1) of the repealing Act) by Taxation (International and Other Provisions) Act 2010 (c. 8), Sch. 10 Pt. 12 (with Sch. 9)
F4158Entry in Sch. 29 para. 32 repealed (1.7.1992) by Social Security (Consequential Provisions) Act 1992 (c. 6), ss. 3, 7(2), Sch. 1 and by Social Security (Consequential Provisions) (Northern Ireland) Act 1992 (c. 9), ss. 3, 7(2), Sch. 1
F4159Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4160Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4161Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4162Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4163Sch. 29 para. 32 Table: entries repealed (25.7.2003 for specified purposes, 29.12.2003 for further specified purposes) by Communications Act 2003 (c. 21), ss. 406(7), 411, Sch. 19(1),(with transitional provisions in Sch. 18); S.I. 2003/1900, art. 1(2), 2(1), 3(1), Sch. 1 (with art. 3(2) (as amended (8.12.2003) by S.I. 2003/3142, art. 1(3))); S.I. 2003/3142, art. 3(2) (with art. 11)
F4164Entry in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4165Sch. 29 para. 32 Table: entries relating to ss. 12(2), 151, 152 of the Inheritance Tax Act 1984 (c. 51) repealed (6.4.2006) by Finance Act 2004 (c. 12), Sch. 42 Pt. 3, Note (with Sch. 36)
F4166Sch. 29 para. 32 Table: entries relating to ss. 96, 102(1) of the Inheritance Tax Act 1984 repealed (1.4.2010 with effect in accordance with s. 1184(1) of the repealing Act) by Corporation Tax Act 2010 (c. 4), Sch. 3 Pt. 1 (with Sch. 2)
F4167Sch. 29 para. 32 Table: entry relating to s. 178(1) of the Inheritance Tax Act 1984 repealed (with effect in accordance with Sch. 43 Pt. 4(1) Note of the repealing Act) by Finance Act 2003 (c. 14), Sch. 43 Pt. 4(1)
F4168Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4169Entry in Sch. 29 para. 32 Table repealed (1988-89 and subsequent years) by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 4, Note 9
F4170Entries in Sch. 29 para. 32 Table repealed by Finance Act 1988 (c. 39), s. 148, Sch. 14 Pt. 7, Note 1
F4171Entries in Sch. 29 para. 32 Table repealed by Capital Allowances Act 1990 (c. 1), s. 164, Sch. 2
F4172Sch. 29 para. 32 Table: entries repealed (15.9.2003) by Enterprise Act 2002 (c. 40), s. 279, Sch. 26: S.I. 2003/2093, art. 2(1), Sch. 1 (with art. 4)
F4173Entry in Sch. 29 para. 32 repealed (1.7.1992) by Social Security (Consequential Provisions) Act 1992 (c. 6), ss. 3, 7(2), Sch. 1
F4174Entry in Sch. 29 para. 32 repealed (1.7.1992) by Social Security (Consequential Provisions) (Northern Ireland) Act 1992 (c. 9), ss. 3, 7(2), Sch. 1
Section 844.
SCHEDULE 30U.K.TRANSITIONAL PROVISIONS AND SAVINGS
Corporation tax payment datesU.K.
1(1)In this paragraph, an “old company” means a company to which section 244 of the 1970 Act applied in respect of the last accounting period ending before 17th March 1987.U.K.
(2)In relation to an old company —
(a)“the company's section 244 interval” means the interval after the end of an accounting period of the company which, in accordance with section 244 of the 1970 Act, was the period within which corporation tax assessed for that period was required to be paid; and
(b)“the period of reduction” means the number of whole days which are comprised in a period equal to one-third of the difference between nine months and the company⿿s section 244 interval.
(3)Subject to sub-paragraph (6) below, with respect to the first accounting period of an old company beginning on or after 17th March 1987, section 243(4) of the 1970 Act and section 10(1) of this Act (time for payment of corporation tax) shall have effect as if for the reference to nine months there were substituted a reference to a period which is equal to the company⿿s section 244 interval less the period of reduction.
(4)Subject to sub-paragraph (6) below, with respect to any accounting period of an old company which begins —
(a)after the accounting period referred to in sub-paragraph (3) above, but
(b)before the second anniversary of the beginning of that period,
section 10(1) of this Act shall have effect as if for the reference to nine months there were substituted a reference to a period equal to the previous payment interval less the period of reduction.
(5)In relation to any accounting period of an old company falling within sub-paragraph (4) above, “the previous payment interval”means the interval after the end of the immediately preceding accounting period within which corporation tax for that preceding period is required to be paid by virtue of section 243(4) of the 1970 Act or section 10(1) of this Act, as modified by this paragraph.
(6)If the accounting period referred to in sub-paragraph (3) above or any accounting period falling within sub-paragraph (4) above is less than 12 months, the sub-paragraph in question shall have effect in relation to that accounting period as if for the reference in that sub-paragraph to the period of reduction there were substituted a reference to the number of whole days comprised in a period which bears to the period of reduction the same proportion as that accounting period bears to 12 months.
(7)With respect to any accounting period of an old company which falls within sub-paragraph (3) or (4) above, section 86(4) of the Management Act (interest on overdue tax) shall have effect as if, in paragraph 5(a) of the Table (the reckonable date in relation to corporation tax), the reference to the nine months mentioned in section 243(4) of the 1970 Act or section 10(1) of this Act were a reference to the period which, under sub-paragraphs (3) to (6) above, is substituted for those nine months.
(8)In section 88(5)(e) of the Management Act (the date when corporation tax ought to have been paid) for the words from “where section 244(1)” to “the interval” there shall be substituted “ in the case of an accounting period in respect of which section 10(1) of the principal Act applies as modified by sub-paragraph 1(3) or (4) of Schedule 30 to that Act, at the end of the period which, under that sub-paragraph, is substituted for the period of nine months ”.
(9)With respect to any accounting period of an old company which falls within sub-paragraph (3) or (4) above, section 825 shall have effect as if, in subsection (8) in paragraph (a) of the definition of “the material date”, the reference to the nine months mentioned in section 10(1) were a reference to the period which, under sub-paragraphs (1) to (8) above is substituted for those nine months.
Duration of leasesU.K.
2U.K.F4175. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4175Sch. 30 paras. 2-4 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 292(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
3U.K.F4176. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4176Sch. 30 paras. 2-4 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 292(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
4U.K.F4177. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4177Sch. 30 paras. 2-4 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 292(2), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Repeal of section 136 of the Income Tax Act 1952: allowance of annual value of land as a business expenseU.K.
5U.K.F4178. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4178Sch. 30 para. 5 repealed (1.4.2009 with effect in accordance with s. 1329(1) of the repealing Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 292(3), Sch. 3 Pt. 1 (with Sch. 2 Pts. 1, 2)
Loss relief etc.U.K.
6(1)The substitution of this Act for the corresponding enactments repealed by this Act shall not alter the effect of any provision enacted before this Act (whether or not there is a corresponding provision in this Act) so far as it determines whether and to what extent —U.K.
(a)losses or expenditure incurred in, or other amounts referable to, a chargeable period earlier than those to which this Act applies may be taken into account for any tax purposes in a chargeable period to which this Act applies; or
(b)losses or expenditure incurred in, or other amounts referable to, a chargeable period to which this Act applies may be taken into account for any tax purposes in a chargeable period earlier than those to which this Act applies.
(2)Without prejudice to sub-paragraph (1) above, the repeals made by this Act shall not affect the following enactments (which are not re-enacted) —
(a)section 27(4) of the Finance Act 1952[1952 c. 33.] (restrictions on removal of six year time limit on carry forward of trading losses);
(b)section 29(3) of the Finance Act 1953[1953 c. 34.] (Isles of Scilly);
(c)section 17 of, and Schedule 3 to, the Finance Act 1954[1954 c. 44.] (company reconstructions before corporation tax) so far as in force by virtue of the saving in Part IV of Schedule 22 to the Finance Act 1965[1965 c. 25.] , and section 80(8) of the Finance Act 1965 (which amends Schedule 3 to the Finance Act 1954);
(d)section 82(4) of the Finance Act 1965 (losses allowable against chargeable gains);
(e)section 85 of the Finance Act 1965 (carry forward of surplus of franked investment income: dividends paid out of pre-1966-67 profits) and the enactments amending that section;
(f)paragraph 25 of Schedule 15 to the Finance Act 1965 (continuity of elections for purposes of corporation tax);
(g)paragraph 7 of Schedule 16 to the Finance Act 1965 (overseas trade corporations);
in so far as those enactments may be relevant to tax for any chargeable period to which this Act applies.
7(1)This paragraph shall apply with respect to claims for group relief in respect of any amount which is attributable —U.K.
(a)to writing-down allowances, within the meaning of Chapter II of Part I of the 1968 Act, or, as the case may require, Chapter I of Part III of the Finance Act 1971[1971 c. 68.] , in respect of expenditure incurred by the surrendering company on the provision of machinery or plant; or
(b)to initial allowances under section 56 of the 1968 Act (expenditure in connection with mines etc.) in respect of expenditure incurred by the surrendering company and falling within section 52(1) of that Act of 1971 (works in a development area or in Northern Ireland); or
(c)to allowances under section 91 of the 1968 Act in respect of expenditure incurred by the surrendering company on scientific research;
where the expenditure is incurred under a contract entered into by the surrendering company before 6th March 1973.
(2)Notwithstanding anything in section 410(1) to (6) or 413(7) to (10) or in Schedule 18 but subject to sub-paragraph (5) below, group relief may be claimed in respect of any such amount as is referred to in sub-paragraph (1) above if —
(a)immediately before 6th March 1973 —
(i)the surrendering company and the company claiming relief were members of a group of companies, and
(ii)throughout the period beginning on that date and ending at the end of the accounting period in respect of which the claim is made, there is no reduction in the rights of the parent company with respect to the matters specified in section 413(7)(a) and (b); or
(b)immediately before 6th March 1973 the company claiming relief was a member of a consortium and, throughout the period beginning on that date and ending at the end of the accounting period in respect of which the claim is made, there is
(i)no variation in the percentage of the ordinary share capital of the company owned by the consortium which is beneficially owned by that member, and
(ii)no reduction in the rights of that member (in respect of the company owned by the consortium) with respect to the matters specified in section 413(7)(a) and (b);
and in either case no such arrangements as are specified in section 410(1) or (2) have come into existence after 5th March 1973 with respect to any of the companies concerned and no variation is made in any such arrangements which are in existence on that date with respect to any of those companies.
(3)For the purposes of sub-paragraph (2)(a) above, “the parent company” means the company of which another member of the group referred to in that sub-paragraph was, immediately before 6th March 1973, a 75 per cent subsidiary, and the rights of the parent company referred to in that paragraph are —
(a)if the parent company is either the surrendering company or the company claiming relief, its rights in the other company; and
(b)in any other case, its rights in both the surrendering company and the company claiming relief.
(4)For the purposes of this paragraph an amount which the claimant company claims by way of group relief shall be treated as attributable to an allowance falling within any of paragraphs (a) to (c) of sub-paragraph (1) above to the extent that that amount would not have been available for surrender by the surrendering company if no such allowance had been available to the surrendering company in respect of the expenditure concerned.
(5)Sub-paragraph (2) above shall not apply if, during the period referred to in that sub-paragraph —
(a)there is a major change in the nature or conduct of a trade or business carried on by the relevant company; or
(b)the relevant company sets up and commences a trade or business [F4179, or begins to carry on a trade,] which it did not carry on immediately before 6th March 1973.
(6)In sub-paragraph (5) above —“a major change in the nature or conduct of a trade or business” has the same meaning as in section 245(1); and “the relevant company” means, if the machinery or plant to which the allowance relates was brought into use on or before 6th March 1978, the company claiming group relief and in any other case either that company or the company which if sub-paragraph (5) did not apply would be the surrendering company.
(7)This paragraph shall be construed as if it were contained in Chapter IV of Part X.
Textual Amendments
F4179Words in Sch. 30 para. 7(5)(b) inserted (1.4.2009 with effect in accordance with s. 1329(1) of the amending Act) by Corporation Tax Act 2009 (c. 4), Sch. 1 para. 292(4) (with Sch. 2 Pts. 1, 2)
Capital allowancesU.K.
8U.K.Without prejudice to paragraphs 6 and 7 above, where a person is, immediately before the commencement of this Act, entitled to a capital allowance by virtue of any enactment repealed by this Act, he shall not cease to be so entitled by reason only of that repeal, notwithstanding that the enactment in question is not re-enacted by this Act; and accordingly the provisions of this Act shall apply, with any necessary modifications, so far as may be necessary to give effect to any such entitlement.
Social security benefitsU.K.
9U.K.F4180. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4180Sch. 30 paras. 9, 14, 15, 19, 20 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
Children's settlements: irrevocable dispositions made before 22nd April 1936U.K.
10U.K.F4181. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4181Sch. 30 paras. 10-12 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
Pre-1959 settlementsU.K.
11U.K.F4182. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4182Sch. 30 paras. 10-12 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
12U.K.F4183. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4183Sch. 30 paras. 10-12 repealed (with effect in accordance with Sch. 29 Pt. 8(8) Note of the repealing Act) by Finance Act 1995 (c. 4), Sch. 29 Pt. 8(8)
General powers of amendment in Acts relating to overseas countriesU.K.
13U.K.Where under any Act passed before this Act and relating to a country or territory outside the United Kingdom there is a power to affect Acts passed or in force before a particular time, or instruments made or having effect under such Acts, and the power would but for the passing of this Act have included power to change the law which is reproduced in, or is made or has effect under, this Act, then that power shall include power to make such provision as will secure the like change in the law reproduced in, or made or having effect under, this Act notwithstanding that it is not an Act passed or in force before that time.
Double taxation agreementsU.K.
14U.K.F4184. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4184Sch. 30 paras. 9, 14, 15, 19, 20 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
SecuritiesU.K.
15U.K.F4185. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4185Sch. 30 paras. 9, 14, 15, 19, 20 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
Building societiesU.K.
16U.K.Any enactment relating to building societies contained in this Act which re-enacts an enactment which was an existing enactment for the purposes of section 121 of the Building Societies Act 1986[1986 c. 53.] shall continue to be an existing enactment for those purposes.
Pension businessU.K.
17U.K.Any reference to pension business in any enactment (other than an enactment repealed by this Act) which immediately before the commencement of this Act was such a reference by virtue of paragraph 11(3) of Part III of Schedule 5 to the Finance Act 1970[1970 c. 24.] shall not be affected by the repeal by this Act of that paragraph and accordingly the business in question shall continue to be known as pension business.
Stock reliefU.K.
18U.K.F4186. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4186Sch. 30 paras. 18, 18A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 352(3), Sch. 3 (with Sch. 2)
[F418718AU.K.F4188. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .]
Textual Amendments
F4188Sch. 30 paras. 18, 18A repealed (6.4.2005 with effect in accordance with s. 883(1) of the repealing Act) by Income Tax (Trading and Other Income) Act 2005 (c. 5), Sch. 1 para. 352(3), Sch. 3 (with Sch. 2)
Schedule E emolumentsU.K.
19U.K.F4189. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4189Sch. 30 paras. 9, 14, 15, 19, 20 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
Unitary statesU.K.
20U.K.F4190. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
Textual Amendments
F4190Sch. 30 paras. 9, 14, 15, 19, 20 repealed (31.1.2013) by Statute Law (Repeals) Act 2013 (c. 2), s. 3(2), Sch. 1 Pt. 10 Group 1
Continuity and construction of references to old and new lawU.K.
21(1)The continuity of the operation of the Tax Acts and of the law relating to chargeable gains shall not be affected by the substitution of this Act for the enactments repealed by this Act and earlier enactments repealed by and corresponding to any of those enactments (“the repealed enactments”).U.K.
(2)Any reference, whether express or implied, in any enactment, instrument or document (including this Act and any Act amended by this Act) to, or to things done or falling to be done under or for the purposes of, any provision of this Act shall, if and so far as the nature of the reference permits, be construed as including, in relation to the times, years or periods, circumstances or purposes in relation to which the corresponding provision in the repealed enactments has or had effect, a reference to, or as the case may be to things done or falling to be done under or for the purposes of, that corresponding provision.
(3)Any reference, whether express or implied, in any enactment, instrument or document (including the repealed enactments and enactments, instruments and documents passed or made after the passing of this Act) to, or to things done or falling to be done under or for the purposes of, any of the repealed enactments shall, if and so far as the nature of the reference permits, be construed as including, in relation to the times, years or periods, circumstances or purposes in relation to which the corresponding provision in this Act has effect, a reference to, or as the case may be to things done or falling to be done under or for the purposes of, that corresponding provision.
(4)Any reference to Case VIII of Schedule D, whether a specific reference or one imported by more general words, in any enactment, instrument or document shall, in relation to the chargeable periods to which section 843(1) applies, be construed as a reference to Schedule A, and for the purposes of sub-paragraph (2) above, Schedule A in this Act shall be treated as corresponding to Case VIII of Schedule D in the repealed enactments, and any provision of this Act or of any Act passed after 12th March 1970 and before this Act referring to Schedule A shall be construed accordingly.
Section 844.
SCHEDULE 31 U.K.REPEALS


Options/Help
Print Options
PrintThe Whole Act
You have chosen to open The Whole Act
The Whole Act you have selected contains over 200 provisions and might take some time to download. You may also experience some issues with your browser, such as an alert box that a script is taking a long time to run.
Would you like to continue?
You have chosen to open The Whole Act as a PDF
The Whole Act you have selected contains over 200 provisions and might take some time to download.
Would you like to continue?
You have chosen to open the Whole Act
The Whole Act you have selected contains over 200 provisions and might take some time to download. You may also experience some issues with your browser, such as an alert box that a script is taking a long time to run.
Would you like to continue?
You have chosen to open the Whole Act without Schedules
The Whole Act without Schedules you have selected contains over 200 provisions and might take some time to download. You may also experience some issues with your browser, such as an alert box that a script is taking a long time to run.
Would you like to continue?
You have chosen to open Schedules only
The Schedules you have selected contains over 200 provisions and might take some time to download. You may also experience some issues with your browser, such as an alert box that a script is taking a long time to run.
Would you like to continue?

Legislation is available in different versions:
Latest Available (revised):The latest available updated version of the legislation incorporating changes made by subsequent legislation and applied by our editorial team. Changes we have not yet applied to the text, can be found in the ‘Changes to Legislation’ area.
Original (As Enacted or Made): The original version of the legislation as it stood when it was enacted or made. No changes have been applied to the text.
See additional information alongside the content
Geographical Extent: Indicates the geographical area that this provision applies to. For further information see ‘Frequently Asked Questions’.
Show Timeline of Changes: See how this legislation has or could change over time. Turning this feature on will show extra navigation options to go to these specific points in time. Return to the latest available version by using the controls above in the What Version box.
Opening Options
Different options to open legislation in order to view more content on screen at once
More Resources
Access essential accompanying documents and information for this legislation item from this tab. Dependent on the legislation item being viewed this may include:
- the original print PDF of the as enacted version that was used for the print copy
- lists of changes made by and/or affecting this legislation item
- confers power and blanket amendment details
- all formats of all associated documents
- correction slips
- links to related legislation and further information resources
Timeline of Changes
This timeline shows the different points in time where a change occurred. The dates will coincide with the earliest date on which the change (e.g an insertion, a repeal or a substitution) that was applied came into force. The first date in the timeline will usually be the earliest date when the provision came into force. In some cases the first date is 01/02/1991 (or for Northern Ireland legislation 01/01/2006). This date is our basedate. No versions before this date are available. For further information see the Editorial Practice Guide and Glossary under Help.
More Resources
Use this menu to access essential accompanying documents and information for this legislation item. Dependent on the legislation item being viewed this may include:
- the original print PDF of the as enacted version that was used for the print copy
- correction slips
Click 'View More' or select 'More Resources' tab for additional information including:
- lists of changes made by and/or affecting this legislation item
- confers power and blanket amendment details
- all formats of all associated documents
- links to related legislation and further information resources
 All content is available under the Open Government Licence v3.0 except where otherwise stated. This site additionally contains content derived from EUR-Lex, reused under the terms of the Commission Decision 2011/833/EU on the reuse of documents from the EU institutions. For more information see the EUR-Lex public statement on re-use.